Category: Buying

  • Strafford, Pennsylvania: A Main Line Town Guide for Luxury Home Buyers

    Strafford, Pennsylvania: A Main Line Town Guide for Luxury Home Buyers

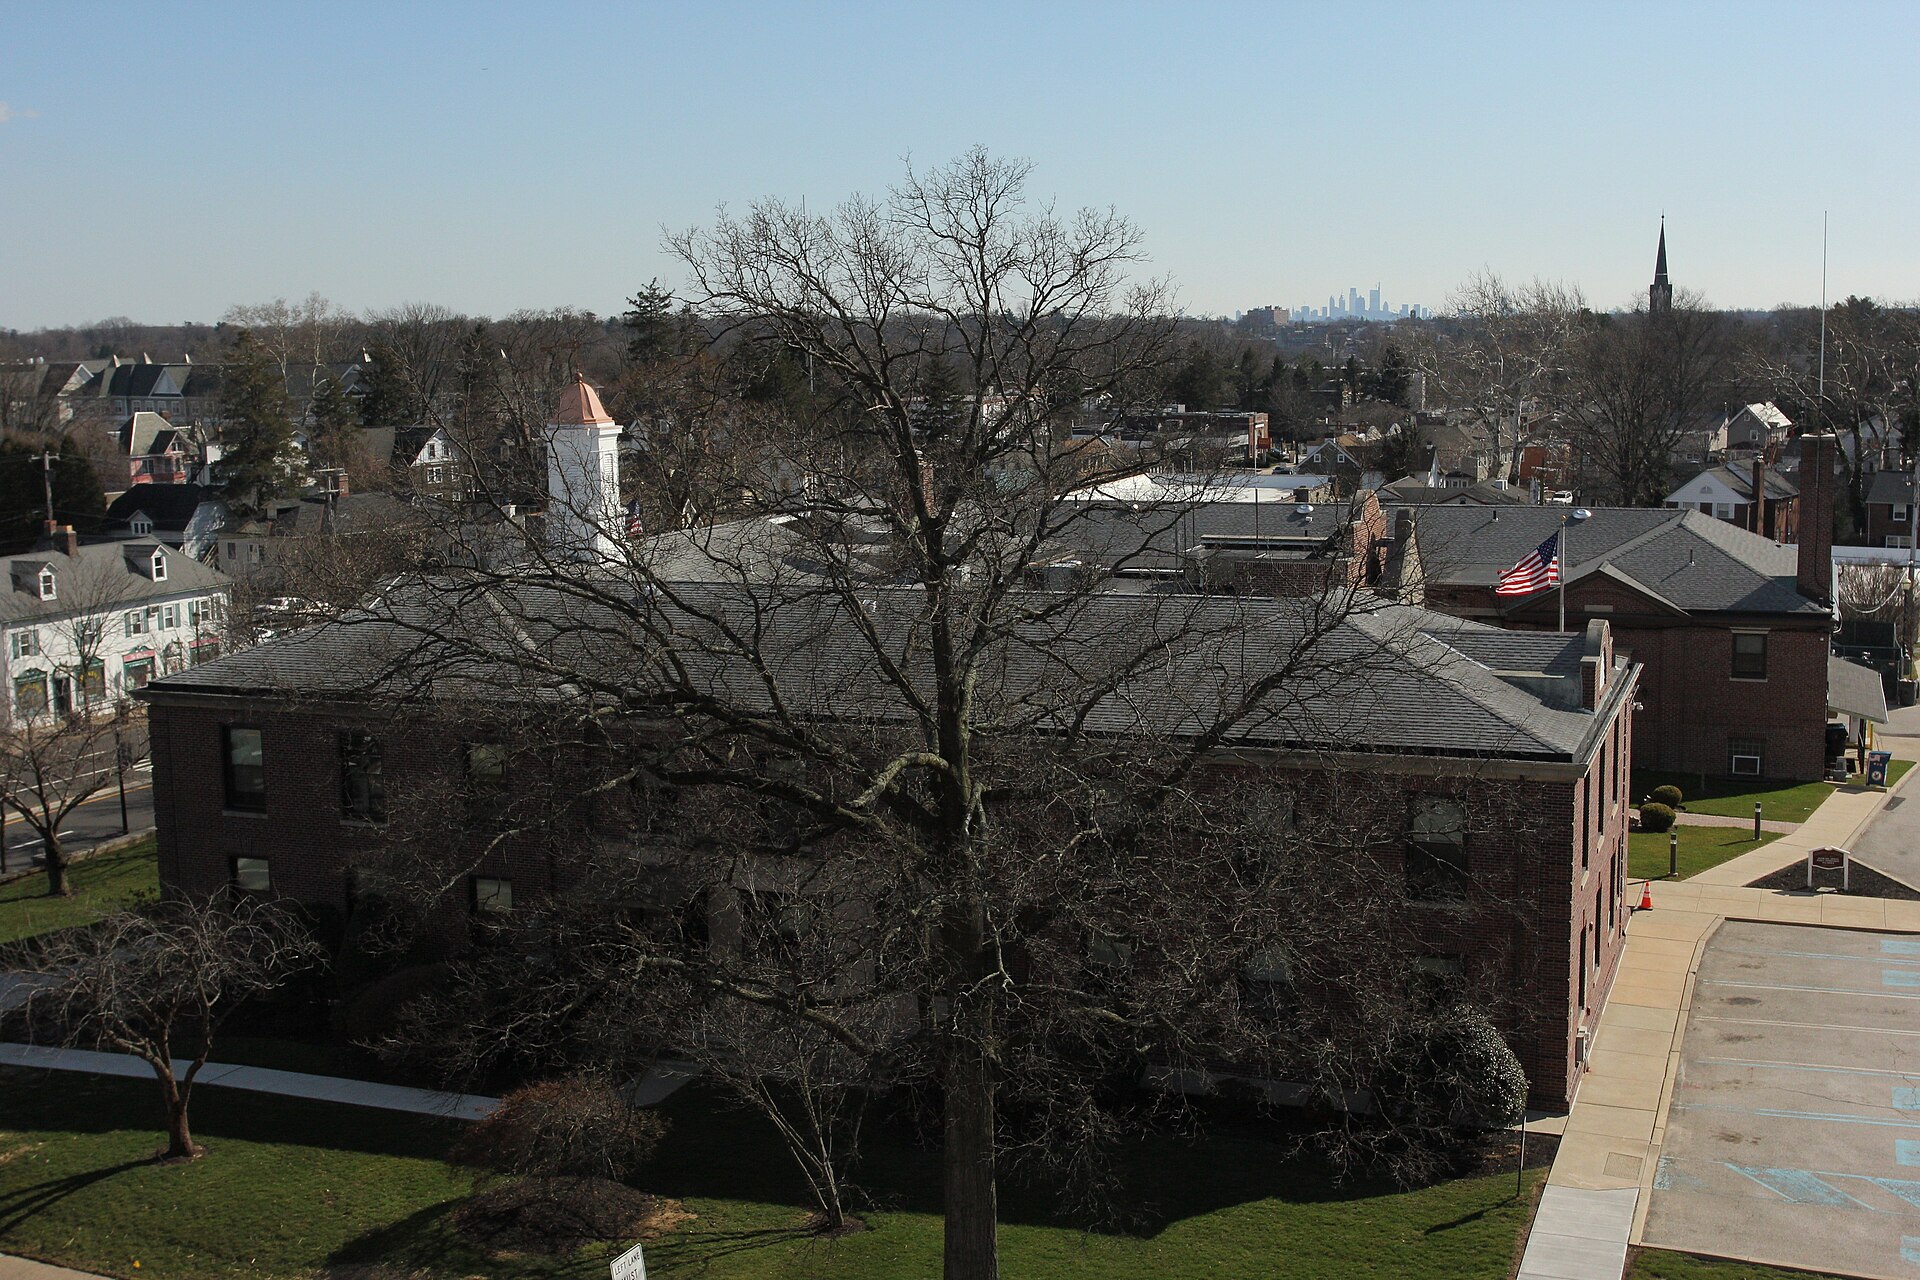
    Ask most people to name a Main Line town and you’ll hear Bryn Mawr, Wayne, or Villanova before you hear Strafford. That relative obscurity is exactly what makes it interesting. Strafford is a small unincorporated village straddling Tredyffrin and Easttown townships in Chester County, built around one of the original Pennsylvania Railroad stops on the historic “Main Line of Public Works” corridor. It has never tried to be a downtown, and it shows: there’s no commercial strip to speak of, just winding roads, mature trees, and houses set back on generous lots. For buyers who want Main Line prestige and train access without the density of Wayne or the price ceiling of Villanova, Strafford deserves a look.

    A brief history worth knowing

    Strafford takes its name from the Pennsylvania Railroad’s practice of naming stations after English and Welsh places, part of a branding effort in the late 19th century meant to lend the new commuter suburbs an air of Old World pedigree. The Strafford train station itself, a handsome late Victorian structure, is a recognized local landmark and one of the more architecturally distinctive stops on the line. That railroad heritage shaped everything that followed: large estates were subdivided gradually over decades rather than all at once, which is why Strafford’s lot sizes and architectural styles are so much more varied than in towns that were platted and built out in a single development wave.

    What the housing stock looks like

    Strafford’s homes span a wide range of eras and styles, which is part of its appeal. You’ll find stone farmhouses and carriage houses dating to the 19th century sitting near shingle-style and Colonial Revival homes from the early 1900s, along with a meaningful supply of mid-century and newer construction built on subdivided estate parcels. Lot sizes tend to be larger than in the denser Main Line boroughs, and many properties back up to wooded buffers or creek frontage along Gulph Creek and its tributaries. Because Strafford was never platted as a formal town grid, street patterns are irregular and lots vary widely in shape and privacy, which rewards buyers who walk properties in person rather than judging purely from listing photos.

    Access and commuting

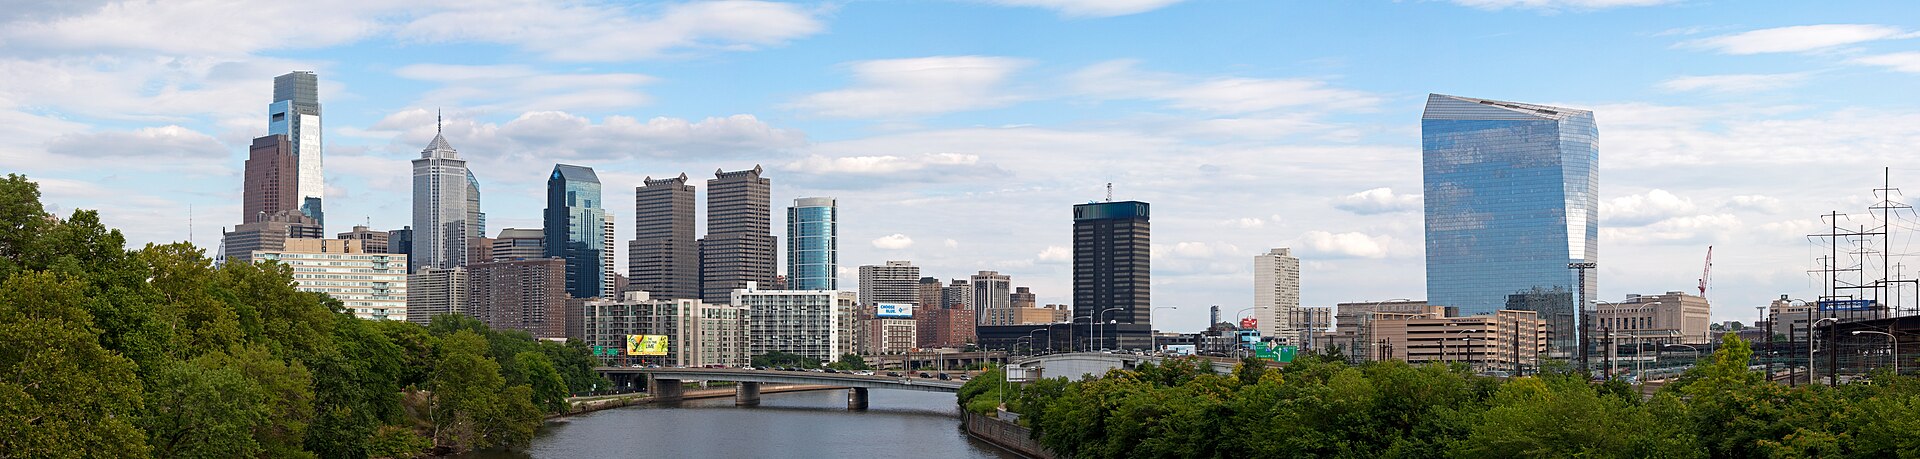
    The Strafford train station sits on SEPTA’s Paoli/Thorndale Regional Rail Line, offering a direct, relatively short ride into Suburban Station and Center City Philadelphia. For buyers who work downtown but want a quieter home base, that station access is a genuine differentiator over towns further out on the line. Strafford is also close to the Route 30 (Lancaster Avenue) corridor and sits a short drive from the King of Prussia interchange on the Pennsylvania Turnpike, which matters for buyers who split time between the city, the airport, and points further west.

    Schools and community character

    Strafford is served primarily by the Tredyffrin/Easttown School District, one of the top-performing public districts in the state and a significant draw for families relocating specifically for schools. The area also sits within easy reach of a cluster of well-regarded private and independent schools common throughout the Main Line. Community life here is understated by design — there’s no downtown business district, so residents tend to socialize through the schools, local clubs, and nearby Wayne or Devon rather than a Strafford-specific commercial core. Buyers who want walkable retail and restaurants at their doorstep should look instead toward Wayne or Ardmore; buyers who want quiet and privacy with those towns a short drive away often find Strafford the better fit.

    What tends to drive value

    In Strafford, three things consistently matter to resale value: proximity to the train station, lot privacy (tree cover, setback from the road, lack of through-traffic), and school district placement, since parts of the broader Strafford area can fall into different district boundaries depending on the exact parcel. Renovated historic stone homes with updated mechanical systems tend to command a premium over homes that look the part but haven’t been modernized underneath. Buyers considering a historic property here should budget time and money for a careful inspection of roofing, foundation, and systems — older stone construction can hide expensive surprises behind a beautiful facade.

    Practical considerations for a purchase

    Because Strafford spans two townships, buyers should confirm early in the process which township a specific parcel falls in, since Tredyffrin and Easttown each set their own zoning, permitting, and property tax rates. Septic and well service is less common here than in some outer Chester County towns, but buyers looking at older or larger estate-style parcels should still confirm public water and sewer availability rather than assume it. Wooded lots and creek-adjacent parcels are also worth checking for flood zone status and tree-related insurance considerations, since mature tree cover is part of Strafford’s appeal but can also mean higher maintenance costs after storms.

    Who Strafford suits

    Strafford tends to appeal to buyers who already know and love the Main Line but want more land and less visibility than Wayne, Villanova, or Bryn Mawr offer at a comparable price point. It’s a strong fit for train commuters who value privacy over walkability, and for buyers drawn to historic stone architecture who are willing to take on some renovation. It’s a less natural fit for buyers who want restaurants, boutiques, and nightlife within walking distance — that experience is a short drive away in Wayne, not a feature of Strafford itself.

    Frequently asked questions

    Is Strafford its own municipality?

    No. Strafford is an unincorporated village that spans parts of Tredyffrin and Easttown townships in Chester County. There’s no separate Strafford borough government, which means zoning, permitting, and property taxes are handled at the township level depending on exactly where a property sits.

    How does Strafford compare in price to Wayne or Villanova?

    Pricing varies significantly by lot, age, and condition, and current figures shift with the market, so it’s best to review active and recently sold comparables rather than rely on general reputation. Generally speaking, Strafford’s lack of a commercial core and lower profile can make comparable land and square footage more attainable than in Wayne’s downtown-adjacent blocks, though truly special historic properties command their own premium regardless of location.

    Which school district serves Strafford?

    Most of Strafford falls within the Tredyffrin/Easttown School District, though buyers should always confirm the exact district and elementary feeder pattern for a specific address before making an offer, since boundaries can be granular in unincorporated areas.

    If you’re weighing Strafford against other Main Line towns, James Kennedy can walk you through current inventory, recent comparable sales, and the tradeoffs between privacy and walkability across the corridor. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Bridge Loans and Home Equity Lines: Financing a Purchase Before You Sell in Philadelphia & South Jersey

    Bridge Loans and Home Equity Lines: Financing a Purchase Before You Sell in Philadelphia & South Jersey

    One of the most common binds a move-up buyer runs into is timing: the home you want to buy is available now, but most of your net worth is tied up in the home you have not yet sold. Selling first can mean losing the new home to another buyer, or scrambling to find temporary housing between closings. Buying first, without a plan, can mean carrying two mortgages at once. For luxury buyers in Philadelphia and South Jersey, a few established financing tools exist specifically to solve this problem — and understanding how they differ matters before you commit to one.

    Why Timing Becomes a Problem for Luxury Buyers

    At the higher end of the market, homes often move on a different schedule than the broader market, and inventory in the most desirable neighborhoods and towns can be genuinely scarce. When the right property appears, a buyer who has to wait for their current home to close before making an offer risks losing it. At the same time, most buyers do not want to carry two full mortgage payments indefinitely, and few want to make an offer contingent on their own home’s sale, since a contingent offer is often less competitive in a multiple-offer situation. Bridge financing and home equity borrowing exist to close that gap.

    How a Bridge Loan Works

    A bridge loan is a short-term loan secured against the equity in your current home, used to fund the down payment and sometimes the full purchase of the new home before the old one sells. Bridge loans are typically structured to be repaid quickly, often within six to twelve months, out of the proceeds when the current home sells. Because they are short-term and secured by real estate you already own, underwriting for bridge loans tends to focus heavily on the equity position in the departing home and a credible plan and timeline for selling it. Interest rates and fees on bridge loans are generally higher than on a standard mortgage, which is the trade-off for the flexibility they provide. Not every lender offers bridge loans, and terms vary considerably, so this is a product worth shopping specifically rather than assuming your everyday mortgage lender provides it.

    How a HELOC or Home Equity Loan Works

    A home equity line of credit, or a home equity loan, is a more widely available alternative that draws on the equity in your current home without necessarily requiring it to be sold on a fixed timeline. A HELOC in particular gives you a revolving credit line you can draw against for a down payment or other purchase costs, and it can be opened well in advance of when you actually need the funds — which is one of its advantages over a bridge loan. The trade-off is that a HELOC adds an additional lien and monthly payment obligation on the current home while you still own it, and approval depends on your income and debt profile supporting that added payment, not just the equity itself. For buyers with substantial equity and strong income, opening a HELOC ahead of a search can be a useful piece of financial preparation even before a specific new home is identified.

    Other Options Worth Discussing With Your Lender

    • Portfolio and asset-based lending: Some private and portfolio lenders will underwrite a purchase primarily against liquid assets or overall net worth rather than requiring the current home to be sold or a HELOC to be in place.
    • Contingent offers with a rent-back: In some markets, sellers will accept an offer contingent on the buyer’s home selling if it is paired with flexible terms, though this is highly dependent on how competitive the specific listing is.
    • Cross-collateralization: Certain lenders will allow the new purchase to be secured partly by the departing home directly, effectively combining features of a bridge loan with the primary mortgage.

    Comparing the Trade-offs

    Bridge loans tend to suit buyers who need funds for a specific, imminent purchase and have a clear, realistic timeline for selling their current home. HELOCs tend to suit buyers who want flexibility, may be searching for a while before finding the right property, and are comfortable carrying an additional payment in the interim. Both require a lender’s honest assessment of your current home’s likely sale price and timeline, so getting a realistic valuation early — not just an optimistic one — is an important first step regardless of which route you take.

    Questions to Ask a Lender Before Committing

    Before choosing either path, it is worth asking a lender directly how the product affects your debt-to-income ratio for qualifying on the new mortgage, what happens if your current home takes longer to sell than expected, what the total cost is in interest and fees, and whether the lender has experience with this structure specifically for move-up buyers in the local luxury market. A mortgage broker or lender who regularly works with high-net-worth buyers in Philadelphia and South Jersey will generally have more flexibility here than a lender focused primarily on conventional, owner-occupied purchases.

    Frequently asked questions

    Is a bridge loan the same as a home equity loan?

    No. A bridge loan is a short-term financing product built specifically to cover the gap between buying a new home and selling the current one, while a home equity loan or HELOC is a longer-standing product that draws on home equity and can be used for a purchase or for other purposes, without necessarily being tied to a sale timeline.

    Do I need to have my current home listed before I can get a bridge loan?

    Requirements vary by lender. Some want the home actively listed or under contract, while others will lend based on equity and a credible plan to list soon. This is a key point to clarify early with any lender you are considering.

    Which option is less expensive?

    It depends on how long you need the financing and your specific equity and income situation. A HELOC often carries a lower rate than a bridge loan but adds an ongoing payment obligation, while a bridge loan is typically more expensive per dollar borrowed but is structured to be short-lived. A lender can model the actual cost for your situation more precisely than a general comparison can.

    If you are weighing how to finance a move-up purchase in Philadelphia or South Jersey before your current home sells, James Kennedy can connect you with lenders experienced in bridge and equity-based financing and help sequence the sale and purchase to minimize risk. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Tenancy in Common vs. Joint Tenancy: How Unmarried Co-Buyers Should Title a Luxury Home

    Tenancy in Common vs. Joint Tenancy: How Unmarried Co-Buyers Should Title a Luxury Home

    More luxury home purchases today involve buyers who aren’t married to each other — long-term partners, siblings splitting an inheritance toward a shared property, friends pooling resources for a shore house, or business partners investing in real estate together. However you’re buying with someone else, the way title is held has real consequences: it determines what happens if one owner dies, what happens if the relationship or partnership ends, and how much flexibility each owner has to sell or borrow against their share. This is a decision worth making deliberately, with the help of a real estate attorney, rather than defaulting to whatever the title company suggests at closing.

    The Two Basic Options: Tenancy in Common and Joint Tenancy

    Both Pennsylvania and New Jersey recognize two primary ways for co-owners to hold title who are not married to one another:

    • Tenancy in common. Each owner holds a distinct, separate share of the property — which does not have to be equal — and that share can be sold, gifted, or left to heirs independently of the other owners. There is no automatic right of survivorship.
    • Joint tenancy with right of survivorship. Owners hold title together as a single unit, typically in equal shares, and when one owner dies, their share passes automatically to the surviving joint tenant(s), regardless of what their will says.

    The distinction sounds technical, but it shapes some of the most consequential outcomes of shared ownership.

    What Happens If One Owner Dies

    This is where the two structures diverge most sharply. Under joint tenancy with right of survivorship, the deceased owner’s interest passes directly and automatically to the surviving co-owner(s), bypassing probate entirely for that asset. Under tenancy in common, the deceased owner’s share becomes part of their estate and passes according to their will (or state intestacy law if there’s no will) — which could mean the surviving co-owner suddenly finds themselves sharing the property with the deceased owner’s children, other relatives, or anyone named in the will. For unmarried couples in particular, this is a critical point: without right of survivorship, a long-term partner has no automatic claim to a deceased partner’s share, however long they lived together.

    What Happens If the Relationship or Partnership Ends

    Co-ownership works well until it doesn’t. If a relationship ends, a business partnership dissolves, or co-owners simply disagree about the property’s future, either structure allows an owner to force a resolution through a legal action called partition, which can result in a court-ordered sale if the owners can’t agree privately. A well-drafted co-ownership agreement, discussed below, is the single best way to avoid ending up in that process.

    Financing Considerations for Co-Buyers

    Lenders generally evaluate all co-borrowers’ income, assets, and credit together when underwriting a jumbo loan, and all owners on title are typically required to be on the mortgage as well. If one buyer is contributing a larger down payment or has substantially stronger credit, it’s worth discussing with your lender and attorney how that imbalance should be reflected in ownership percentages and in any co-ownership agreement, rather than assumed to be a 50/50 split by default.

    Written Co-Ownership Agreements: Why They Matter

    Whichever title structure you choose, a separate written co-ownership (or “tenants in common”) agreement is worth the legal fees it costs to draft. A good agreement typically addresses:

    • How ownership percentages were determined and how they’re recorded
    • How ongoing costs — mortgage, taxes, insurance, maintenance, capital improvements — are shared
    • What happens if one owner wants to sell and the other doesn’t, including a right of first refusal
    • How a buyout would be valued and financed if one owner wants out
    • What happens in the event of death, disability, or a dispute

    This document does the work that a prenuptial agreement does for married couples — it settles the hard questions in advance, while everyone is getting along, rather than in the middle of a dispute.

    Should You Consider an LLC or Trust Instead?

    For some co-buyers, particularly business partners or larger family groups pooling resources for a vacation property, holding title through an LLC or trust can offer additional structure, privacy, and flexibility — including the ability to transfer membership interests without the same complications as transferring real property directly. This comes with its own costs, tax considerations, and lender requirements (jumbo lenders don’t always finance LLC-held property on the same terms as individual buyers), so it’s a conversation to have with both a real estate attorney and a tax advisor before you’re under contract.

    State-Specific Notes for Pennsylvania and New Jersey

    Both Pennsylvania and New Jersey default to tenancy in common when a deed to unmarried co-owners doesn’t specify otherwise — joint tenancy with right of survivorship must be explicitly stated on the deed to apply. This makes it especially important to review exactly how title will be worded before closing, rather than assuming a particular outcome. An attorney licensed in the state where the property is located should review the deed language directly.

    Frequently asked questions

    Can co-owners hold unequal shares under tenancy in common?

    Yes. Tenancy in common allows owners to hold any percentage split they agree to — for example, 70/30 based on differing down payment contributions — and each owner’s share can be transferred independently of the others.

    Does joint tenancy avoid probate entirely?

    It avoids probate for that specific property, since the surviving owner’s title passes automatically outside of the estate process. Other assets the deceased owner held would still go through probate according to their own titling.

    Is a co-ownership agreement legally binding if it’s separate from the deed?

    Yes, a properly drafted and signed co-ownership agreement is a binding contract between the owners, separate from and in addition to the deed itself. It’s the document that governs the practical, day-to-day, and exit-scenario questions the deed doesn’t address.

    If you’re buying a luxury property with a partner, sibling, or friend and want to talk through how to structure ownership, James Kennedy can help you think through the real estate side and connect you with a qualified attorney for the legal structure — call 215-267-8479 or email jameskennedy@unlockedteam.com.

  • Rydal and Meadowbrook, Pennsylvania: An Abington Township Guide for Luxury Home Buyers

    Rydal and Meadowbrook, Pennsylvania: An Abington Township Guide for Luxury Home Buyers

    Tucked into Abington Township in Montgomery County, Rydal and Meadowbrook are two of the quieter, more established pockets of the Philadelphia suburbs. They don’t have the name recognition of the Main Line or Chestnut Hill, but longtime Philadelphia-area buyers know them well: mature tree canopies, generously sized lots, a mix of stately older homes and well-built newer construction, and a level of privacy that’s increasingly hard to find inside the beltway of closer-in suburbs. For buyers who want suburban scale and quiet without sacrificing a reasonable commute into Center City, this corner of Abington Township deserves a serious look.

    Where Rydal and Meadowbrook Are, and Why Buyers Look Here

    Rydal and Meadowbrook sit along the eastern edge of Abington Township, bordering Jenkintown and not far from Elkins Park, in a part of Montgomery County that developed earlier than some of the townships further out. That earlier development pattern is part of the appeal: streets were laid out with generous setbacks and lot sizes decades ago, so many properties here offer the kind of acreage and mature landscaping that’s difficult to replicate on a newly subdivided lot. Buyers drawn to Rydal and Meadowbrook tend to want that established, settled feel — homes with real trees, real gardens, and neighbors who have often been there for years.

    The Housing Stock: What to Expect

    The architecture in this part of Abington Township is varied but leans traditional. Expect to see:

    • Center-hall colonials and stone farmhouses dating from the early-to-mid twentieth century
    • Tudor and Cotswold-style homes with slate roofs and leaded glass detailing
    • A smaller number of newer or extensively renovated homes that blend contemporary systems with traditional exteriors
    • Larger parcels, some approaching or exceeding an acre, which is unusual this close to Philadelphia

    Because much of the housing stock predates modern building codes, buyers should budget time and diligence for mechanical systems, roofing, and any prior additions — points covered in more detail below.

    Getting Around: Rydal Station and the Commute to Center City

    One of the practical advantages of this location is Rydal Station on SEPTA’s Warminster Line, which offers a direct regional rail connection into Center City Philadelphia. For buyers who want suburban living without giving up rail access to the city, that’s a meaningful draw — it puts Rydal and Meadowbrook in a similar commuting category to better-known Main Line stops, without the same price premium that name recognition can carry. Road access via Route 611 (Old York Road) and proximity to major arteries also make driving into the city or out to King of Prussia straightforward.

    Schools and Community Considerations

    Homes in Rydal and Meadowbrook fall within the Abington School District, one of the larger public districts in Montgomery County. As with any home purchase where schools matter to your decision, confirm the specific attendance zone for a property you’re considering directly with the district — boundaries can shift and are the kind of detail worth verifying rather than assuming based on a neighboring address. Some buyers in this price range also look at nearby independent schools; if that’s part of your plan, James can walk you through the options within a reasonable drive.

    Comparing Rydal and Meadowbrook to Nearby Jenkintown and Elkins Park

    Buyers cross-shopping this part of Montgomery County often consider Jenkintown and Elkins Park alongside Rydal and Meadowbrook. Jenkintown offers a more walkable, borough-style downtown with shops and restaurants within a short walk of many homes — a different lifestyle than the more spread-out, private feel of Rydal and Meadowbrook. Elkins Park brings a similar mix of grand older homes but with its own distinct architectural history. None of the three is strictly “better” — the right fit depends on whether you value walkable amenities, architectural pedigree, or the quieter, larger-lot privacy that Rydal and Meadowbrook tend to offer.

    What to Know Before You Buy

    A few practical points worth raising with your agent and inspector when you tour homes here:

    • Age of major systems. Many homes have had multiple owners and renovations over the decades; ask for documentation on when the roof, HVAC, and electrical service were last updated.
    • Septic vs. public sewer. Most of this area is on public sewer, but it’s worth confirming for any property on a larger or more rural-feeling parcel.
    • Additions and permits. Older homes sometimes carry additions completed without full permitting. A title search and municipal permit history check can surface this before you’re under contract.
    • Property lines on larger lots. A current survey is worth requesting, particularly on properties with mature landscaping or outbuildings that may sit close to a boundary.

    Frequently asked questions

    Is Rydal considered part of Jenkintown?

    No. Rydal is an unincorporated community within Abington Township, adjacent to but administratively separate from the Borough of Jenkintown. Homes in Rydal are governed by Abington Township, not Jenkintown Borough, which matters for zoning, taxes, and municipal services.

    How far is Rydal from Center City Philadelphia?

    Rydal Station is roughly a 30-minute regional rail ride into Center City on SEPTA’s Warminster Line, and the drive covers a similar distance depending on traffic and route. It’s comparable to many well-regarded Main Line commutes.

    Are there newer-construction options in this area, or is it mostly older homes?

    The majority of the housing stock is older, reflecting the area’s early development, but newer construction and substantial renovations do come to market from time to time, particularly on larger parcels. James can set up alerts for new listings that match this criteria as they become available.

    If you’d like to see what’s currently available in Rydal, Meadowbrook, or elsewhere in Abington Township, or want a private tour of a specific property, reach out to James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Portfolio Loans and Asset-Based Financing: How Self-Employed and High-Net-Worth Buyers Qualify for Luxury Mortgages

    Portfolio Loans and Asset-Based Financing: How Self-Employed and High-Net-Worth Buyers Qualify for Luxury Mortgages

    Many of the most qualified buyers in the Philadelphia and South Jersey luxury market do not fit neatly into a conventional mortgage box. Business owners with fluctuating income, retirees living off investment portfolios, and high-net-worth individuals whose wealth is concentrated in assets rather than a steady paycheck often find that a standard, income-documentation-based loan simply was not designed with them in mind. Fortunately, an entire category of lending exists specifically to serve these buyers. Understanding the options before you start shopping for a home can save significant time and frustration during the financing process.

    Why Traditional Underwriting Often Doesn’t Fit

    Conventional and jumbo mortgages typically rely heavily on two years of tax returns, W-2 income, and debt-to-income ratios calculated from documented earnings. This works well for salaried buyers but poorly for a business owner who legitimately minimizes taxable income through deductions, a recently retired buyer drawing from a portfolio rather than a paycheck, or someone whose net worth is real but whose annual “income” on paper looks modest. None of these situations reflect an inability to afford a home; they reflect a mismatch between how the buyer’s finances actually work and how conventional underwriting is built to measure them.

    What Is a Portfolio Loan

    A portfolio loan is a mortgage that a lender originates and keeps on its own balance sheet rather than selling to Fannie Mae, Freddie Mac, or another investor on the secondary market. Because the lender is not bound by the standardized guidelines those investors require, it has more flexibility to set its own underwriting criteria, weigh a buyer’s full financial picture, and make case-by-case judgments. Portfolio loans are common at private banks, credit unions, and regional lenders who want to build long-term relationships with high-net-worth clients, and they are frequently used for jumbo loan amounts above conventional limits.

    Asset-Based and Asset-Depletion Lending

    For buyers whose wealth sits in investment accounts rather than a paycheck, asset-based (sometimes called asset-depletion) lending offers a different qualification path. Instead of calculating income from tax returns, the lender calculates a hypothetical monthly income by dividing a portion of the buyer’s liquid assets over a set period, such as several years or an actuarial life expectancy figure, and uses that number to qualify the loan. This approach can work well for retirees, buyers who recently sold a business, or anyone sitting on significant investment or retirement assets who wants to preserve those assets rather than liquidate them for a large cash purchase.

    Bank Statement Loans for Business Owners

    Self-employed buyers are often better served by a bank statement loan, which qualifies income based on twelve to twenty-four months of business or personal bank deposits rather than tax returns. Because business owners frequently take legitimate deductions that reduce taxable income without reducing actual cash flow, a bank statement loan can paint a more accurate picture of what a buyer can genuinely afford. These loans typically carry a modestly higher interest rate than a conventional mortgage in exchange for the more flexible documentation standard, which is often a worthwhile trade for a buyer who would otherwise struggle to qualify at all through traditional means.

    Pledged-Asset and Securities-Backed Lines of Credit

    Another option some luxury buyers use, either alongside or instead of a traditional mortgage, is a securities-backed line of credit or pledged-asset mortgage, in which an investment portfolio is used as collateral rather than being sold to generate a down payment. This can allow a buyer to purchase a home, in some cases with cash-like speed and terms, while keeping an investment portfolio intact and continuing to benefit from its growth. Because this approach ties financing to the value and performance of the pledged portfolio, it comes with its own risks, particularly if the market value of the securities drops, and should be discussed carefully with a financial advisor as well as a lender.

    What Lenders Typically Look For Instead of W-2 Income

    • Liquid asset reserves, including investment and retirement accounts, and how they are distributed across account types
    • Bank statement deposit history for self-employed borrowers, generally over twelve to twenty-four months
    • Overall net worth and the composition of assets, including real estate, business interests, and securities
    • Credit history and existing debt obligations, much as with any mortgage
    • The specific property itself, since portfolio lenders often place additional weight on collateral value for unique or high-value homes

    Working With the Right Team

    Not every loan officer or bank regularly handles portfolio, asset-based, or bank statement lending, and buyers who go to a lender unfamiliar with these products can end up wasting time on an application that was never going to fit their situation. It is worth asking directly, early in the process, whether a lender has experience specifically with self-employed or asset-based borrowers in the jumbo loan range common to Philadelphia and South Jersey’s luxury market. A real estate agent who works regularly with luxury buyers can often point toward lenders and private banks with a track record in this space.

    Frequently asked questions

    Do portfolio and asset-based loans have higher interest rates?

    Rates and terms vary by lender and by the buyer’s overall financial picture, and can be higher, comparable to, or in some cases better than conventional jumbo rates depending on the relationship and the assets involved. Because pricing is negotiated case by case rather than set by standardized guidelines, it is worth comparing more than one lender before committing.

    Can a self-employed buyer with strong income still qualify for a conventional mortgage?

    Sometimes, particularly if tax returns show consistent, well-documented income over multiple years. Many self-employed buyers do qualify conventionally, but those who take significant deductions or have variable year-to-year income often find a bank statement or portfolio loan is a better fit even if they could technically qualify another way.

    Is a pledged-asset line of credit the same as a home equity loan?

    No. A pledged-asset or securities-backed line of credit uses an investment portfolio as collateral, not the home itself, and is typically arranged before or independent of the home purchase. A home equity loan or line of credit, by contrast, is secured by equity in real estate the borrower already owns.

    Financing a luxury home purchase often involves more moving pieces than a standard mortgage, and having the right guidance matters. James Kennedy works with buyers across Philadelphia and South Jersey to connect them with lenders suited to their specific financial picture. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Willistown and Radnor Hunt Country, Pennsylvania: A Chester County Guide for Luxury Equestrian Estate Buyers

    Willistown and Radnor Hunt Country, Pennsylvania: A Chester County Guide for Luxury Equestrian Estate Buyers

    Tucked between the manicured lawns of the Main Line and the rolling farmland of central Chester County, Willistown Township and the surrounding Radnor Hunt country represent one of the Philadelphia region’s most understated pockets of wealth. This is not a place of grand entrance gates and cul-de-sacs; it is a place of stone farmhouses, post-and-rail fencing, and land held by the same families for generations. For buyers drawn to privacy, acreage, and an equestrian way of life within reasonable reach of Center City, this corridor deserves a closer look.

    What Sets Willistown Apart

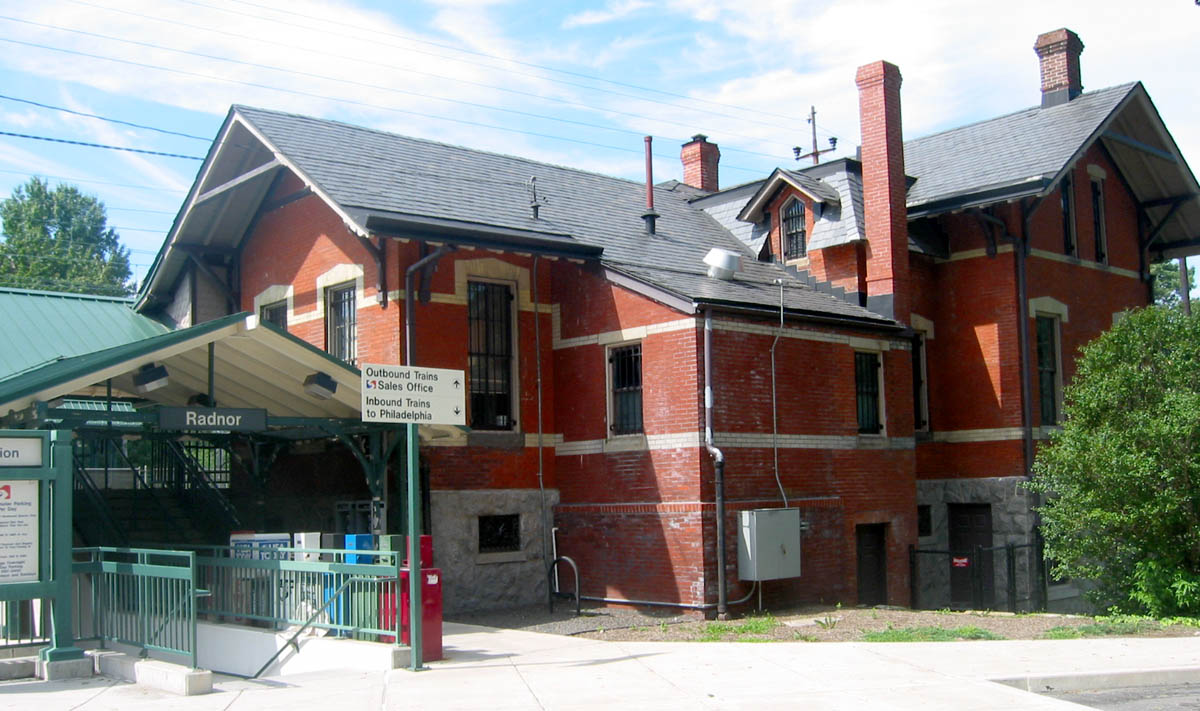
    Willistown sits west of Radnor and south of Malvern, occupying a quieter tier of the Main Line than the train-station towns most buyers picture first. There is no downtown commercial strip to speak of; the character here comes from open land, wooded stream valleys, and a road network that still follows eighteenth-century property lines. Much of the appeal is what you do not see: no strip malls, no dense subdivisions, and long stretches where a mile of driving passes only a handful of homes.

    That scarcity of development is not an accident. Decades of active land conservation by local trusts and easement holders have kept large tracts of Willistown and its neighboring townships out of the subdivision pipeline permanently, which is part of why land here tends to hold its value and why turnover can be slow. Buyers who want this lifestyle should expect a patient search rather than a large, fast-moving inventory of listings.

    The Radnor Hunt Legacy

    The Radnor Hunt Club, one of the oldest organized fox hunts in the country, anchors the cultural identity of this area. Its influence extends well beyond hunt season: the surrounding countryside is threaded with informal riding trails, hunt-country social traditions, and a community of owners who maintain their properties with an eye toward horses, whether or not they ride themselves. The annual Radnor Hunt races draw visitors from across the region and are one of the more visible expressions of a lifestyle that otherwise stays fairly private.

    Buyers relocating from more suburban markets sometimes underestimate how much this culture shapes day-to-day life here. Fencing styles, barn architecture, and even landscaping choices in hunt country tend to follow long-standing, informal conventions. A property that ignores them can feel out of place to neighbors, even if nothing about it violates any ordinance.

    Land, Privacy, and Conservation Easements

    A significant share of the acreage in and around Willistown carries a conservation easement, meaning future development rights have been permanently restricted, often in exchange for tax benefits to a prior owner. This is generally good news for buyers seeking privacy and protected views, since it guarantees a neighboring farm cannot become a housing development. It does require careful review during due diligence, however, since an easement can also limit what a new owner is allowed to build, from additional structures to fencing and even certain agricultural uses. An easement’s terms are recorded and should be reviewed by an attorney familiar with conservation restrictions before a buyer commits.

    Stone Farmhouses vs. Custom Equestrian Estates

    Inventory in this area generally falls into two broad categories. The first is historic stone farmhouses, many dating to the 1700s or 1800s, often expanded and updated over decades while retaining original fieldstone walls, wide-plank flooring, and period detailing. These homes reward buyers who enjoy the character of an older structure and are prepared for the maintenance considerations that come with one. The second category is custom-built equestrian estates, constructed more recently on larger parcels with the barn, ring, and paddocks designed alongside the main house from the start. These tend to offer more predictable mechanical systems and layouts suited to modern life, at the trade-off of less architectural history.

    What to Evaluate on a Horse Property

    Whether a property already has equestrian infrastructure or a buyer intends to add it, a few items deserve particular attention before closing:

    • Barn condition and configuration, including stall count, ventilation, and whether the structure meets a buyer’s specific discipline (dressage, hunter/jumper, trail riding, or breeding)
    • Pasture acreage and rotation potential relative to the number of horses a buyer intends to keep
    • Water access and quality, since most properties in this area rely on private wells rather than municipal water
    • Riding ring footing and drainage, which can be expensive to correct if poorly built
    • Access to trail networks and whether any easements grant or restrict riding access across neighboring land
    • Septic system capacity, particularly on older farmhouses that may have been upgraded incrementally over the years

    Commuting and Everyday Life

    Despite its rural feel, Willistown remains within a manageable drive of Center City Philadelphia and close to the Route 202 and Route 30 corridors that connect to King of Prussia, Wayne, and West Chester. Regional rail access is less direct here than in station towns like Wayne or Paoli, so most residents rely on a car for daily commuting. For buyers whose work allows hybrid or flexible schedules, this trade-off of drive time for land and privacy has become increasingly appealing.

    Frequently asked questions

    Do I need to own horses to live in Willistown or Radnor Hunt country?

    No. Many residents in this area do not ride or keep horses at all; they are drawn instead by the privacy, acreage, and rural character that the equestrian culture helps preserve. That said, buyers should expect the surrounding community and landscape to reflect hunt-country traditions even if they do not personally participate.

    How does a conservation easement affect what I can do with a property?

    Each easement is a unique legal document, so the restrictions vary. Some limit only future subdivision, while others also restrict new construction, fencing, or land use. A buyer should always request and review the recorded easement, along with any related agreements with the holding land trust, before finalizing an offer.

    Is this area a good fit for a full-time equestrian operation, or mainly personal use?

    Both exist here. Some properties are set up as small, personal facilities for a few horses, while others are established as larger private or commercial equestrian operations. The right fit depends on acreage, zoning, and the specific infrastructure already in place, all of which should be evaluated against a buyer’s plans before purchase.

    If you are considering a move to Willistown, Radnor Hunt country, or anywhere along the Main Line and want a guide who understands both the luxury market and the practical realities of an equestrian property, James Kennedy can help. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com to start the conversation.

  • Right of First Refusal and Board Approval: How Some Philadelphia Luxury Condo Buildings Vet New Owners

    Right of First Refusal and Board Approval: How Some Philadelphia Luxury Condo Buildings Vet New Owners

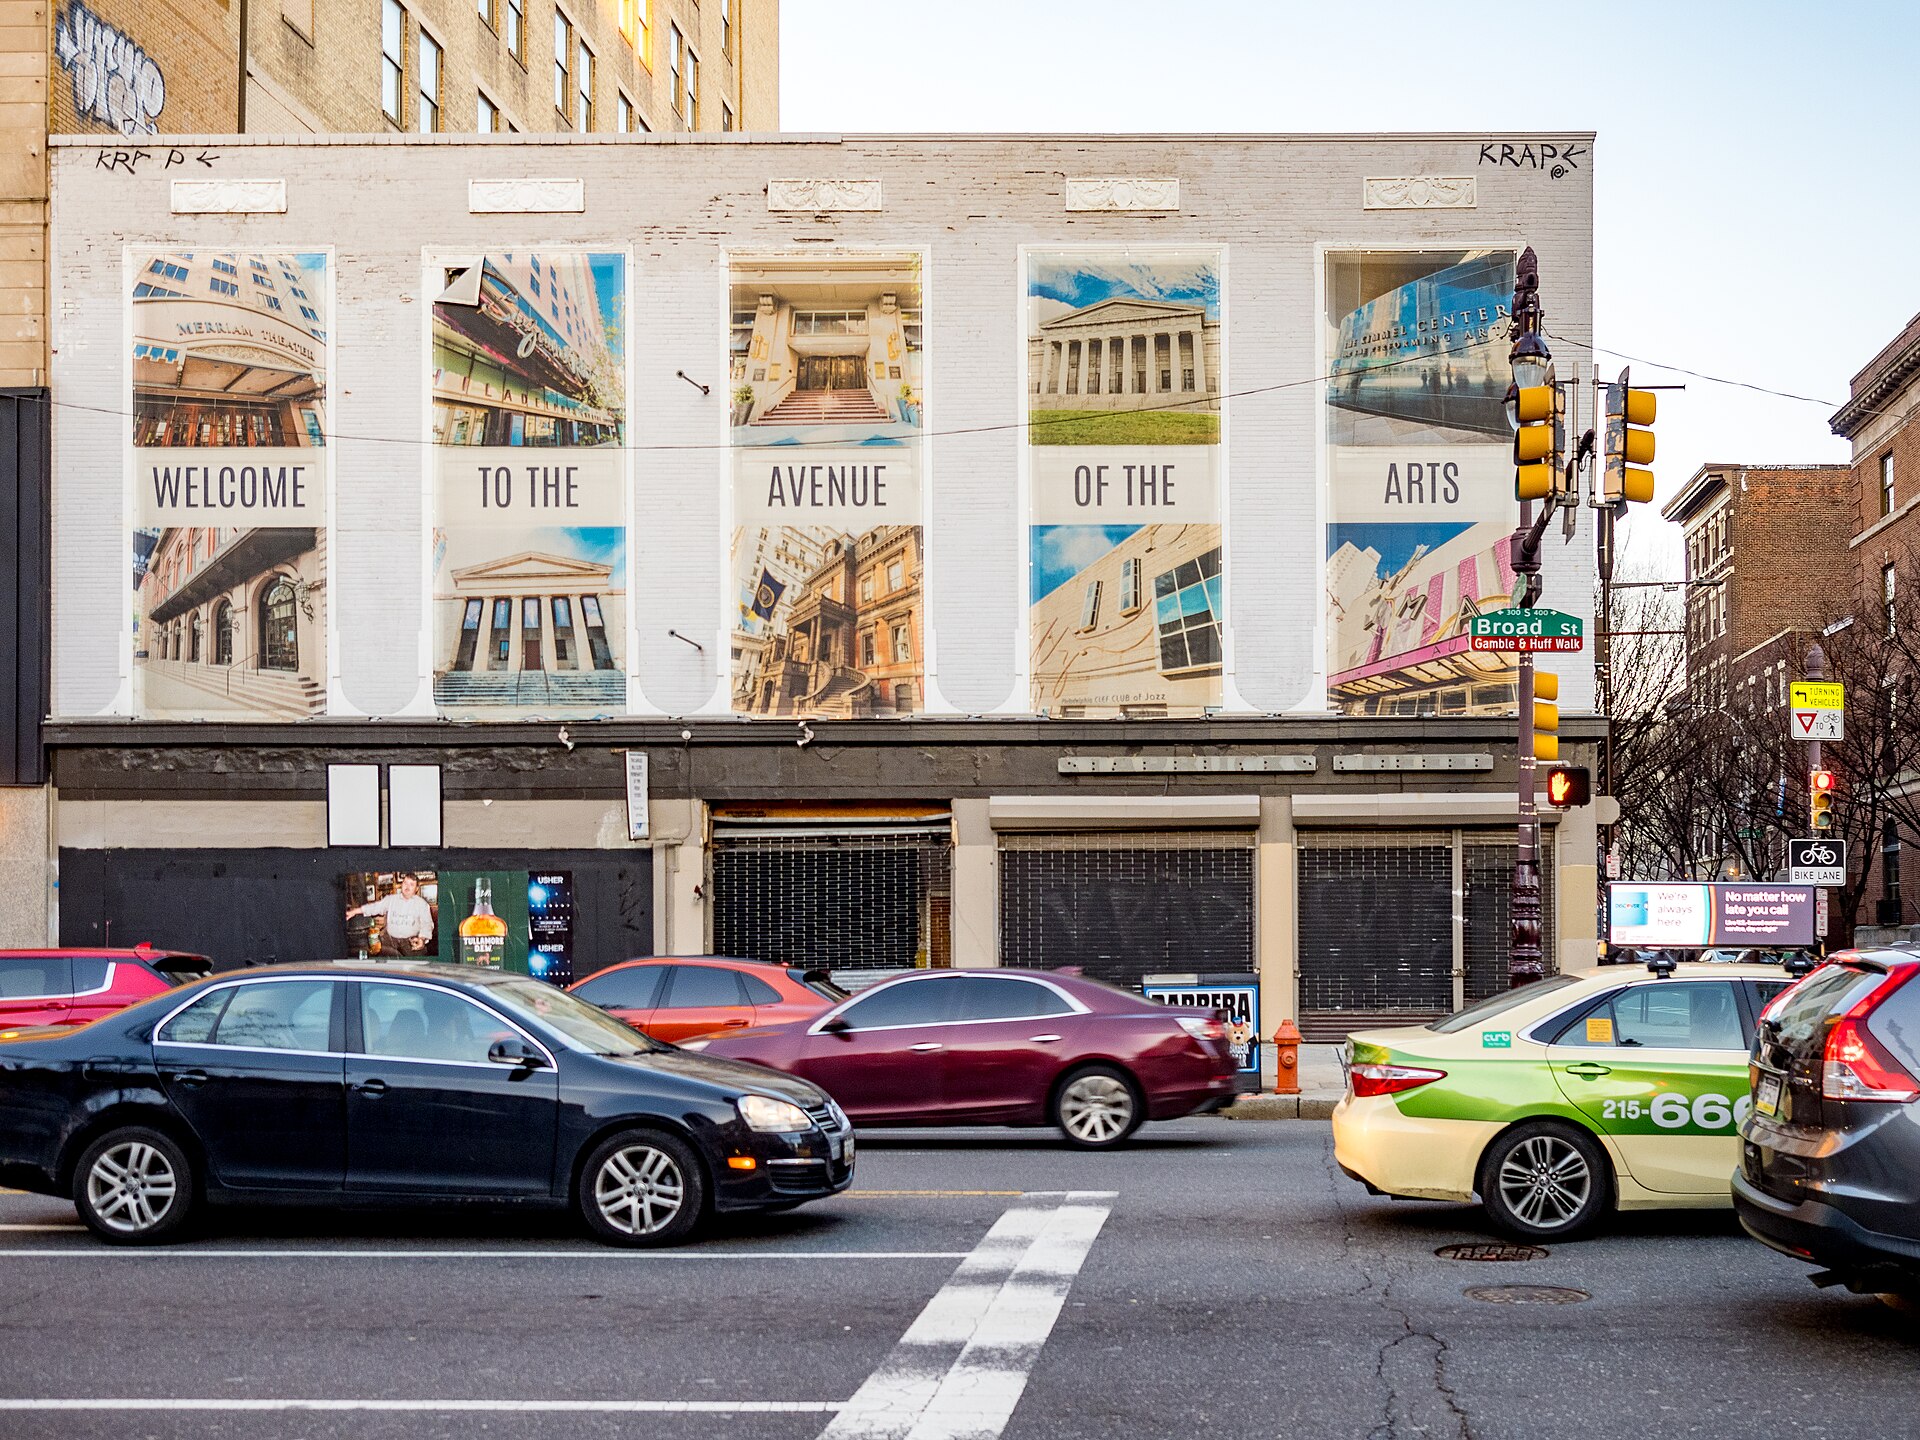
    Most condominium purchases in Philadelphia work the way buyers expect: negotiate a price, satisfy inspection and financing contingencies, close, and move in. But a smaller number of the city’s boutique and historic-conversion buildings, particularly some of the more established addresses in and around Rittenhouse Square, Society Hill, and the Avenue of the Arts, include governance provisions that add another layer to the process — a right of first refusal, a board approval requirement, or both. Buyers who have purchased condos elsewhere are sometimes surprised to encounter these provisions in Philadelphia, so it is worth understanding what they mean and how they can affect a purchase timeline before you fall in love with a specific unit.

    What Is a Right of First Refusal?

    A right of first refusal, sometimes shortened to ROFR, gives the condominium association, or in some cases the other unit owners collectively, the ability to purchase a unit under the same terms a seller has already negotiated with an outside buyer before that sale can proceed. In practice, this usually means that once a seller accepts an offer, the signed agreement is submitted to the board or association, which then has a defined window of time to decide whether to exercise its right to buy the unit itself on the same terms, or to waive that right and allow the sale to the original buyer to move forward.

    In the vast majority of cases, the association waives its right and the sale proceeds as negotiated. The provision exists less as a routine obstacle and more as a mechanism some older or smaller buildings use to retain some control over ownership composition, particularly in structures that were converted from apartments, hotels, or other historic uses and carry governing documents drafted decades ago.

    Board Approval Processes in Certain Buildings

    Separately from, or sometimes alongside, a right of first refusal, a smaller number of Philadelphia’s boutique and historic condo buildings maintain a board approval process for incoming owners. This is far less common in Philadelphia than in New York’s cooperative buildings, but it does exist in some addresses, and it typically involves submitting a purchase application, financial documentation, and sometimes personal or professional references, followed by an interview with a board committee. The stated purpose is usually financial: boards want assurance that an incoming owner can meet monthly assessment obligations and any special assessments the building may face.

    Because these processes are building-specific rather than standardized across the city, the details, timeline, and level of scrutiny vary considerably. Some buildings run a light-touch process that amounts to a brief document review, while others expect a more thorough application and formal interview.

    How This Differs from Standard HOA Rules

    • Standard condo association rules govern fees, maintenance, and use of common areas, but do not restrict who can buy a unit
    • A right of first refusal specifically gives the association or other owners the option to purchase before an outside sale closes
    • Board approval adds a vetting step — application, documentation, sometimes an interview — before a sale can close
    • Most Philadelphia condos have neither provision; where they exist, they are concentrated in a handful of older, boutique, or converted buildings

    What Buyers and Sellers Should Confirm Early

    For a seller, the practical step is straightforward: know before listing whether the building’s governing documents include a right of first refusal or approval requirement, and disclose that clearly so buyers and their agents can plan around it. For a buyer, the right move is to request the condominium’s governing documents, including the declaration, bylaws, and any resale certificate, as early in the process as possible, ideally before submitting an offer on a unit in an older or boutique building. Ask the listing agent directly whether either provision applies, and if so, what the association’s typical timeline and process have been for recent sales.

    These documents will also spell out the exact procedural details: how long the association has to exercise or waive a right of first refusal, what documentation a board approval application requires, and whether there is any fee associated with the review.

    Building This Into Your Purchase Timeline

    A right of first refusal or board approval process typically adds days to weeks to a closing timeline, not months, but that additional time needs to be built into contract deadlines, mortgage rate locks, and any moving or lease-end plans on the buyer’s side. If you are also competing for a unit using an escalation clause or a tight closing date to strengthen your offer, it is worth discussing with your agent how an approval contingency interacts with those strategies, since a seller weighing offers may view one with a lengthy building approval process differently than a comparable offer without one.

    Frequently asked questions

    Do most Philadelphia condo buildings have a right of first refusal?

    No. The great majority of Philadelphia condominiums have no such provision, and buyers can proceed through a standard purchase and closing process. It appears mainly in a limited number of older, boutique, or historically converted buildings, so it is worth confirming for any specific address rather than assuming it applies broadly.

    How long does board approval typically take?

    Timelines vary by building since there is no citywide standard, but where a formal review exists it commonly adds a few weeks to the process for document review and any required interview, which is why confirming the requirement and its typical timeline early is valuable.

    Can a right of first refusal delay or kill a deal?

    It can add time to a closing while the association decides whether to exercise or waive its right, but outright exercise of the right, where the association actually elects to purchase the unit itself, is uncommon. Buyers and sellers should still account for the review period in their contract timeline.

    If you are considering a purchase in one of Philadelphia’s boutique or historic condo buildings and want a clear read on a specific building’s governing documents before you make an offer, James Kennedy can help you review the details and plan your timeline accordingly. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Home Warranties for Luxury Homes: What They Cover and What They Don’t

    Home Warranties for Luxury Homes: What They Cover and What They Don’t

    A home warranty comes up in a lot of luxury transactions, usually as something a seller offers to make a listing more attractive or a buyer requests as part of negotiations. It sounds reassuring — a service contract that covers repairs on major systems and appliances after closing — but the fine print on these plans varies enormously, and the gap between what a buyer expects and what a standard policy actually covers tends to widen as the home gets larger and more elaborate. Understanding that gap before relying on a warranty, rather than after a claim gets denied, is worth the time.

    What a Home Warranty Covers

    A residential home warranty is a service contract, typically purchased annually, that pays for repair or replacement of specific home systems and appliances when they fail from normal wear and use — think a furnace, water heater, central air system, plumbing, electrical, and kitchen appliances like a range, dishwasher, or built-in refrigerator. It is distinct from homeowners insurance, which covers sudden and accidental damage from events like fire, storms, or theft, not gradual mechanical failure.

    In a resale transaction, it’s common for a seller to purchase a one-year home warranty for the buyer as a closing gift or negotiating concession, giving the new owner a safety net during the first year in a home whose systems they don’t yet know well. Buyers can also purchase their own warranty independently at any point.

    Where Home Warranties Fall Short for Luxury Properties

    Standard home warranty plans are built around typical residential systems, and luxury homes often have equipment that falls outside that standard scope or is covered only through costly add-ons, if at all. Elevators, whole-house generators, geothermal systems, high-end water filtration, smart-home automation systems, wine refrigeration units, pool and spa equipment, and specialty appliances from boutique manufacturers frequently aren’t included in a base plan, and even when a rider is available for one of these items, coverage limits and payout caps may fall well short of what an actual repair or replacement costs on high-end equipment.

    Warranty companies also typically cap payouts per repair or per contract term, and those caps are set with a typical home in mind. A luxury furnace, a commercial-grade range, or a large zoned HVAC system can cost significantly more to repair or replace than the caps built into a standard plan, leaving the homeowner to cover the difference even with an active warranty in place.

    Home Warranties vs. Manufacturer and Builder Warranties

    It’s worth distinguishing a home warranty service contract from the manufacturer warranties that come with new appliances and systems, and from the structural and systems warranties that often accompany new construction. A manufacturer warranty covers a specific product against defects, usually for a set number of years, and is unrelated to who owns the home. A new construction builder warranty typically covers workmanship and certain systems for a defined period after closing and is a separate protection with its own claims process. A home warranty service contract sits alongside these, generally kicking in for wear-and-tear failures once other coverage has lapsed or for items those warranties don’t address, and buyers of newer luxury construction should understand which protection actually applies to a given system before assuming a home warranty is the relevant coverage.

    Should a Luxury Seller Offer One?

    Offering a home warranty can still be a reasonable goodwill gesture or negotiating tool in a luxury sale, particularly for buyers who are nervous about an older home’s systems or who are relocating from out of the area and won’t have local contractors lined up right away. But sellers considering this should look specifically at plans with higher coverage caps and riders for the specific high-end systems in the home — pool equipment, generators, elaborate HVAC zoning — rather than defaulting to the most basic plan available, since a warranty that clearly won’t cover the home’s actual equipment does little to reassure a sophisticated buyer.

    What Buyers Should Ask Before Relying on One

    Before treating a home warranty as meaningful protection, buyers should read the actual contract rather than the marketing summary, paying attention to per-item payout caps, what counts as pre-existing or improperly maintained equipment (a common basis for denied claims), which specific systems and appliances are named, and what add-on riders exist for anything unusual in the home. It’s also worth asking the seller or listing agent for documentation on the age and maintenance history of major systems regardless of whether a warranty is in place — a warranty is not a substitute for knowing the real condition of what’s being purchased, and a thorough inspection remains the better source of truth about what’s likely to need attention.

    Frequently asked questions

    Does a home warranty replace the need for a home inspection?

    No. A home inspection assesses the current condition of the home’s systems and structure before purchase, while a home warranty is a service contract that may pay for certain repairs after the fact. They serve different purposes, and a warranty should never be treated as a reason to skip or shorten an inspection.

    Can a buyer negotiate for a higher-tier home warranty plan instead of the seller’s standard offer?

    Yes, this is a reasonable point of negotiation, especially for a home with specialty systems. A buyer can ask the seller to upgrade to a plan with higher coverage limits or specific riders, or to credit the buyer enough at closing to purchase their own more comprehensive plan.

    Are pools, generators, and elevators ever covered by a standard home warranty?

    Sometimes, but usually only through optional add-on coverage at extra cost, and often with lower payout caps than the item would actually cost to repair. Buyers with these systems should confirm coverage specifics in writing rather than assuming they’re included.

    For guidance on what protections make sense for a specific Philadelphia or South Jersey luxury property, buying or selling, James Kennedy is available to talk through the details. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Party Walls and Shared Structures: What Philadelphia Rowhome and Twin Owners Need to Know

    Party Walls and Shared Structures: What Philadelphia Rowhome and Twin Owners Need to Know

    Philadelphia’s luxury market includes plenty of detached homes in Chestnut Hill or on the Main Line, but a significant share of the city’s highest-value real estate — in Rittenhouse Square, Society Hill, Fitler Square, Queen Village, and dozens of other neighborhoods — sits in rowhomes and twins that share at least one structural wall with the house next door. That shared wall, known legally as a party wall, comes with its own set of rights, obligations, and potential friction points that buyers moving from detached homes elsewhere often haven’t had to think about.

    What a Party Wall Actually Is

    A party wall is a wall that sits on or along the boundary line between two properties and is shared by both. In a Philadelphia rowhome block, the walls separating each house from its neighbors are typically party walls, often original brick or masonry construction dating back a century or more. In a twin, it’s usually the single wall dividing the two halves of the building. Because the wall serves both structures — supporting the roof line, carrying some of the load, and separating the two homes for fire and sound — neither owner can treat it as entirely their own property to modify, remove, or damage without regard for the other side.

    In many older Philadelphia neighborhoods, party wall rights and responsibilities are governed by a combination of common law, city building code, and sometimes a formal recorded party wall agreement between the two properties. Not every rowhome has a written agreement on file, which is part of what makes this worth investigating rather than assuming.

    Why It Matters More at the Luxury End

    In a modest rowhome, party wall issues might come up only occasionally — a leak, a shared roofline repair. At the luxury end, where owners are more likely to be doing significant renovations, adding structural elements, extending upward, or finishing basements, party wall questions come up constantly. Excavating a basement for a wine cellar or home theater, adding a rooftop deck, or extending a rear addition can all affect the shared wall or the neighboring foundation, and construction that goes wrong can create real liability, not just an awkward conversation with the neighbor.

    Buyers evaluating a high-end rowhome renovation, whether newly completed or planned, should understand that the presence of a party wall changes what’s possible and what permitting and neighbor notification requirements apply, compared with a similar project on a detached home.

    Common Issues Buyers and Sellers Encounter

    A few situations come up repeatedly in Philadelphia rowhome and twin transactions. One is discovering, often only at the point of a renovation or an addition, that there’s no formal party wall agreement on record, leaving both sides to rely on informal understanding or city code defaults. Another is a prior owner’s renovation that altered or penetrated the party wall — running plumbing, electrical, or HVAC through or along it — without clear documentation of what was done or whether the neighbor consented. A third is settlement or movement in an old masonry party wall that shows up as cracking, which can be a purely cosmetic issue or a sign of a more significant structural concern depending on the building’s history.

    None of these issues are necessarily deal-breakers, but they’re the kind of thing that benefits from being surfaced and understood before closing rather than after, especially on a high-value purchase where a buyer may be planning renovations of their own.

    What to Check Before You Buy or List

    For buyers, it’s worth asking directly whether a recorded party wall agreement exists for the property, and if so, reviewing what it says about maintenance responsibility, cost-sharing, and any restrictions on alterations. A qualified home inspector experienced with older Philadelphia construction can flag visible signs of party wall movement or prior unpermitted work, though a structural engineer may be warranted for a property where significant work is planned or where cracking or settlement is visible.

    For sellers, gathering any documentation related to the party wall — permits for past work that touched it, any correspondence or agreements with the neighboring owner — ahead of listing can prevent last-minute questions from slowing down a deal. If a renovation is planned or already underway at the time of sale, having clear records of what was approved and by whom protects both the seller and the eventual buyer.

    Renovating Without Creating a Dispute

    Philadelphia’s building code has specific requirements around work that affects a party wall, including notification to the adjoining property owner in many cases and, depending on the scope, formal party wall agreements executed as part of the permitting process. Owners planning a significant renovation — a rear addition, a roof deck, a basement excavation — should loop in a contractor and, where the project is substantial, an attorney experienced in party wall matters early in the planning process rather than after work has started. Getting this right protects the project timeline as much as it protects the relationship with the neighbor.

    Frequently asked questions

    Do all Philadelphia rowhomes have a written party wall agreement?

    No. Many older rowhomes were built without a formal recorded agreement, and rights and responsibilities default to common law and city code in that case. It’s worth checking the property’s title history and prior permits to see what, if anything, is on record before assuming one exists.

    Can I be held responsible for damage caused by my neighbor’s renovation to a shared wall?

    Generally a party wall owner is responsible for damage they or their contractor cause, not damage caused by the neighbor’s work, but the details depend on the specific facts, any recorded agreement, and applicable law. This is a good question to raise with a real estate attorney if a dispute or damage actually occurs.

    Does having a party wall affect what renovations I can do?

    It doesn’t prevent renovation, but it does mean certain types of work — anything that touches, penetrates, or could affect the structural integrity of the shared wall — typically requires additional notice, documentation, or agreement with the neighboring owner as part of the permitting process, which can add time to a project’s planning phase.

    If you’re buying or selling a rowhome or twin in Philadelphia and want a clear-eyed read on what a shared wall means for your plans, James Kennedy can help. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Gated Communities and Private Enclaves in the Philadelphia Suburbs: A Luxury Buyer’s Guide

    Gated Communities and Private Enclaves in the Philadelphia Suburbs: A Luxury Buyer’s Guide

    A gate, a guardhouse, or a privately maintained entrance road signals something specific to a buyer: this neighborhood is governed by more than township zoning alone. Across Chester, Montgomery, Bucks, and parts of South Jersey, a number of communities operate under homeowners associations that control access, maintain shared infrastructure, and enforce architectural standards well beyond what municipal code requires. For some luxury buyers, that structure is exactly the appeal. For others, it is a constraint worth understanding fully before signing a purchase agreement.

    What “gated” actually means in practice

    Not every private or restricted-access community has a physical gate and guard staff. The term covers a spectrum: some developments have a staffed gatehouse and controlled vehicle access at all hours; others have a gate that is more symbolic, unlocked during the day and used mainly to mark the community’s private status; and many “private enclaves” have no gate at all but are legally structured as private communities with association-owned and maintained roads, shared open space, and binding architectural covenants. Before assuming a community offers a particular level of security or privacy, ask specifically how access is controlled, whether that control is staffed or purely mechanical, and what happens for deliveries, guests, and service providers.

    Governance: what an HOA in this setting typically controls

    A private community’s homeowners association generally has authority over more than a condo building’s HOA would, because it is often responsible for infrastructure a township would normally maintain elsewhere: private roads, stormwater management, shared landscaping, entry features, and sometimes amenities like a clubhouse, pool, or tennis courts. That authority typically comes with real teeth. Architectural review committees can require approval before exterior renovations, additions, fencing, or even landscaping changes, and enforcement mechanisms can include fines or liens against a property. Before buying, request the community’s governing documents — the declaration of covenants, bylaws, and any current architectural guidelines — and read them closely rather than relying on a summary from the listing agent.

    Costs beyond the mortgage

    Private community dues fund the infrastructure and amenities the association maintains, and they can vary substantially depending on what is included — a community maintaining several miles of private road and a full amenity package will typically carry higher dues than one with a simple entrance feature and minimal shared space. Buyers should also ask about the association’s reserve fund and whether any special assessments are planned or have occurred recently, the same due diligence luxury condo buyers apply to building finances. A community with underfunded reserves for road resurfacing or major infrastructure repair can mean a large, unplanned assessment down the line.

    Resale and appraisal considerations

    Private and gated communities can behave differently in resale than comparable non-gated neighborhoods. On one hand, the exclusivity, security, and consistent architectural standards that come with strong governance can support value over time. On the other, a smaller buyer pool — some buyers actively prefer not to pay HOA dues or accept architectural restrictions — can mean a longer marketing period in a soft market. Appraisers also need comparable sales within similar governed communities to support value accurately; a lack of recent comparable sales inside the same or a similar private community can complicate financing, so it is worth discussing this specifically with a lender experienced in the local market before making an offer contingent on financing.

    Questions to ask before writing an offer

    • What exactly does the HOA maintain, and is that scope clearly defined in the governing documents rather than assumed informally?
    • What are current dues, and has the association disclosed any planned or recent special assessments?
    • What does the architectural review process require for a renovation, addition, or even exterior paint color change, and how long does approval typically take?
    • Are there rental restrictions that would affect plans to lease the home short-term or long-term in the future?
    • How is access actually controlled, and does that match the level of security or privacy you are expecting to pay for?

    Who tends to be well suited to this kind of community

    Buyers who value consistency — knowing a neighbor cannot paint their house a jarring color or let landscaping go untended — often find the trade-off of HOA oversight worthwhile. The same goes for buyers prioritizing security features, shared amenities like a private clubhouse or pool, or the simple predictability of a professionally managed shared environment. Buyers who place a high value on doing whatever they want with their own property, without review, are often happier in a non-governed neighborhood, even if it means sacrificing some of the amenities and consistency a private community offers.

    Frequently asked questions

    Is a gated community automatically safer than a non-gated one?

    Not automatically. A gate can reduce casual through-traffic, but the actual security benefit depends heavily on how access is controlled and staffed, and on broader neighborhood and regional factors that apply regardless of gating. Buyers prioritizing security should ask about the specific access control system rather than assuming a gate alone provides it.

    Can I rent out a home in a gated or private community?

    It depends entirely on that community’s governing documents. Some associations allow long-term leasing with minimal restriction, others require board approval of tenants, and some prohibit short-term rentals outright. This should be confirmed in writing before assuming any future rental plan is viable.

    Do HOA fees in these communities ever decrease?

    They can be adjusted in either direction by the association’s board, typically through an annual budget process outlined in the governing documents, but well-run associations generally plan for gradual increases to keep pace with maintenance and reserve funding needs rather than sudden swings. Reviewing several years of the association’s financial statements, when available, gives a clearer picture than a single year’s dues figure.

    If you are weighing a gated or privately governed community against a traditional single-family neighborhood, James Kennedy can help you evaluate the specific HOA documents, dues, and resale dynamics for a property you’re considering. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.