Author: James Kennedy

  • Drone Photography, 3D Tours, and Video: How Philadelphia’s Luxury Listings Get Noticed

    Drone Photography, 3D Tours, and Video: How Philadelphia’s Luxury Listings Get Noticed

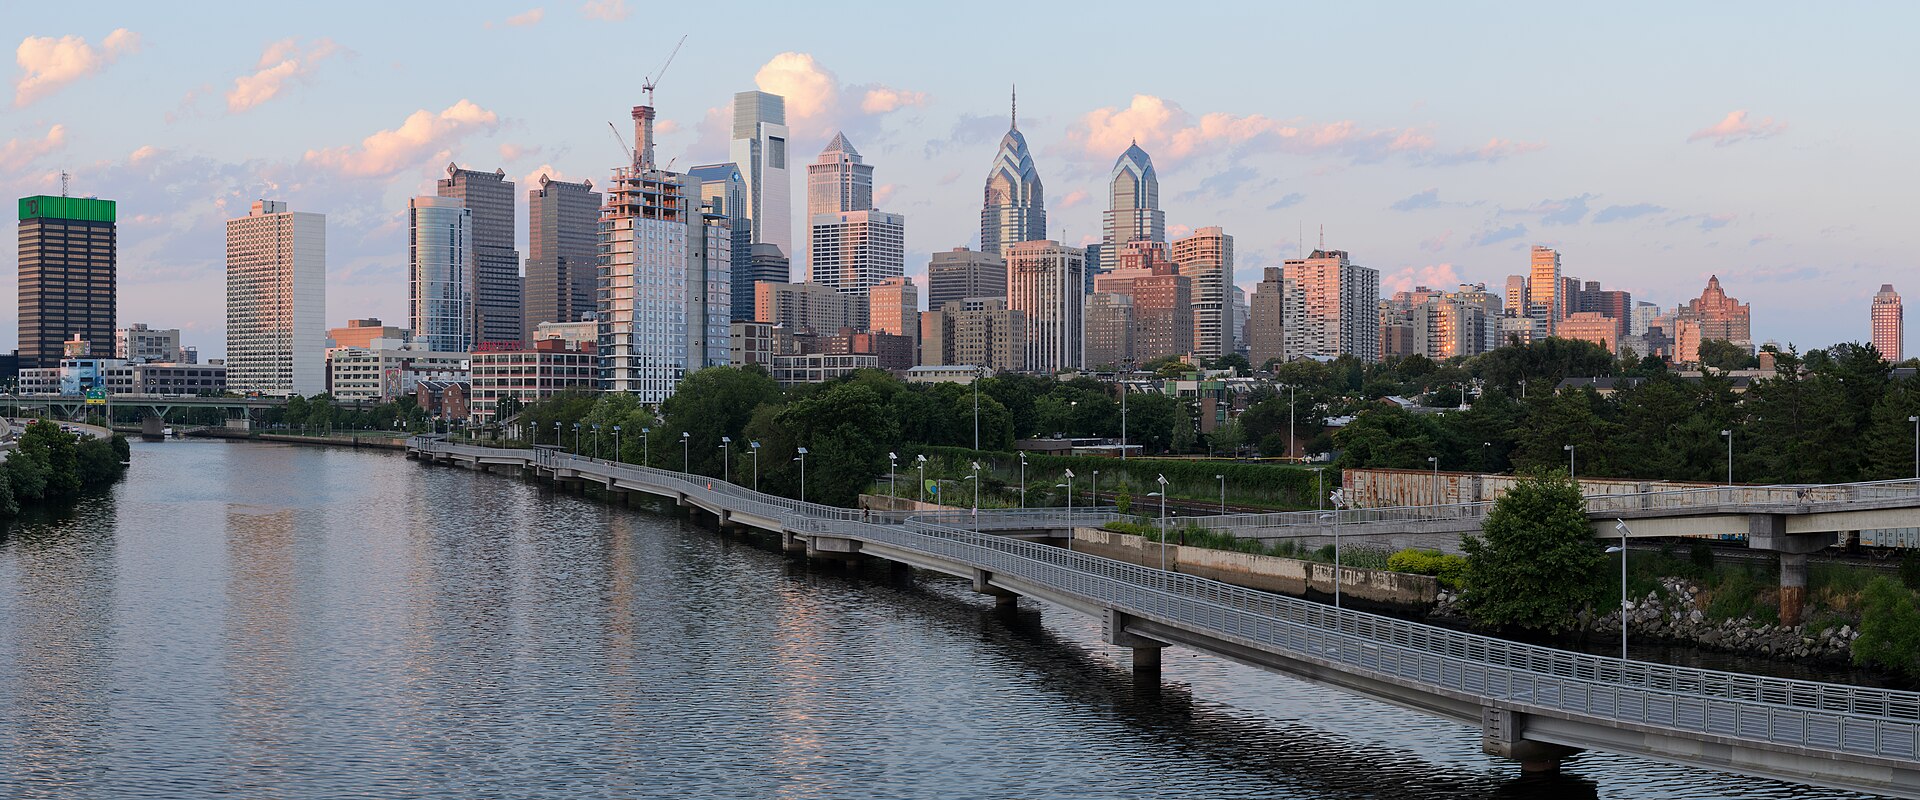
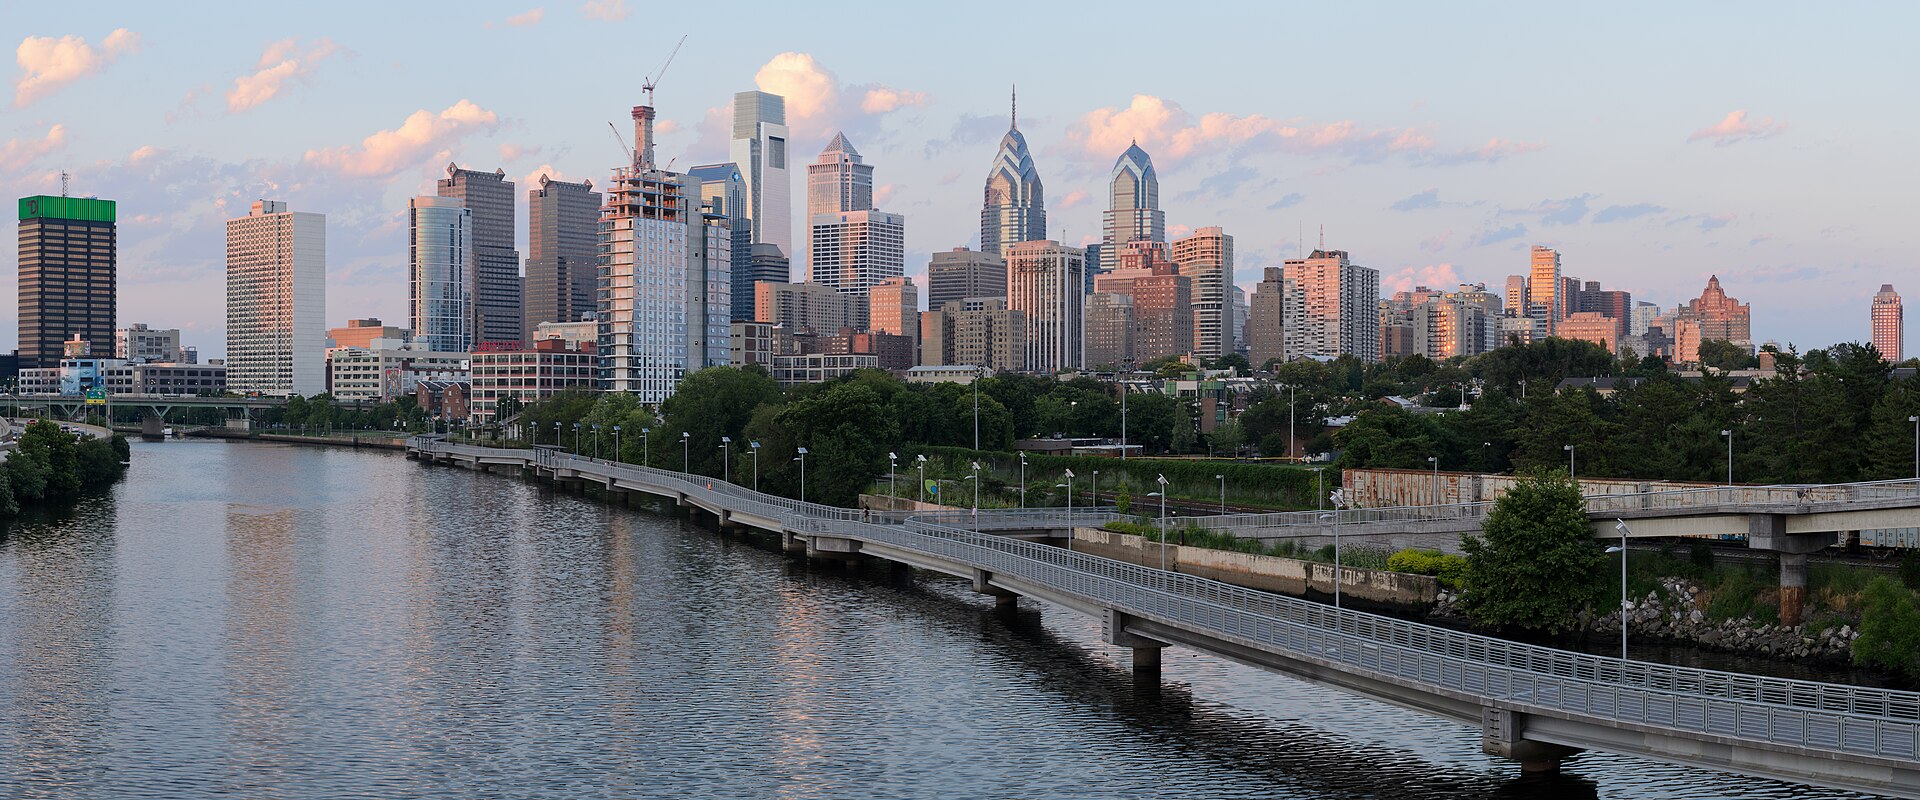
    A luxury buyer’s first real showing of a home usually happens on a screen, not in person. Before a relocating executive, an out-of-state second-home buyer, or a busy local buyer ever schedules a tour, they have almost always scrolled through a listing’s photos, watched a video, or clicked through a virtual tour to decide whether the property is worth their time. At the upper end of the Philadelphia and South Jersey market, where buyers are often comparing homes across several neighborhoods or towns before narrowing their search, the quality of that first digital impression has a direct effect on how much interest — and how strong an offer — a listing ultimately attracts.

    Why Visual Marketing Matters More at the High End

    Every home for sale gets photographed, but luxury buyers are typically more visually literate and more skeptical of anything that looks generic or rushed. A listing with flat, poorly lit photos signals — fairly or not — that the rest of the sale process may be equally unpolished. Conversely, a listing that is photographed, filmed, and presented with real craft signals that the property, and the seller, are being taken seriously. For homes in this price range, that first impression is doing real work: filtering serious buyers in, and filtering out people who were never going to be a fit.

    Drone Photography

    Aerial photography has become close to standard for luxury listings, and for good reason — it is often the only way to show a property’s lot lines, privacy, proximity to water or open space, and relationship to its neighborhood in a way that ground-level photos cannot. A waterfront home on the South Jersey coast, an estate on several acres in Chester County, or a rowhome with a rare rooftop deck in Philadelphia all benefit from an aerial perspective that gives buyers real context before they ever set foot on the property. Twilight drone shots, in particular, tend to perform well for showcasing pools, outdoor living spaces, and water views.

    3D Virtual Tours

    Interactive 3D tours let a buyer walk through a home room by room on their own schedule, measure rooms, and get a genuine sense of flow and scale — something static photos struggle to convey. For out-of-town or relocating buyers, a good 3D tour can be the difference between scheduling a flight to see a home in person and passing on it entirely. These tours also tend to keep serious buyers engaged longer with a listing, which matters for search visibility on platforms that reward time-on-listing as a signal of interest.

    Professional Video

    A well-produced video — often combining interior walkthroughs, drone footage, and a bit of neighborhood context — gives a listing a narrative that photos alone cannot. The best luxury listing videos are not simply room-by-room footage; they are edited to highlight what makes a specific property distinctive, whether that is a chef’s kitchen, a wine cellar, historic architectural details, or a rare private yard in a dense city neighborhood. Video content also performs well when shared to social media and via email to an agent’s buyer network, extending a listing’s reach well beyond the MLS.

    Print and Digital Syndication

    High-quality visual assets pay off across every channel a listing appears in — the MLS, the brokerage website, social media, email campaigns to an agent’s buyer database, and, for the right property, print placements in regional or national luxury real estate publications. The same photography and video package should be doing consistent work across all of these, which is why it is worth investing in getting it right once rather than patching together lower-quality assets for different platforms.

    What Sellers Should Ask Their Agent

    Sellers preparing to list a luxury home should ask specifically what visual marketing is included: whether drone photography and video are standard or an add-on, whether a 3D tour is provided, how the home will be staged and lit for the shoot, and where the finished content will actually be distributed. It is also worth asking to see recent examples of a similar property the agent has marketed, since quality varies significantly between photographers and videographers.

    Frequently asked questions

    Do I need drone photography if my home doesn’t have a large lot?

    Aerial photography is most valuable for larger properties, waterfront homes, and homes where the surrounding neighborhood or proximity to amenities is part of the appeal, but it can still add value for city properties by showing rooftop space, nearby parks, or a home’s position on the block. Your agent can advise whether it is worth including for your specific property.

    How far in advance should visual marketing be scheduled before listing?

    Most photography and video shoots should be scheduled once the home is fully staged and ready to show — typically a few days to a week before the listing goes live, with enough buffer to review and select the final images and video before marketing begins.

    Does a 3D virtual tour replace in-person showings?

    No. A strong virtual tour helps serious buyers pre-qualify themselves and often speeds up the process of scheduling in-person showings with genuinely interested buyers, but it does not replace the walkthrough most buyers want before making an offer on a luxury home.

    James Kennedy markets luxury listings across Philadelphia and South Jersey with professional photography, drone imagery, video, and 3D tours as part of a full marketing plan. If you are considering selling, reach James at 215-267-8479 or jameskennedy@unlockedteam.com to discuss how your home would be presented.
  • Second Homes and Tax Residency: What Philadelphia-Area Luxury Buyers Should Know About Owning in Two States

    Second Homes and Tax Residency: What Philadelphia-Area Luxury Buyers Should Know About Owning in Two States

    It is common for luxury buyers in this region to end up owning property in more than one state — a primary home in Philadelphia or the Main Line paired with a place at the Jersey Shore, or a Pennsylvania residence alongside a South Jersey property purchased for family or investment reasons. Once a household has meaningful ties to two states, questions about tax residency and domicile tend to follow. This is a genuinely complex area of state tax law, it changes over time, and the right answer depends on a household’s specific facts — so this article explains the concepts buyers should understand and the questions worth raising with a qualified accountant or tax attorney, rather than offering specific tax advice.

    Domicile vs. Residency: Two Different Questions

    Domicile generally refers to the one place a person considers their permanent home — the place they intend to return to, even after time away. Residency, by contrast, is often about where someone actually spends their time and maintains a home, and a person can be a legal resident of more than one state for tax purposes even though they can only have one domicile. States use different tests to determine both, and the distinction matters because it can affect which state taxes a household’s income, and in some cases how a household’s estate is taxed after death.

    Why This Matters for Owners of a Philadelphia Home and a Shore or Suburban Second Home

    For a household with a primary residence in Pennsylvania and a second home in New Jersey — or the reverse — the stakes usually involve state income tax exposure. A state that considers a taxpayer a resident may seek to tax all of that person’s income, not just income earned within the state, while a non-resident is typically taxed only on state-source income. For high-income households, the difference between resident and non-resident tax treatment in a second state can be significant, which is exactly why this deserves proactive planning rather than an assumption that “the house we live in most of the year” automatically settles the question.

    The General Idea Behind Day-Count Tests

    Many states, including Pennsylvania and New Jersey, use some version of a statutory residency test that looks at both the number of days spent in the state during the year and whether the taxpayer maintains a “permanent place of abode” there. A commonly referenced threshold in many states’ rules is around 183 days, though the exact rule, definitions, and exceptions vary by state and can change, so this should be treated as a general concept to discuss with a professional rather than a number to rely on directly. Simply owning a second home does not automatically make someone a statutory resident of that state — the analysis typically also depends on how much time is actually spent there.

    Evidence States Look At

    When domicile or residency is contested, states typically look well beyond day counts. Voter registration, driver’s license and vehicle registration, where a person’s primary doctor, accountant, and place of worship are located, the address used on a will or estate planning documents, where children attend school, and where a person’s most significant personal and business relationships are centered can all be considered. Households that want to establish or maintain a particular domicile should be consistent across all of these details, not just the address on a tax return.

    Property Tax Is a Separate Issue

    It is worth distinguishing this from local property tax, which is assessed by the municipality where a property sits and applies regardless of a household’s residency or domicile status. Owning a second home in New Jersey means paying New Jersey property tax on that home no matter where the household is domiciled for income tax purposes. Some jurisdictions also offer homestead exemptions or other primary-residence property tax benefits that are unrelated to state income tax residency rules and have their own separate qualification requirements.

    Building a Record Over Time

    Because residency and domicile questions can come up years after a purchase — sometimes triggered by an audit following the sale of a home or a significant change in income — it is worth keeping organized records from the start: utility bills, calendars or credit card statements that help establish time spent in each state, and copies of any state tax filings. This is far easier to assemble proactively than to reconstruct after the fact.

    Frequently asked questions

    If I buy a second home in New Jersey, does that automatically make me a New Jersey tax resident?

    Not automatically. Residency generally depends on factors like how many days are spent in the state and whether a permanent place of abode is maintained there, not simply on owning property. A tax professional can evaluate a household’s specific situation against current state rules.

    Can I be considered a resident of both Pennsylvania and New Jersey at the same time?

    It is possible for a household to have residency-related tax obligations in more than one state depending on the specific facts, which is part of why this situation benefits from professional guidance rather than assumptions.

    Does this affect the property taxes I pay on each home?

    No — local property tax is based on where each property is located and its assessed value, and applies regardless of a household’s state income tax residency or domicile status.

    James Kennedy works with buyers and sellers across Philadelphia and South Jersey who own or are considering property in more than one location, and can help connect you with qualified tax professionals as part of your purchase planning. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.

  • Lumberville and Cuttalossa, Pennsylvania: A Bucks County River Village Guide for Luxury Buyers

    Lumberville and Cuttalossa, Pennsylvania: A Bucks County River Village Guide for Luxury Buyers

    Tucked along the Delaware River in Solebury Township, Lumberville is one of Bucks County’s smallest and most quietly prestigious addresses. A cluster of stone farmhouses, a historic general store, and the pedestrian bridge to Raven Rock, New Jersey give the hamlet a sense of scale that feels closer to a New England river village than a suburb of Philadelphia. A few minutes up River Road, Cuttalossa Road winds past the creek of the same name, framed by stone walls, mature trees, and some of the region’s most photographed rural scenery. For buyers who want a serious luxury property without the density of New Hope or the formality of the Main Line, this corner of Upper Bucks County is worth a close look.

    What Makes Lumberville and Cuttalossa Distinctive

    This is a landscape shaped by the Delaware Canal and the river itself. Many of the area’s finest homes are 18th- and 19th-century stone farmhouses, sensitively expanded and updated over the decades, sited on lots that range from a manicured acre to twenty or more acres of pasture and woodland. Newer construction exists too, generally built to blend with the area’s historic character rather than stand apart from it. The towpath along the canal offers walking and cycling for miles in either direction, and the general store and the Lumberville–Raven Rock bridge give the hamlet an actual center, rather than just a collection of estates along a road.

    Because so much of the housing stock here predates modern construction standards, buyers should expect a different due-diligence process than they would in a newer development. Stone and fieldstone construction, older heating systems retrofitted over time, hand-dug wells, and septic systems on larger parcels are all common, and a qualified inspector with experience in historic rural properties is essential.

    The Real Estate Market

    Inventory in Lumberville and along Cuttalossa Road is thin by nature — there are simply not that many properties here, and well-maintained stone farmhouses with river or creek frontage do not come up often. That scarcity is part of the appeal for buyers who want privacy and a truly distinctive property, but it also means patience and a strong local search strategy matter more here than in higher-turnover markets. Homes can range from beautifully restored three- and four-bedroom farmhouses on a few acres to larger estate parcels with barns, guest cottages, or equestrian facilities.

    Flood Zones, Wells, and Septic: What to Check

    Because the area sits along the Delaware River and its tributary creeks, flood zone status is a genuine consideration for riverfront and near-river parcels, and buyers should review FEMA flood maps and ask about flood insurance costs and claims history as part of due diligence, not as an afterthought. Most properties in this area rely on private wells and septic systems rather than municipal water and sewer, so a well flow test, water quality test, and septic inspection should be built into any offer. On larger parcels, it is also worth confirming easements, right-of-way access along shared lanes, and any agricultural or conservation restrictions that may run with the land.

    Access, Commuting, and Lifestyle

    River Road (Route 32) connects Lumberville south to New Hope and north through Upper Black Eddy, and the Lumberville–Raven Rock bridge provides pedestrian access into Hunterdon County, New Jersey. A car is a necessity here — this is not a walkable town center in the way New Hope or Doylestown are — but the trade-off is privacy, acreage, and scenery that are difficult to find closer to Philadelphia. Commuters typically drive to Doylestown or Trenton for train service into Philadelphia or New York, which makes this area better suited to buyers who work remotely, keep flexible schedules, or are purchasing a full-time or weekend retreat rather than commuting daily into Center City.

    Who Tends to Buy Here

    Lumberville and the Cuttalossa corridor tend to attract buyers who already know Bucks County well — often people who have spent time in New Hope or Doylestown and want more land and more privacy without leaving the area’s historic character behind. Second-home buyers from Philadelphia and New York are common, as are buyers relocating from denser markets who want a genuine change of pace. Equestrian buyers, art collectors drawn to the area’s long history as an artists’ colony, and buyers simply looking for a serious architectural or historic property all show up here regularly.

    Frequently asked questions

    Is Lumberville considered part of New Hope?

    No. Lumberville is its own hamlet within Solebury Township, a few miles north of New Hope borough along River Road. It shares the same general Bucks County market and river geography but has a distinctly quieter, more rural character than New Hope’s walkable downtown.

    Are homes in this area on well and septic, or public utilities?

    The large majority of properties in Lumberville and along Cuttalossa Road use private wells and septic systems rather than municipal water and sewer. Buyers should budget for well and septic inspections as part of due diligence and ask sellers for maintenance and pumping records.

    How does flood risk affect riverfront properties here?

    Proximity to the Delaware River and its tributaries means flood zone designation is a real factor for some parcels, particularly those closest to the water. It affects insurance cost and availability and should be reviewed early in the search process using current FEMA flood maps, not left until just before closing.

    If you are exploring a move to Lumberville, Cuttalossa Road, or another corner of Bucks County’s river towns, James Kennedy can help you understand what is realistically available and walk the due-diligence process with you from search through settlement. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.

  • New Jersey’s Municipal Certificate of Occupancy and Smoke Detector Certification: What Luxury Sellers Need to Know Before Closing

    New Jersey’s Municipal Certificate of Occupancy and Smoke Detector Certification: What Luxury Sellers Need to Know Before Closing

    Pennsylvania buyers and sellers often assume the closing process works the same way everywhere, but New Jersey adds a step that surprises a lot of first-time sellers on that side of the river: a municipal inspection requirement that must be satisfied before or at closing in many towns. It goes by different names locally — a resale certificate of occupancy, a certificate of continued occupancy, or most commonly a smoke detector, carbon monoxide, and fire extinguisher certification — but the underlying idea is the same. The town wants to confirm basic life-safety equipment is present and functioning before ownership changes hands.

    Where this requirement comes from

    New Jersey’s Uniform Fire Code requires smoke detector, carbon monoxide detector, and portable fire extinguisher compliance at the time of a one- or two-family home’s sale, and it’s enforced at the municipal level, typically by the local fire department or fire marshal’s office. Many townships layer an additional certificate of occupancy or certificate of continued occupancy requirement on top of that, which can involve a broader inspection covering things like handrails, egress windows, electrical panels, and exterior conditions depending on the municipality’s own ordinance. Because this is set locally rather than statewide, requirements and inspection scope vary meaningfully from one South Jersey town to the next, and sellers should never assume their last sale’s process will match this one.

    What the inspection typically covers

    At minimum, expect the inspector to verify smoke detectors are present, correctly located, and functioning in required areas; that carbon monoxide detectors are installed near sleeping areas or as the local ordinance specifies; and that an approved, properly sized, and current fire extinguisher is present, usually near the kitchen. Towns with a broader certificate of occupancy requirement may also check handrails and guardrails on stairs, smoke detector interconnection in newer construction, the condition of exterior steps and walkways, and sometimes basic electrical and plumbing conditions. Luxury and historic homes with older wiring, walk-up attics converted to living space, or additions built without permits can surface issues here that a seller didn’t anticipate, so it pays to request the inspection early rather than waiting until the week of closing.

    Timing and how it fits into a transaction

    This inspection is separate from — and in addition to — a buyer’s home inspection and any township building permit closeout for prior renovation work. Sellers typically schedule the smoke detector or certificate of occupancy inspection through the local fire department or code enforcement office, often for a modest fee, and it can usually be scheduled once a firm closing date is set. Because scheduling windows can run one to several weeks depending on the town and season, waiting until the final week before closing is a common and avoidable source of delay. Any deficiencies found are generally simple and inexpensive to fix — installing or relocating a detector, buying a compliant extinguisher — but they do need to be corrected and reinspected before the certificate is issued, and that reinspection also takes time to schedule.

    How this differs from Philadelphia’s U&O process

    Philadelphia has its own related but distinct requirement, the Certificate of Rental Suitability for rental transfers and a Use and Occupancy process tied to certain sales and zoning changes, which is not identical to New Jersey’s fire code inspection. Sellers who have sold property on one side of the river and are now selling on the other should not assume the process carries over — South Jersey’s smoke detector and certificate of occupancy requirements are municipal and fire-code driven, while Philadelphia’s system is administered through Licenses and Inspections and tied to zoning and rental use. Both are manageable with early planning, but they are genuinely different processes.

    What this means for high-value, historic, and renovated homes specifically

    Luxury sellers in South Jersey’s older towns — think grand Victorians in Haddonfield, farmhouses in the Burlington County countryside, or riverfront homes in towns like Riverton and Cinnaminson — should pay particular attention to this requirement, because these homes are more likely to have additions, finished third floors, or converted spaces built over many decades, sometimes without a permit on file. A finished attic bedroom without a properly located smoke detector, or a converted carriage house without a required extinguisher, is a common and easily fixed finding, but only if it’s identified with enough lead time. Sellers who have completed recent renovations should also confirm that any required building permits were properly closed out with the township, since an open or unclosed permit can sometimes surface during this process and create a separate, more time-consuming issue to resolve before closing.

    Why sellers should plan ahead

    For a luxury listing, an unexpected compliance delay in the final days before closing is an unnecessary source of stress for everyone involved, including the buyer’s lender if a specific closing date is tied to a rate lock. Building the municipal inspection into the listing preparation timeline, alongside any pre-listing home inspection, is the simplest way to avoid a last-minute scramble.

    Frequently asked questions

    Does every New Jersey town require this before a home can be sold?

    Requirements vary by municipality, since the underlying fire code mandate is statewide but enforcement and any additional certificate of occupancy requirements are set locally. Sellers should confirm the specific requirement, fee, and scheduling process with their town’s fire department or code enforcement office as soon as a home goes under contract.

    Who typically pays for the inspection and any required repairs?

    The seller is generally responsible for scheduling and passing this inspection, along with the cost of the inspection fee and any corrective work such as detectors or an extinguisher, since it’s a condition of legally transferring occupancy rather than a negotiated item between buyer and seller.

    Can this inspection delay a closing?

    It can, particularly if it’s scheduled late or if the home requires more than a minor fix, such as bringing an older or renovated area up to current detector placement standards. Scheduling the inspection as soon as a closing date is set, rather than waiting until the final week, is the most reliable way to prevent delay.

    If you’re preparing to sell in South Jersey and want a clear timeline for every pre-closing requirement, James Kennedy can walk you through what your specific municipality requires. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.

  • Strathmere, New Jersey: A Luxury Buyer’s Guide to the Jersey Shore’s Quietest Barrier Island Village

    Strathmere, New Jersey: A Luxury Buyer’s Guide to the Jersey Shore’s Quietest Barrier Island Village

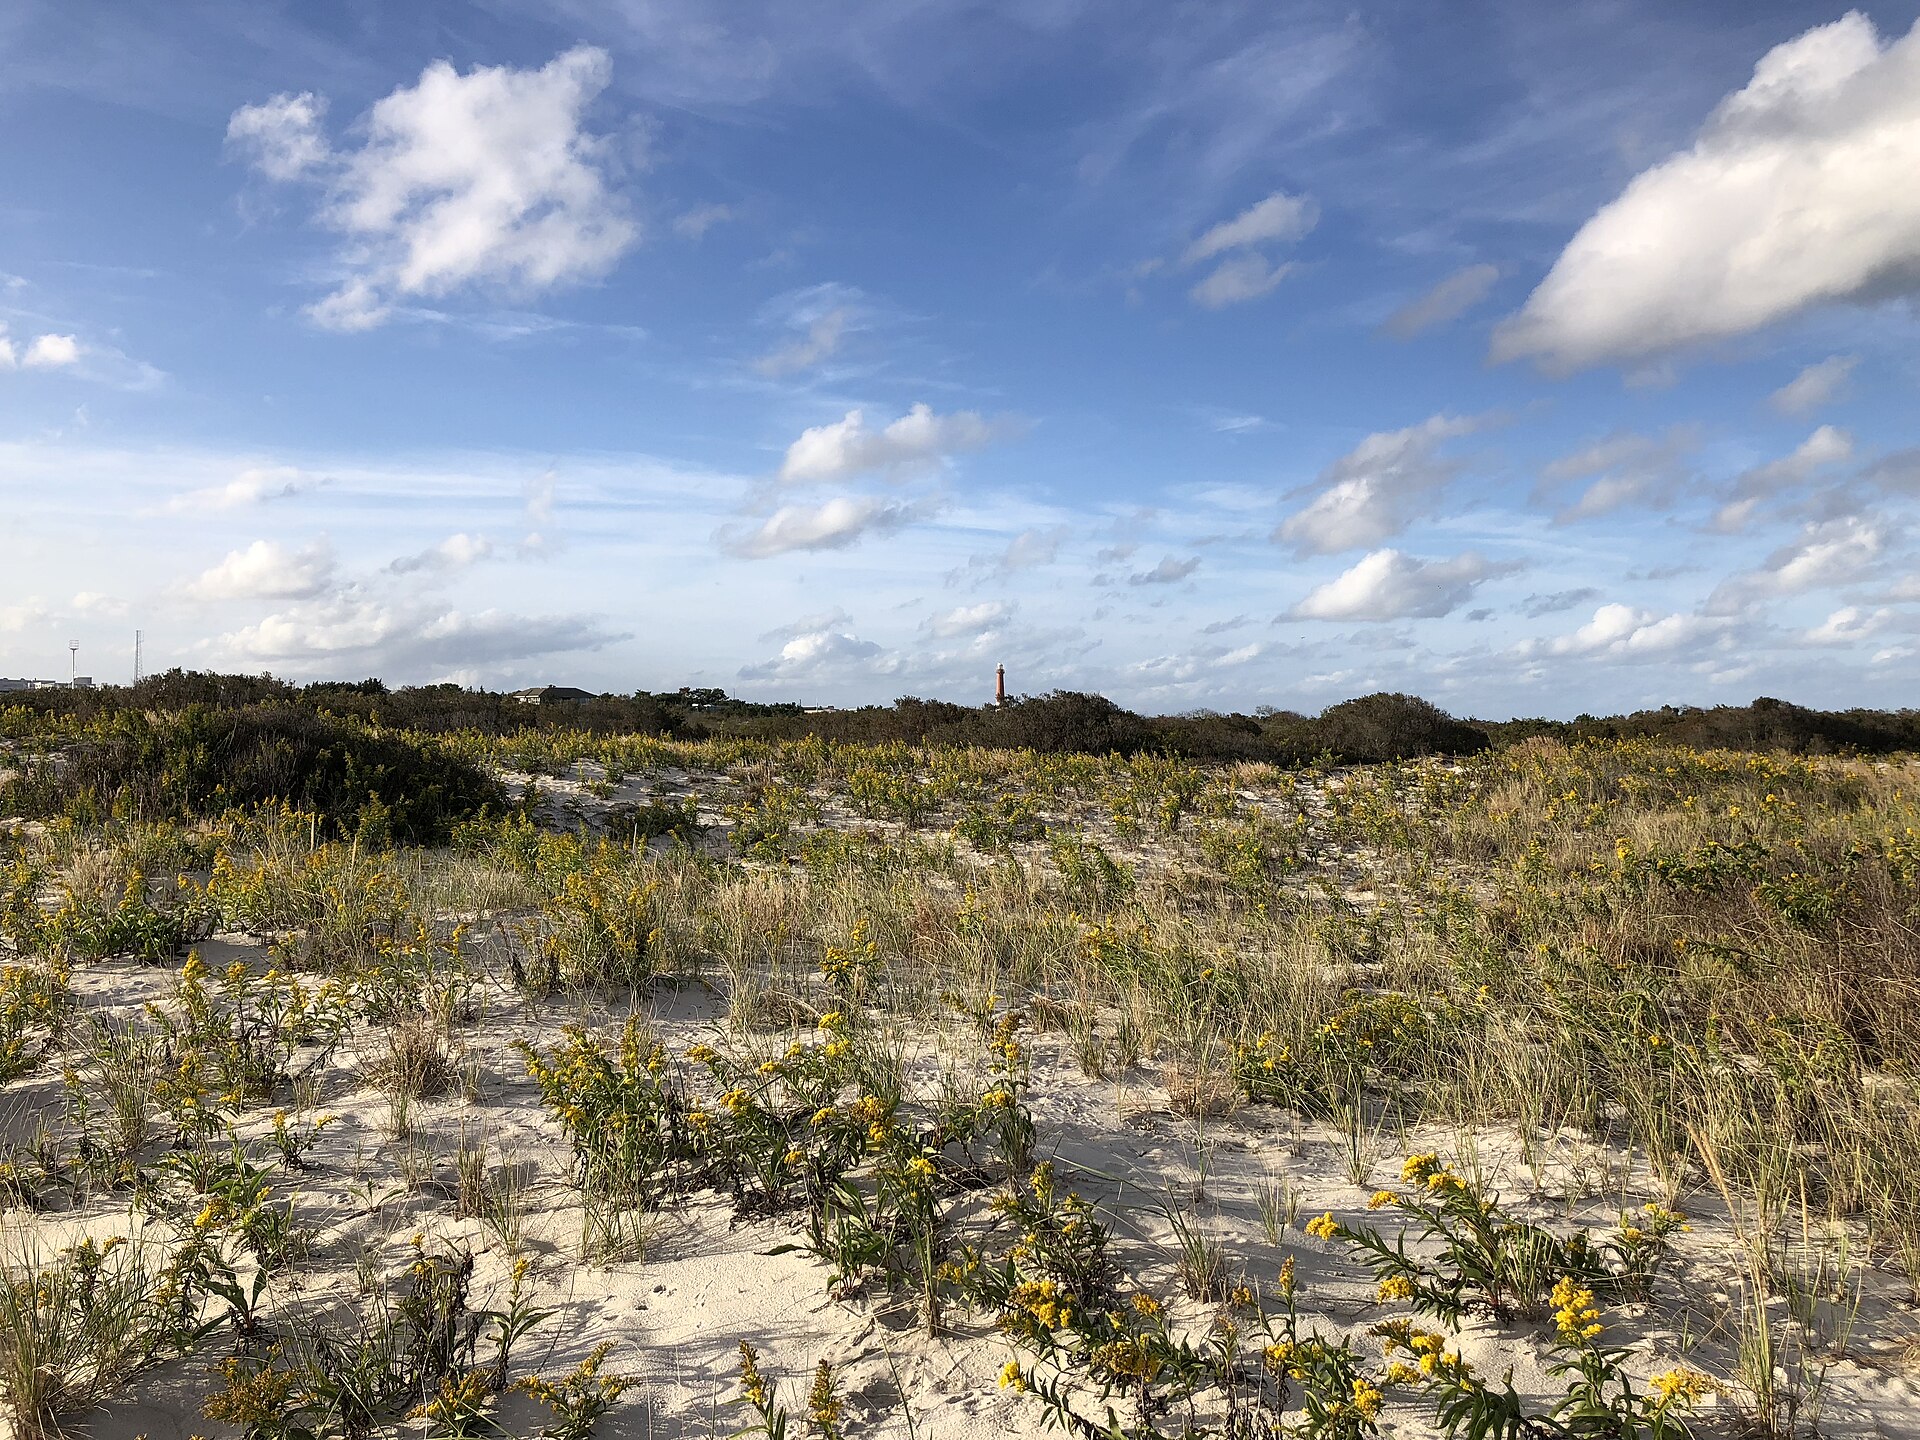
    Drive south from Ocean City on Landis Avenue and the commercial strip falls away almost immediately. What’s left is Strathmere: a narrow, largely residential stretch of Upper Township that occupies its own quiet pocket of barrier island between Ocean City and Sea Isle City. There’s no boardwalk, no arcade, and barely any retail. For a certain kind of shore buyer, that absence is the entire point.

    A short history of a deliberately small place

    Strathmere was originally known as Whale Beach, a name that still appears on some older deeds and local references, before being renamed in the early 20th century as shore development expanded along the New Jersey coast. Unlike its larger neighbors, Strathmere never built out a commercial downtown or a boardwalk entertainment district, and that pattern has held for more than a century. Its neighbor to the north, Corson’s Inlet, was never bridged for development the way many other inlets were, which permanently fixed the village’s northern edge as open space rather than a growth corridor. The result is a shore community that looks today much as it has for decades — a deliberate contrast to the continuous redevelopment cycle seen in larger shore towns.

    A village built around restraint

    Strathmere is part of Upper Township rather than its own incorporated municipality, and that governance structure has helped keep commercial development minimal by design. The village consists mostly of single-family homes on the ocean side and bay side of a narrow barrier spit, with Corson’s Inlet State Park forming a natural, permanently undeveloped buffer at its northern end. That state park boundary is significant for value: it guarantees that Strathmere’s northern flank can never be built out, which is a rare and durable form of protected view and privacy on the New Jersey coast.

    Oceanfront, bayfront, and everything between

    Because the village is narrow, most homes are within a few blocks of either the ocean or Ludlam Bay, and a meaningful number of properties have direct water frontage on one side or the other. Bayfront homes tend to draw boating families who want dock access and calmer water for kids, while oceanfront and ocean-block homes command the clearest view premiums. Given the barrier island setting, flood zone designation and elevation requirements are central to any purchase here — older homes are often being raised or have already been raised to meet current base flood elevation standards, and that history (or its absence) belongs in every buyer’s due diligence.

    Lifestyle and what’s nearby

    Strathmere’s appeal is precisely that it isn’t a destination in the boardwalk sense. Residents walk or bike into Ocean City or Sea Isle City for restaurants, groceries, and nightlife, and return to Strathmere for quiet. Corson’s Inlet State Park offers protected beach, dunes, and birdwatching immediately adjacent to the village, and the absence of a commercial strip means summer traffic and crowds are noticeably lighter than in neighboring towns. Buyers who want an active boardwalk scene at their doorstep should look to Ocean City; buyers who want that scene a short trip away, with true quiet at home, tend to gravitate to Strathmere.

    Rental and investment considerations

    Strathmere sees consistent seasonal rental demand from families specifically seeking a quieter alternative to the bigger shore towns, and its limited housing stock keeps supply naturally constrained. Buyers considering an income component should factor in Upper Township’s specific rules on short-term rentals, along with standard shore-market considerations like flood insurance costs, which can be meaningfully higher for older, unelevated construction. As with any shore purchase, current insurance quotes should be obtained before finalizing an offer rather than estimated after the fact.

    What to watch for as a buyer

    Because Strathmere is narrow and low-lying, elevation, flood zone, and drainage due diligence matter more here than in many mainland South Jersey towns. A qualified home inspector with barrier-island experience, plus a review of FEMA flood maps and any existing elevation certificate, should be standard parts of due diligence. Septic versus sewer service, and the age of any bulkhead on bayfront lots, are also worth confirming early, since replacement costs for either can be substantial.

    Comparing Strathmere to its shore neighbors

    Buyers cross-shopping the barrier islands south of Atlantic City often compare Strathmere to Sea Isle City’s quieter blocks or to the more residential ends of Ocean City. The distinction that tends to matter most is governance and scale: Sea Isle City and Ocean City are full municipalities with their own boardwalks, business districts, and year-round municipal services, while Strathmere remains a small, unincorporated residential pocket within Upper Township with essentially no commercial development of its own. That means fewer amenities within Strathmere itself, but also a level of quiet and low turnover that’s difficult to find in towns built around tourism. Buyers who have loved a family summer in a bigger shore town but found the in-season crowds wearing often discover Strathmere is the version of that same stretch of coast they were actually looking for.

    Frequently asked questions

    Is Strathmere its own town?

    No. Strathmere is an unincorporated community within Upper Township, Cape May County. It has no separate municipal government, which is part of why it has stayed comparatively undeveloped compared to incorporated shore boroughs nearby.

    How does Strathmere compare to Ocean City or Sea Isle City for a buyer?

    Strathmere offers a quieter, more residential setting with no commercial strip of its own, bordered by Corson’s Inlet State Park to the north, while Ocean City and Sea Isle City offer boardwalks, retail, and denser year-round infrastructure. Many buyers use Strathmere as a base and simply drive or bike into the neighboring towns for amenities.

    What should a buyer check regarding flood risk?

    Every barrier-island purchase should include a review of the property’s FEMA flood zone designation, any existing elevation certificate, and current flood insurance quotes, since these can vary significantly by block and by whether a home has already been elevated to modern standards.

    For a private tour of available Strathmere and surrounding shore properties, contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com.

  • Strafford, Pennsylvania: A Main Line Town Guide for Luxury Home Buyers

    Strafford, Pennsylvania: A Main Line Town Guide for Luxury Home Buyers

    Ask most people to name a Main Line town and you’ll hear Bryn Mawr, Wayne, or Villanova before you hear Strafford. That relative obscurity is exactly what makes it interesting. Strafford is a small unincorporated village straddling Tredyffrin and Easttown townships in Chester County, built around one of the original Pennsylvania Railroad stops on the historic “Main Line of Public Works” corridor. It has never tried to be a downtown, and it shows: there’s no commercial strip to speak of, just winding roads, mature trees, and houses set back on generous lots. For buyers who want Main Line prestige and train access without the density of Wayne or the price ceiling of Villanova, Strafford deserves a look.

    A brief history worth knowing

    Strafford takes its name from the Pennsylvania Railroad’s practice of naming stations after English and Welsh places, part of a branding effort in the late 19th century meant to lend the new commuter suburbs an air of Old World pedigree. The Strafford train station itself, a handsome late Victorian structure, is a recognized local landmark and one of the more architecturally distinctive stops on the line. That railroad heritage shaped everything that followed: large estates were subdivided gradually over decades rather than all at once, which is why Strafford’s lot sizes and architectural styles are so much more varied than in towns that were platted and built out in a single development wave.

    What the housing stock looks like

    Strafford’s homes span a wide range of eras and styles, which is part of its appeal. You’ll find stone farmhouses and carriage houses dating to the 19th century sitting near shingle-style and Colonial Revival homes from the early 1900s, along with a meaningful supply of mid-century and newer construction built on subdivided estate parcels. Lot sizes tend to be larger than in the denser Main Line boroughs, and many properties back up to wooded buffers or creek frontage along Gulph Creek and its tributaries. Because Strafford was never platted as a formal town grid, street patterns are irregular and lots vary widely in shape and privacy, which rewards buyers who walk properties in person rather than judging purely from listing photos.

    Access and commuting

    The Strafford train station sits on SEPTA’s Paoli/Thorndale Regional Rail Line, offering a direct, relatively short ride into Suburban Station and Center City Philadelphia. For buyers who work downtown but want a quieter home base, that station access is a genuine differentiator over towns further out on the line. Strafford is also close to the Route 30 (Lancaster Avenue) corridor and sits a short drive from the King of Prussia interchange on the Pennsylvania Turnpike, which matters for buyers who split time between the city, the airport, and points further west.

    Schools and community character

    Strafford is served primarily by the Tredyffrin/Easttown School District, one of the top-performing public districts in the state and a significant draw for families relocating specifically for schools. The area also sits within easy reach of a cluster of well-regarded private and independent schools common throughout the Main Line. Community life here is understated by design — there’s no downtown business district, so residents tend to socialize through the schools, local clubs, and nearby Wayne or Devon rather than a Strafford-specific commercial core. Buyers who want walkable retail and restaurants at their doorstep should look instead toward Wayne or Ardmore; buyers who want quiet and privacy with those towns a short drive away often find Strafford the better fit.

    What tends to drive value

    In Strafford, three things consistently matter to resale value: proximity to the train station, lot privacy (tree cover, setback from the road, lack of through-traffic), and school district placement, since parts of the broader Strafford area can fall into different district boundaries depending on the exact parcel. Renovated historic stone homes with updated mechanical systems tend to command a premium over homes that look the part but haven’t been modernized underneath. Buyers considering a historic property here should budget time and money for a careful inspection of roofing, foundation, and systems — older stone construction can hide expensive surprises behind a beautiful facade.

    Practical considerations for a purchase

    Because Strafford spans two townships, buyers should confirm early in the process which township a specific parcel falls in, since Tredyffrin and Easttown each set their own zoning, permitting, and property tax rates. Septic and well service is less common here than in some outer Chester County towns, but buyers looking at older or larger estate-style parcels should still confirm public water and sewer availability rather than assume it. Wooded lots and creek-adjacent parcels are also worth checking for flood zone status and tree-related insurance considerations, since mature tree cover is part of Strafford’s appeal but can also mean higher maintenance costs after storms.

    Who Strafford suits

    Strafford tends to appeal to buyers who already know and love the Main Line but want more land and less visibility than Wayne, Villanova, or Bryn Mawr offer at a comparable price point. It’s a strong fit for train commuters who value privacy over walkability, and for buyers drawn to historic stone architecture who are willing to take on some renovation. It’s a less natural fit for buyers who want restaurants, boutiques, and nightlife within walking distance — that experience is a short drive away in Wayne, not a feature of Strafford itself.

    Frequently asked questions

    Is Strafford its own municipality?

    No. Strafford is an unincorporated village that spans parts of Tredyffrin and Easttown townships in Chester County. There’s no separate Strafford borough government, which means zoning, permitting, and property taxes are handled at the township level depending on exactly where a property sits.

    How does Strafford compare in price to Wayne or Villanova?

    Pricing varies significantly by lot, age, and condition, and current figures shift with the market, so it’s best to review active and recently sold comparables rather than rely on general reputation. Generally speaking, Strafford’s lack of a commercial core and lower profile can make comparable land and square footage more attainable than in Wayne’s downtown-adjacent blocks, though truly special historic properties command their own premium regardless of location.

    Which school district serves Strafford?

    Most of Strafford falls within the Tredyffrin/Easttown School District, though buyers should always confirm the exact district and elementary feeder pattern for a specific address before making an offer, since boundaries can be granular in unincorporated areas.

    If you’re weighing Strafford against other Main Line towns, James Kennedy can walk you through current inventory, recent comparable sales, and the tradeoffs between privacy and walkability across the corridor. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.

  • New Jersey’s “Exit Tax”: What Luxury Sellers Moving Out of State Should Know

    New Jersey’s “Exit Tax”: What Luxury Sellers Moving Out of State Should Know

    Sellers who are leaving New Jersey often hear about the state’s “exit tax” and assume it is an extra tax charged specifically for moving away. It is not. What is commonly called the exit tax is actually an estimated tax withholding requirement, collected at the closing table, that applies to certain home sellers who will no longer be New Jersey residents after the sale. For a South Jersey seller relocating to Pennsylvania, another state, or overseas, understanding how this withholding actually works — and how to recover any amount that turns out to be more than you owe — is worth doing well before your closing date.

    What the Exit Tax Actually Is

    New Jersey requires an estimated payment toward state income tax on the gain from a real estate sale to be collected at closing when the seller is a nonresident of New Jersey at the time of sale, or will become one as part of the move connected to that sale. This is not a new or additional tax on top of your regular income tax liability. It is a prepayment, collected up front by the closing agent and remitted to the state, that is later reconciled against your actual New Jersey tax return for the year of the sale. In practice, this means money is withheld at the closing table that you may or may not ultimately owe, depending on your actual taxable gain.

    How the Withholding Is Calculated

    The withheld amount is generally based on a state-set formula tied to either the total sale price or the calculated gain on the sale, with the closing agent applying whichever method the relevant paperwork specifies. Because the rules and rates involved can change and because the calculation depends on details specific to your transaction — your basis in the property, any exemptions that may apply, and the structure of the sale — this is an area where a real number should come from your accountant or the closing attorney handling your specific transaction, not from a general guide. What is consistent is the mechanism: money is withheld at closing, not assessed separately afterward.

    Who It Applies To — and Who May Be Exempt

    The withholding requirement is generally aimed at sellers who are moving their primary residence out of New Jersey, along with sellers of investment or second homes who are already nonresidents. Certain circumstances can exempt a seller from the withholding at closing, including some transactions involving a continuing New Jersey resident, or sales that qualify under specific state exemption categories. Because eligibility depends on your residency status, how the property was used, and documentation filed as part of the closing, this is a determination that should be made in consultation with a New Jersey real estate attorney or accountant well before your closing date, not discovered at the settlement table.

    Getting the Withholding Back

    Because the amount collected at closing is an estimate, not a final tax bill, sellers who had more withheld than they actually owe are entitled to recover the difference by filing a New Jersey nonresident income tax return for the year of the sale. This is a step that is easy to overlook once you have relocated out of state, but it is often where a meaningful amount of money gets left on the table. If your actual capital gain on the sale, after accounting for your basis and any applicable exclusions, is lower than the amount the withholding formula assumed, filing that return is how you get the excess back.

    How This Differs from the Mansion Tax and Capital Gains Tax

    It is worth separating this withholding requirement from two other costs New Jersey sellers sometimes confuse it with. New Jersey’s mansion tax and realty transfer fee are separate charges tied to the sale price of higher-value properties and apply regardless of where the seller is moving. Federal and state capital gains tax is your actual tax liability on the profit from the sale, which the exit tax withholding is simply an advance payment toward, not a substitute for. A seller can be subject to all three at once — the transfer fee, capital gains liability, and exit tax withholding — and each is calculated and handled differently, which is exactly why working with an accountant familiar with New Jersey real estate transactions matters for a high-value sale.

    Planning Ahead as a Seller

    The most useful thing a relocating seller can do is loop in an accountant early, ideally before listing, rather than encountering this requirement for the first time at the closing table. Understanding roughly what will be withheld helps with cash-flow planning around the move itself, and knowing in advance whether you are likely to be owed a refund helps you plan to file the necessary return promptly the following tax season rather than losing track of it once you have settled into a new state.

    Frequently asked questions

    Is the exit tax really an extra tax on top of what I already owe?

    No. It is a withholding collected at closing as a prepayment toward your New Jersey income tax liability on the sale. If your actual tax owed is less than what was withheld, you file a return to get the difference refunded.

    Does the exit tax apply if I am moving from South Jersey to Philadelphia?

    It can apply any time a seller is leaving New Jersey residency as part of the sale, regardless of whether the new home is across the country or just across the river in Pennsylvania. Your specific situation should be reviewed with an accountant or closing attorney.

    Who actually collects this money?

    The withholding is collected by the closing agent as part of the settlement and remitted to the State of New Jersey, similar to how other closing costs and prorated items are handled at settlement.

    If you are planning to sell a home in South Jersey and relocate, James Kennedy can help you coordinate the timeline with your accountant and closing attorney so there are no surprises at the settlement table. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.

  • Bridge Loans and Home Equity Lines: Financing a Purchase Before You Sell in Philadelphia & South Jersey

    Bridge Loans and Home Equity Lines: Financing a Purchase Before You Sell in Philadelphia & South Jersey

    One of the most common binds a move-up buyer runs into is timing: the home you want to buy is available now, but most of your net worth is tied up in the home you have not yet sold. Selling first can mean losing the new home to another buyer, or scrambling to find temporary housing between closings. Buying first, without a plan, can mean carrying two mortgages at once. For luxury buyers in Philadelphia and South Jersey, a few established financing tools exist specifically to solve this problem — and understanding how they differ matters before you commit to one.

    Why Timing Becomes a Problem for Luxury Buyers

    At the higher end of the market, homes often move on a different schedule than the broader market, and inventory in the most desirable neighborhoods and towns can be genuinely scarce. When the right property appears, a buyer who has to wait for their current home to close before making an offer risks losing it. At the same time, most buyers do not want to carry two full mortgage payments indefinitely, and few want to make an offer contingent on their own home’s sale, since a contingent offer is often less competitive in a multiple-offer situation. Bridge financing and home equity borrowing exist to close that gap.

    How a Bridge Loan Works

    A bridge loan is a short-term loan secured against the equity in your current home, used to fund the down payment and sometimes the full purchase of the new home before the old one sells. Bridge loans are typically structured to be repaid quickly, often within six to twelve months, out of the proceeds when the current home sells. Because they are short-term and secured by real estate you already own, underwriting for bridge loans tends to focus heavily on the equity position in the departing home and a credible plan and timeline for selling it. Interest rates and fees on bridge loans are generally higher than on a standard mortgage, which is the trade-off for the flexibility they provide. Not every lender offers bridge loans, and terms vary considerably, so this is a product worth shopping specifically rather than assuming your everyday mortgage lender provides it.

    How a HELOC or Home Equity Loan Works

    A home equity line of credit, or a home equity loan, is a more widely available alternative that draws on the equity in your current home without necessarily requiring it to be sold on a fixed timeline. A HELOC in particular gives you a revolving credit line you can draw against for a down payment or other purchase costs, and it can be opened well in advance of when you actually need the funds — which is one of its advantages over a bridge loan. The trade-off is that a HELOC adds an additional lien and monthly payment obligation on the current home while you still own it, and approval depends on your income and debt profile supporting that added payment, not just the equity itself. For buyers with substantial equity and strong income, opening a HELOC ahead of a search can be a useful piece of financial preparation even before a specific new home is identified.

    Other Options Worth Discussing With Your Lender

    • Portfolio and asset-based lending: Some private and portfolio lenders will underwrite a purchase primarily against liquid assets or overall net worth rather than requiring the current home to be sold or a HELOC to be in place.
    • Contingent offers with a rent-back: In some markets, sellers will accept an offer contingent on the buyer’s home selling if it is paired with flexible terms, though this is highly dependent on how competitive the specific listing is.
    • Cross-collateralization: Certain lenders will allow the new purchase to be secured partly by the departing home directly, effectively combining features of a bridge loan with the primary mortgage.

    Comparing the Trade-offs

    Bridge loans tend to suit buyers who need funds for a specific, imminent purchase and have a clear, realistic timeline for selling their current home. HELOCs tend to suit buyers who want flexibility, may be searching for a while before finding the right property, and are comfortable carrying an additional payment in the interim. Both require a lender’s honest assessment of your current home’s likely sale price and timeline, so getting a realistic valuation early — not just an optimistic one — is an important first step regardless of which route you take.

    Questions to Ask a Lender Before Committing

    Before choosing either path, it is worth asking a lender directly how the product affects your debt-to-income ratio for qualifying on the new mortgage, what happens if your current home takes longer to sell than expected, what the total cost is in interest and fees, and whether the lender has experience with this structure specifically for move-up buyers in the local luxury market. A mortgage broker or lender who regularly works with high-net-worth buyers in Philadelphia and South Jersey will generally have more flexibility here than a lender focused primarily on conventional, owner-occupied purchases.

    Frequently asked questions

    Is a bridge loan the same as a home equity loan?

    No. A bridge loan is a short-term financing product built specifically to cover the gap between buying a new home and selling the current one, while a home equity loan or HELOC is a longer-standing product that draws on home equity and can be used for a purchase or for other purposes, without necessarily being tied to a sale timeline.

    Do I need to have my current home listed before I can get a bridge loan?

    Requirements vary by lender. Some want the home actively listed or under contract, while others will lend based on equity and a credible plan to list soon. This is a key point to clarify early with any lender you are considering.

    Which option is less expensive?

    It depends on how long you need the financing and your specific equity and income situation. A HELOC often carries a lower rate than a bridge loan but adds an ongoing payment obligation, while a bridge loan is typically more expensive per dollar borrowed but is structured to be short-lived. A lender can model the actual cost for your situation more precisely than a general comparison can.

    If you are weighing how to finance a move-up purchase in Philadelphia or South Jersey before your current home sells, James Kennedy can connect you with lenders experienced in bridge and equity-based financing and help sequence the sale and purchase to minimize risk. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.

  • Surf City and Ship Bottom, New Jersey: A Luxury Buyer’s Guide to Long Beach Island’s Classic Beach Towns

    Surf City and Ship Bottom, New Jersey: A Luxury Buyer’s Guide to Long Beach Island’s Classic Beach Towns

    Long Beach Island stretches eighteen miles along the New Jersey coast, and its character changes block by block as you move north and south. Near the middle of the island sit Surf City and Ship Bottom, two small, walkable communities that have long appealed to buyers who want classic LBI living without the longer drive to the island’s northern tip or the quieter isolation of its southern end. For luxury buyers evaluating the Jersey Shore, these two towns are worth a closer look precisely because they combine convenience, character, and a scale that has stayed genuinely residential.

    Where Surf City and Ship Bottom Sit on the Island

    Surf City and Ship Bottom sit almost directly across from the Manahawkin Bay Bridge, which is the primary vehicle entrance to Long Beach Island from the mainland. That location matters more than it might seem. A home in this stretch of the island puts a buyer close to the bridge, close to the island’s main commercial strip along Long Beach Boulevard, and within a short walk or bike ride of the beach in almost any direction. Buyers who split time between a primary residence and a shore home often weigh drive time heavily, and this central location shortens the trip in from Route 72 and the Garden State Parkway compared with towns further up or down the island.

    The Character of These Two Towns

    Surf City

    Surf City is one of the older municipalities on the island, and its housing stock reflects that history: a mix of classic shore cottages, updated mid-century homes, and newer or substantially renovated construction on both the oceanside and bayside blocks. The town has kept a low-key, residential feel even as home values have risen, with a compact business district rather than a dense commercial strip. For a buyer who wants a walkable shore town without a resort atmosphere, Surf City tends to fit.

    Ship Bottom

    Ship Bottom, just south of Surf City, functions as something of a hub for this part of the island, with more of the restaurants, shops, and services that make a shore town livable outside of peak summer weekends. Its housing stock spans a similarly wide range, from older bungalows on interior streets to larger, elevated new construction closer to the water. Because it sits at the base of the Boulevard’s northern stretch and the bridge, Ship Bottom often draws buyers who want convenience as much as they want beach access.

    What Luxury Buyers Are Evaluating

    At the higher end of this market, the meaningful distinctions are usually about water proximity, elevation, and lot orientation rather than town boundary lines. A few factors luxury buyers weigh most heavily:

    • Oceanfront and oceanblock position: Direct ocean exposure commands a premium, and the difference between oceanfront, oceanblock, and a few streets back can be substantial even within the same town.
    • Bay and lagoon access: Bayfront and lagoon-front homes appeal to buyers who boat, and dock or slip availability is often a deciding factor for these buyers.
    • Elevation and construction type: Homes built or substantially rebuilt after the most recent wave of flood-elevation updates tend to sit higher off grade, which affects both insurance costs and resale appeal.
    • Lot size and setbacks: LBI lots are famously compact by suburban standards, so buyers accustomed to larger parcels should recalibrate expectations and focus on livability — outdoor space, pool placement, parking — rather than acreage.

    Flood Zones, Elevation, and Insurance Considerations

    Nearly every property on Long Beach Island sits within a mapped flood zone, and elevation requirements have shaped a lot of the new construction and major renovation work on the island over the past couple of decades. Before making an offer, a serious buyer should confirm a home’s flood zone designation and base flood elevation, review its elevation certificate if one exists, and get a firm sense of projected flood insurance costs from an agent who works regularly with barrier island properties. These costs can vary meaningfully between two homes on the same street depending on how and when each was built, and they belong in the total cost of ownership alongside the purchase price.

    Rental Potential and Investment Considerations

    A meaningful share of LBI buyers, including buyers at the luxury end, plan to rent the home out for at least part of the season. Surf City and Ship Bottom’s central location and walkability tend to support strong seasonal rental demand, but every buyer weighing rental income should confirm current municipal rules on rental registration, minimum stay lengths, and any local ordinances that could affect how the property can be used before counting on that income as part of the purchase decision.

    Getting to and From the Island

    Access is one of LBI’s defining practical realities. The island connects to the mainland by a single bridge corridor, which means travel times can lengthen considerably on summer weekends and ahead of storms. Buyers who plan to use a shore home as a regular weekend or seasonal residence should factor typical shoulder-season and peak-season travel times into their expectations, particularly if they are commuting back to Philadelphia or South Jersey during the week.

    Frequently asked questions

    Are Surf City and Ship Bottom oceanfront towns?

    Both towns include oceanfront blocks along with oceanblock, bayfront, and interior streets. Because the island is narrow, most homes are within a short walk of the beach regardless of exact location, but direct oceanfront property commands a distinct premium and comes with its own maintenance and insurance considerations.

    How does buying in Surf City or Ship Bottom compare with towns further up the island, like Loveladies or Harvey Cedars?

    Northern LBI towns tend to be quieter, more spread out, and further from the bridge and commercial services, while Surf City and Ship Bottom offer more walkability and shorter travel times to and from the mainland. Price points can overlap significantly; the choice often comes down to lifestyle preference rather than budget alone.

    Do these towns allow short-term rentals?

    Rental rules are set at the municipal level and can change, so any buyer counting on rental income should verify current registration requirements, minimum stay rules, and any recent ordinance changes directly with the relevant township before relying on those numbers.

    If you are considering a shore purchase on Long Beach Island or anywhere along the South Jersey coast, James Kennedy can walk you through current inventory, flood zone and insurance considerations, and what a given property is likely to command in the rental market. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com to start the conversation.

  • Backup Offers and Multiple-Offer Strategy: How Luxury Sellers Maximize Leverage

    Backup Offers and Multiple-Offer Strategy: How Luxury Sellers Maximize Leverage

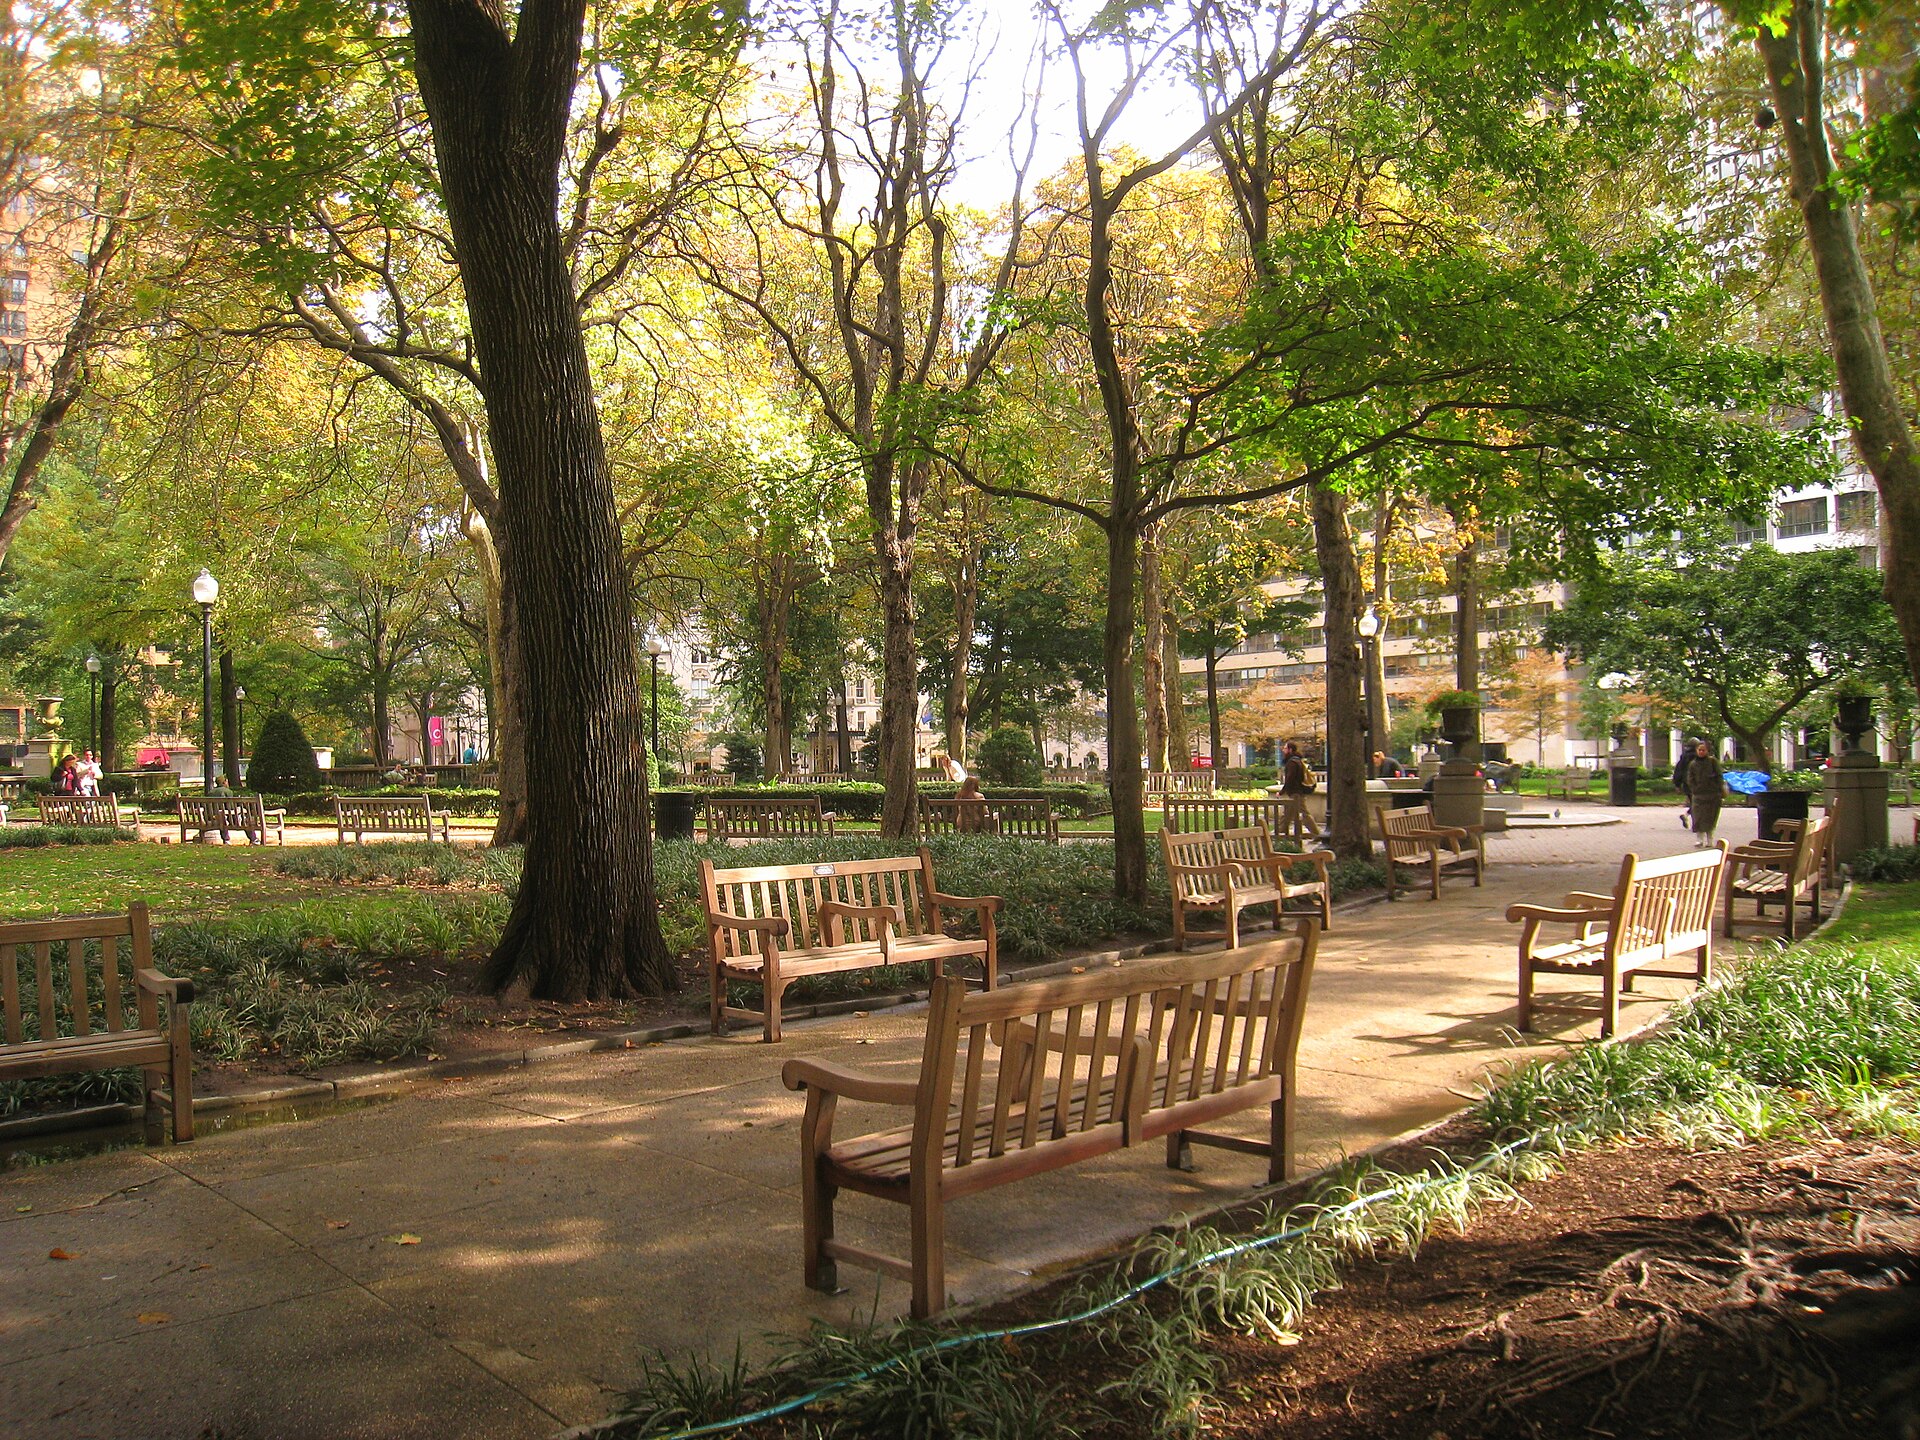
    In the right micro-market — a well-priced home in a sought-after Center City building, a rare offering in Rittenhouse Square or Society Hill, or a standout property in a tight South Jersey school district — luxury sellers sometimes find themselves with more than one serious buyer at the same time. Handling that situation well can meaningfully improve the outcome of a sale; handling it poorly can cost a seller the strongest buyer in the pool or create legal exposure. Here’s how experienced luxury sellers and their agents approach multiple offers and backup offers in Philadelphia and South Jersey.

    What a Multiple-Offer Situation Looks Like at the Luxury Level

    Multiple offers happen less often at the high end than in the entry-level market simply because the buyer pool is smaller and more selective, but they do happen — usually on homes that are genuinely well priced relative to their condition, location, and comparable sales, rather than on homes priced aspirationally. When it happens, sellers typically have some combination of a stronger offer emerge quickly, several offers arrive within a similar window, or one strong offer arrive while another buyer is still touring or drafting theirs. Each of these calls for a slightly different response, which is why having an agent who communicates clearly and promptly with all interested parties matters.

    Setting an Offer Deadline: When It Helps and When It Backfires

    A common tool in a multiple-offer situation is setting a deadline by which all offers must be submitted, so the seller can compare them side by side rather than reacting to whichever arrives first. This can work well when there’s genuine, confirmed interest from more than one buyer — but it can also backfire. Announcing a deadline when interest is thin can read as a pressure tactic and cause a hesitant buyer to walk away rather than compete. At the luxury level, where the buyer pool is smaller and often more risk-averse, this is a judgment call best made with real information about how many buyers are actually engaged, not just how many showings have occurred.

    Evaluating Offers Beyond Price

    The highest offer isn’t automatically the best offer. Sellers comparing multiple offers should weigh:

    • Financing strength. A cash offer or one with a large down payment and clear jumbo loan pre-approval typically carries less risk than a higher offer with a thin financing contingency.
    • Contingencies. An offer with fewer or shorter contingencies — inspection, financing, appraisal, sale of another home — closes with more certainty, even at a slightly lower price.
    • Closing timeline. A buyer whose timeline matches the seller’s needs (a faster close, or conversely more time to coordinate a move) can be worth more than the number on the page.
    • Appraisal risk. On a high offer relative to recent comparable sales, ask whether the buyer has agreed to cover an appraisal gap in writing, not just verbally.
    • Buyer’s agent and lender reputation. An experienced buyer’s agent and a lender known for closing on time reduce the odds of last-minute surprises.

    What Is a Backup Offer, and How Does It Work

    A backup offer is a fully negotiated purchase agreement from a second buyer that becomes active only if the primary, accepted contract falls through — due to a failed inspection negotiation, financing falling apart, or the primary buyer backing out. In both Pennsylvania and New Jersey, a seller can sign a backup agreement while still under contract with the primary buyer, as long as the backup agreement is clearly written to take effect only upon termination of the first contract, and the primary buyer generally does not need to be notified that a backup exists. For sellers, a signed backup offer is valuable insurance: if the primary deal collapses, the home can move directly to a second closing rather than back onto the open market from scratch.

    Communicating with Buyers’ Agents During Multiple Offers

    How a listing agent communicates during a multiple-offer scenario has real consequences for the seller’s outcome and reputation. Best practice is straightforward and consistent: let every buyer’s agent know that other offers exist (without disclosing specific terms of competing offers, which is both an ethical and often a legal boundary), give a clear and fair deadline if one is being used, and respond to all parties around the same time rather than negotiating serially and informally with one buyer while others wait. This approach tends to produce the strongest final offers and preserves goodwill with agents who represent buyers in the current transaction and potentially in future ones.

    Common Mistakes Sellers Make

    • Trying to bid up buyers informally over the phone instead of asking for best and final offers in writing, which can create confusion and, in some cases, legal risk.
    • Accepting the highest price without vetting financing, only to have the deal fail weeks later during underwriting.
    • Failing to secure a signed backup offer when a strong second buyer was available, leaving nothing in place if the primary contract falls apart.
    • Disclosing the specifics of one offer to another buyer, which can expose the seller and agent to claims of unfair dealing.

    Frequently asked questions

    Can a seller back out of an accepted offer if a better one comes in later?

    Generally no, not once a purchase agreement is fully signed and any contingency periods for the seller’s side have passed — the contract is binding on both parties. This is exactly why a backup offer, rather than trying to renegotiate after acceptance, is the appropriate tool if a stronger buyer appears after a contract is already signed.

    Do buyers know when they’re submitting a backup offer versus a primary offer?

    Yes, this should always be disclosed clearly. A backup offer is a distinct type of agreement, and the buyer signing one understands it only becomes active if the primary contract terminates.

    Is it legal to tell buyers that multiple offers exist?

    Yes, sellers and their agents can generally disclose that multiple offers exist, but should not disclose the specific terms of a competing offer without that buyer’s permission. Practices vary somewhat by local custom and brokerage policy, so this is worth confirming with your listing agent at the start of the process.

    If you’re preparing to list a luxury property and want a strategy tailored to your specific home and market, contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com.