Blog

  • Chimneys, Fireplaces, and Flues in Older Homes: A Luxury Buyer’s Guide for Philadelphia and South Jersey

    Chimneys, Fireplaces, and Flues in Older Homes: A Luxury Buyer’s Guide for Philadelphia and South Jersey

    Few features sell an older home faster than a working wood-burning fireplace, and few create more hidden risk. In the historic rowhouses of Society Hill and Rittenhouse, the stone estates of the Main Line, and the Colonial and Victorian homes of Haddonfield and Moorestown, chimneys are often original to the house and have been quietly aging for a century or more. This guide explains what luxury buyers and sellers should understand about fireplaces, flues, and chimney masonry in older Philadelphia and South Jersey homes.

    Why chimneys deserve their own inspection

    A general home inspection typically includes a visual look at the chimney and fireplace, but a visual look cannot see inside a flue. Clay tile liners crack, mortar joints erode, and old flues were often built without any liner at all. A cracked or missing liner can allow heat and combustion gases to reach nearby wood framing, which is why insurers and lenders pay attention to it.

    For a home with multiple fireplaces, a common feature in grand Main Line and Chestnut Hill houses, the cost and complexity multiply. Each flue is its own system with its own history, and not every fireplace in the house may be safe to use.

    The Level 2 chimney inspection

    Chimney professionals describe inspection levels. A Level 1 inspection is a basic visual check. A Level 2 inspection includes a video scan of the interior of the flue using a camera and is generally the right choice when a home is being bought or sold, or when a fireplace has not been used for years. Buyers of historic homes should ask their agent and inspector whether to schedule a Level 2 scan during the inspection period.

    Sellers can get ahead of this by having the scan done before listing. A clean report becomes a selling point; a problem found early can be repaired on the seller’s timeline instead of negotiated under deadline pressure.

    What inspectors commonly find

    • Cracked or missing flue liners that allow heat transfer to combustible framing.
    • Deteriorated mortar and spalling brick, especially above the roofline where weather exposure is greatest.
    • Failed or missing chimney crowns and caps, which let water into the masonry and the house.
    • Flashing leaks where the chimney meets the roof, often mistaken for roof failure.
    • Fireplaces that were closed off or converted without proper documentation.
    • Leaning or separating chimneys, sometimes tied to foundation movement.

    Wood-burning, gas, and decorative fireplaces

    Not every fireplace in a luxury home is meant to burn wood. Many have been converted to gas logs, fitted with gas inserts, or sealed entirely. Each configuration has its own rules. Gas appliances need proper venting and a correctly installed supply line, and a vent-free gas log set may be restricted or prohibited depending on the municipality. Decorative fireplaces in some newer homes were never designed for real fires.

    Buyers should find out what each fireplace actually is, who installed any conversion, and whether permits and final inspections exist. In Philadelphia and in New Jersey municipalities, work on gas lines and fireplace inserts often requires permits, and missing paperwork can surface at resale.

    Insurance and disclosure considerations

    Some insurers ask about solid-fuel heating sources, and a wood stove or insert can affect coverage or premiums. If you plan to use a fireplace regularly, confirm with your insurer before closing. On the sale side, Pennsylvania and New Jersey sellers should disclose known defects, including known chimney or flue problems, and honest disclosure protects sellers from disputes after settlement.

    Repair and restoration realities

    Chimney work ranges from routine cleaning and repointing to flue relining and full rebuilds above the roofline. In historic districts, particularly in Philadelphia, exterior changes visible from the street may require review by the Historical Commission, so matching brick, mortar, and detailing matters. Choose masons experienced with lime-based mortar on older brick; modern hard mortar can damage soft historic brick.

    Ask for written scopes, confirm the contractor carries insurance, and obtain an estimate before the end of your inspection contingency so you can negotiate credits or repairs while you still have leverage.

    A practical checklist for buyers and sellers

    • Order a Level 2 scan for any fireplace you plan to use.
    • Ask for documentation of past liner work, gas conversions, and permits.
    • Look for water staining on ceilings and walls near chimney chases.
    • Confirm smoke and carbon monoxide detectors are present and working.
    • Get repair estimates in writing before your due diligence period closes.

    Chimney care and seasonal maintenance

    A chimney that is used regularly should be inspected and cleaned annually. Even unused chimneys benefit from periodic checks of the cap, crown, and flashing, since animals, moisture, and debris can enter an idle flue. Use only seasoned hardwood, avoid burning trash or treated wood, and keep a metal-mesh screen in front of the opening. Sellers who can show a recent cleaning and inspection receipt are giving buyers an easy reason to feel comfortable.

    Frequently asked questions

    Can I use the fireplace in an older home right after buying it?

    Not until you know the flue is sound. Have a certified chimney professional perform a camera inspection and cleaning first, even if the seller says it was used recently.

    Who pays for chimney repairs found during inspection?

    It is negotiable. Buyers may request repairs, a credit, or a price reduction, while sellers may agree, counter, or decline. The outcome depends on the severity, the contract terms, and the market.

    Do sealed or capped fireplaces affect value?

    They can reduce appeal for buyers who want a working hearth, but a safely capped fireplace is far better than a poorly repaired one. Restoring a fireplace to working order may be worth exploring with a mason.

    Ready to talk through your plans? Contact James Kennedy, luxury real estate specialist serving Philadelphia and South Jersey, at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Sewer Laterals and Underground Utilities: A Luxury Buyer’s Guide to the Hidden Systems Beneath Older Philadelphia and South Jersey Homes

    Sewer Laterals and Underground Utilities: A Luxury Buyer’s Guide to the Hidden Systems Beneath Older Philadelphia and South Jersey Homes

    Buyers of high-end homes tend to focus on kitchens, finishes, and floor plans, but some of the costliest surprises in older properties are buried under the lawn or the sidewalk. The sewer lateral, the water service line, and related underground systems can fail quietly and become expensive to repair or replace.

    This guide explains what these systems are, why they matter in the Philadelphia region, and how to protect yourself during the purchase process.

    What is a sewer lateral?

    The sewer lateral is the pipe that carries wastewater from your home to the municipal sewer main, usually located under the street. In most cases the property owner is responsible for the lateral from the house to the connection point, which can include the portion under the sidewalk or street. Responsibility boundaries differ by municipality, so confirm the rules for the specific address.

    Older homes may have laterals made of clay, cast iron, or other materials that can crack, shift, or be invaded by tree roots. Newer materials like PVC are more durable but are not immune to damage from settling or poor installation.

    Why it matters in Philadelphia and South Jersey

    Much of the region’s housing stock is decades or even more than a century old, and mature street trees are a hallmark of many desirable neighborhoods, which also means roots seeking moisture in aging pipes. Homes in dense Center City blocks, older Main Line estates, and historic South Jersey boroughs can all have original or partially replaced lines.

    A failed lateral can cause backups, slow drains, foul odors, and foundation moisture problems. Repairs may involve excavation through landscaping, driveways, or public rights-of-way, which can raise cost and complicate permitting.

    How to inspect: the sewer scope

    A sewer scope inspection uses a camera fed through the line to reveal cracks, offsets, root intrusion, bellies where water pools, and collapsed sections. It is typically an optional add-on to the general home inspection, and for any older luxury home it is a modest cost compared with the potential repair bill.

    • Ask the inspector to provide the video and a written summary.
    • Request the location of the cleanout and the pipe material.
    • Have a plumber review any significant defect and provide a repair estimate.

    Other buried systems to consider

    Beyond the sewer lateral, ask about the water service line material, since older lead or galvanized lines may need replacement and can affect water quality. Our guide on environmental testing covers water testing in more detail. Properties in parts of South Jersey may have underground oil tanks or private wells and septic systems, which we cover in separate guides. Also ask about buried gas lines, drainage systems, French drains, and irrigation or landscape lighting that may be tied into the property.

    On larger estates, long driveways, private utility runs, and detached structures can add buried infrastructure that deserves its own review.

    Using findings in negotiation

    If a scope reveals defects, you have options: request a repair before settlement, negotiate a credit or price adjustment, or reconsider the purchase. Inspection timelines are limited by the terms of your agreement, so schedule the scope early. In New Jersey, the attorney review period and inspection contingency provide structure for these conversations, while Pennsylvania buyers rely on the inspection contingency in the agreement of sale.

    Also ask whether the municipality requires a lateral inspection or certification at the time of sale. Some do, and requirements can affect timing and who pays.

    Insurance and ongoing maintenance

    Standard homeowners policies often exclude wear-and-tear failures of buried lines. Ask your insurance professional about optional service-line coverage and what it includes. After closing, schedule periodic cleaning or inspections, manage tree roots near the line, and avoid flushing items that stress older pipes.

    Typical costs and timelines

    A camera scope is generally inexpensive relative to a purchase of this size, while a full lateral replacement can run from a few thousand dollars into five figures depending on depth, length, access, and restoration requirements. Trenchless repair methods can reduce disruption in some cases, but they are not suitable for every pipe condition. Obtain more than one estimate when a defect is found, and ask each contractor to explain the method, the permit requirements, and the warranty on the work.

    Questions to ask the seller

    Request any records of prior repairs, relining, or replacements. Ask whether the home has ever experienced a sewer backup, whether root cutting has been needed, and whether a plumber has performed a camera inspection. Sellers who have already addressed the line can often provide documentation that supports your confidence in the property, and sellers preparing to list may consider a pre-listing scope of their own so that surprises do not derail a contract later.

    Frequently asked questions

    Who pays for a sewer lateral repair?

    In many municipalities the property owner is responsible for at least part of the lateral, but rules vary. Confirm local responsibility and any sale-time requirements for the address you are considering.

    Is a sewer scope worth it for a newer luxury home?

    It can still be valuable, since installation defects and settling can occur, but the risk is generally higher for older homes and properties with large mature trees near the line.

    Can I negotiate after a scope finds a problem?

    Yes, within the timelines and contingencies of your agreement. Options typically include repair, a credit, a price change, or termination, depending on the terms and the severity of the defect.

    Ready to talk through your options? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a private, no-pressure conversation about luxury real estate in Philadelphia and South Jersey.

  • Oreland and Maple Glen, Pennsylvania: A Montgomery County Guide for Luxury Home Buyers

    Oreland and Maple Glen, Pennsylvania: A Montgomery County Guide for Luxury Home Buyers

    Between the northern edge of Philadelphia and the Route 309 corridor, Oreland and Maple Glen offer well-kept suburban neighborhoods with a mix of established single-family homes and newer executive-style construction. For buyers who want room to spread out, reasonable commutes, and strong local amenities, these Montgomery County communities often fit the brief.

    Below is a practical overview of both areas and the questions luxury buyers should ask before they commit.

    Oreland: established streets and rail access

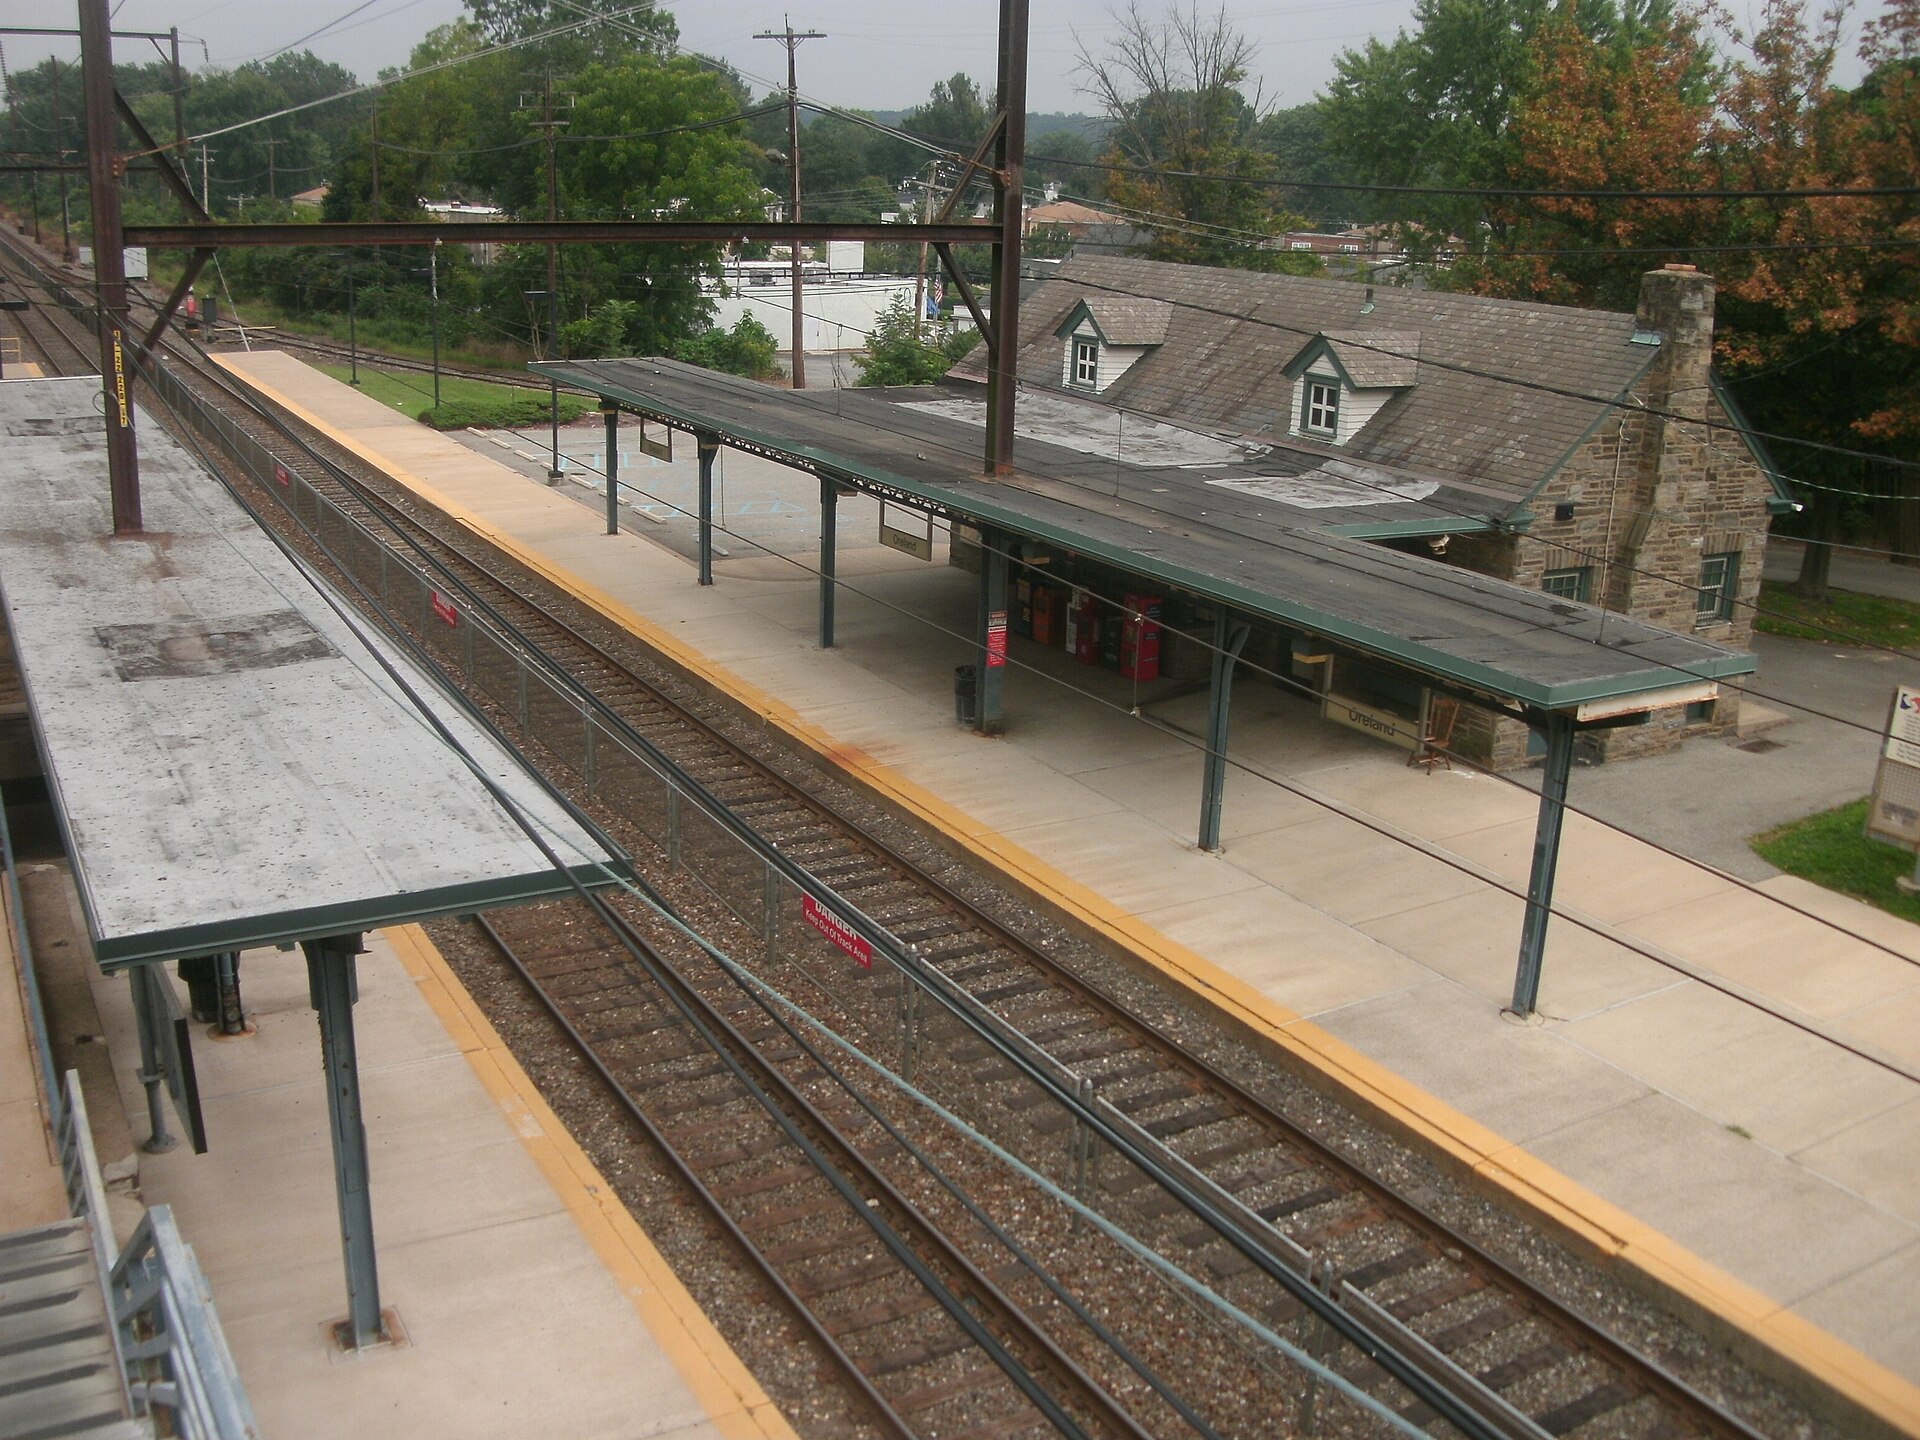
    Oreland lies largely within Springfield Township, Montgomery County, and is known for its leafy residential streets, mid-century and earlier homes, and a small commercial center near the rail station. Housing includes stone and brick Colonials, Cape Cods, ranches, and a growing number of substantially renovated or expanded homes. Rail service toward Center City is a significant draw for commuters who prefer not to drive downtown.

    Buyers drawn to Oreland often prioritize lot size, tree cover, and a neighborly feel over brand-new construction, and are willing to renovate or select homes where the work has already been done.

    Maple Glen: newer construction and larger floor plans

    Maple Glen, part of Upper Dublin Township, tends to feature larger, more recently built homes, including executive Colonials and Traditional-style houses in planned subdivisions with curving streets and cul-de-sacs. Floor plans are generally open and family-oriented, with finished basements, three-car garages, and spacious primary suites common in the upper range.

    Because many of these homes are one or two generations old, buyers should evaluate the age of major systems such as roofs, HVAC, and windows, and look closely at the quality of finishes rather than assuming newer always means better.

    What drives value in this part of Montgomery County

    • School district assignment: Public school boundaries are a major factor for many buyers. Confirm assignment for the specific address directly with the district.
    • Lot and privacy: Backing to open space, a park, or a buffer of trees generally improves desirability.
    • Condition and updates: Turnkey kitchens, baths, and finished lower levels carry a clear premium.
    • Commute options: Proximity to rail or major roads affects daily convenience and resale appeal.

    Daily life and amenities

    Residents have access to parks, trails, community events, shopping centers, and dining within a short drive. Nearby Fort Washington, Ambler, and Blue Bell expand the options, and we cover several of those communities in separate guides. For private-school and cultural access, the region offers plenty of choices within a reasonable drive.

    Spend time visiting at different times of day and compare traffic patterns on the routes you will actually use.

    Buying strategy and negotiation

    In well-maintained neighborhoods, move-in-ready homes can draw competing interest, particularly in the spring. A pre-approval letter, a clear understanding of your inspection priorities, and flexibility on timing can strengthen your offer without overpaying. For homes with unique features or recent expansions, ask for permits and documentation of the work.

    Pennsylvania buyers should plan for transfer taxes, title insurance, and local tax implications. A thoughtful financing plan, including whether a jumbo loan makes sense, is worth discussing early.

    Taxes, costs, and long-term planning

    Property taxes in Montgomery County communities vary by municipality and school district, and assessed values can change over time. Ask for the current tax bill, understand how reassessment could affect you, and factor in utilities, insurance, and maintenance for a larger home and lot. If you are comparing Oreland and Maple Glen to other suburbs, evaluate total monthly carrying cost rather than purchase price alone.

    Touring tips for these communities

    Visit neighborhoods on a weekday morning to observe commuter traffic, and again on a weekend to see how parks and shopping areas are used. Walk the lot lines, check drainage after rain if possible, and look at how neighboring homes are maintained. Ask the listing agent about recent updates, the age of the roof and mechanical systems, and any known issues. Small observations during a visit often reveal more than the listing photos do, and they can help you decide which homes merit a second showing.

    It also helps to consider how your needs may change. A home office, an in-law suite, or flexible lower-level space can matter as much in five years as they do today.

    Finally, remember that lifestyle fit matters as much as specifications. Talk with neighbors, visit local shops, and consider how weekends, school activities, and commutes would feel in practice. Buyers who match the community to their routines tend to be happiest over the long term, and they are also the buyers who make the most disciplined offers.

    Frequently asked questions

    Which is more expensive, Oreland or Maple Glen?

    It varies by home. Maple Glen tends to offer newer and larger construction, while Oreland offers older, character-rich housing with transit access. Compare individual properties rather than assuming one area is always higher priced.

    Are Oreland and Maple Glen good for commuters?

    Oreland has a rail station that serves Center City, and both areas have access to major roads. Your own commute depends on the exact address and destination, so test it before buying.

    Do I need a jumbo loan here?

    If your loan amount exceeds the conforming limit for the county, a jumbo mortgage may apply. A lender can confirm the current limit and the terms available to you.

    Ready to talk through your options? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a private, no-pressure conversation about luxury real estate in Philadelphia and South Jersey.

  • Drexel Hill and Lansdowne, Pennsylvania: A Delaware County Guide for Luxury Home Buyers

    Just west of Philadelphia, Drexel Hill and Lansdowne offer something that is increasingly hard to find near the city: substantial, architecturally distinctive houses on generous lots, with a direct rail connection to Center City. For buyers who want character and square footage without the price profile of the Main Line, these Delaware County communities deserve a closer look.

    This guide covers what the housing stock looks like, how commuting works, what to inspect, and how to approach a purchase in the upper range of each market.

    Two communities, two personalities

    Drexel Hill is a large, primarily residential section of Upper Darby Township. Its higher-ground streets feature stone and brick Colonials, Tudors, and Dutch Colonials, many built in the early to mid twentieth century, with mature trees and a quiet, established feel. Some of the most sought-after blocks sit near the township’s wooded park areas and on the hillside streets away from the main commercial corridors.

    Lansdowne is a separate borough with its own government and a compact, walkable downtown. Its housing is notable for Victorian-era twins and singles with deep porches, plus a number of larger detached homes near the borough’s edges. Lansdowne’s arts-oriented, community-minded identity and its walkable commercial blocks attract buyers who value a village feel.

    The housing stock buyers should expect

    The most compelling homes here are typically pre-war: stone Colonials, Tudor revivals with slate roofs, and Queen Anne or Italianate Victorians with original millwork, stained glass, and wide staircases. Lot sizes and room proportions often exceed what is available in similar-priced newer construction.

    • Original details: Plaster walls, hardwood floors, built-ins, and leaded glass are major value drivers when intact.
    • Updated systems: Homes with modernized kitchens, electrical service, and mechanicals command a clear premium over those needing full renovation.
    • Additions: Well-executed rear additions that add a family room or primary suite are common; permits and quality of work matter.

    Commuting and daily life

    Both communities are served by SEPTA’s regional transit network, including trolley routes and rail options toward Center City and University City. Many residents also rely on nearby arterial roads and highway access for trips to the airport, the Main Line, and South Jersey. Test your actual commute at the times you would travel before committing, since transit proximity varies block by block.

    Everyday amenities include neighborhood shopping districts, parks, and a range of local restaurants. Buyers should visit on a weekday evening and a weekend morning to get a sense of the rhythm of each street.

    Inspection priorities for older homes

    Houses of this age reward careful inspection. Pay particular attention to the roof and flashing, chimney condition, basement moisture, the sewer lateral, original wiring or partial updates, and heating systems. In sloped neighborhoods, drainage and grading deserve a close look. Our related guides on wet basements, older-home wiring, and wood-destroying insects explain what to ask for in detail.

    Because roofs such as slate or tile can be costly to repair, a specialist roofing opinion is often worth the modest expense before you remove contingencies.

    How to approach a high-end purchase

    Well-presented homes in desirable pockets can attract multiple interested buyers, so preparation matters. Get a lender’s pre-approval in hand, understand how an appraisal may compare to your offer on a unique older home, and decide in advance which inspection findings you would negotiate versus walk away from. Because comparable sales for distinctive houses can be sparse, a thoughtful pricing analysis is more reliable than a simple per-square-foot average.

    Be mindful of Pennsylvania transfer taxes, local taxes, and school district considerations when comparing these towns to neighboring options. A local advisor can help you weigh the full cost of ownership rather than just the list price.

    Who tends to buy here, and why

    Buyers in Drexel Hill and Lansdowne are often move-up purchasers leaving smaller city rowhomes, families who want a yard without a long commute, and downsizers who value walkable amenities. Many are comparing these towns against the Main Line, Media, and Swarthmore, and the deciding factor is frequently how much house and land their budget buys. Taking the time to tour several blocks in both communities will reveal how much the feel changes from one street to the next.

    Renovation potential and resale considerations

    Because so many homes here are older, renovation is a recurring theme. A thoughtfully updated kitchen, a finished lower level, and restored original details tend to support resale, while over-improving beyond the neighborhood’s typical price range can be difficult to recoup. Before purchasing a project house, obtain contractor estimates, confirm what permits are required, and build a contingency into your budget. Keep in mind that the strongest long-term performers are usually well-located homes on desirable blocks with sound structure and systems, rather than the most heavily customized properties.

    Frequently asked questions

    Is Drexel Hill considered a luxury market?

    Drexel Hill is best described as a strong value market for larger, character-rich homes. The most distinctive properties on desirable blocks can reach the upper tiers of the local market, but buyers should compare each home on its condition, lot, and location rather than relying on a general label.

    What is the difference between Drexel Hill and Lansdowne?

    Drexel Hill is a section of Upper Darby Township with wooded streets and larger lots, while Lansdowne is an independent borough with a walkable downtown and Victorian-era housing. Taxes, services, and school district assignments can differ, so verify specifics for any address.

    How long is the commute to Center City?

    It depends on the mode and address. Transit options exist in both communities, and many buyers also drive. Test the route during your actual commuting hours before making an offer.

    Ready to talk through your options? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a private, no-pressure conversation about luxury real estate in Philadelphia and South Jersey.

  • Termites and Wood-Destroying Insects: An Inspection Guide for Older Philadelphia and South Jersey Homes

    Termites and Wood-Destroying Insects: An Inspection Guide for Older Philadelphia and South Jersey Homes

    Termites rarely make headlines, yet wood-destroying insects can quietly damage a home’s structure for years before anyone notices. In older Philadelphia rowhomes, South Jersey colonials, and Main Line stone-and-timber estates, a wood-destroying insect inspection is one of the most valuable pieces of due diligence a luxury buyer can order. Here is what it covers, what it does not, and how it fits into negotiations in Pennsylvania and New Jersey.

    What the inspection looks for

    A wood-destroying insect (WDI) inspection, often called a termite inspection, is a visual evaluation by a licensed pest professional. The inspector looks for active infestations, evidence of past activity, and conditions that invite future problems. The common culprits in our region include:

    • Subterranean termites, which live in soil and build mud tubes to reach wood.
    • Carpenter ants, which excavate damp wood to nest and are often tied to moisture problems.
    • Powderpost beetles, which can riddle older hardwood framing and flooring with small exit holes.
    • Carpenter bees, which bore into exposed trim, eaves, and decks.

    Why older and luxury homes deserve extra attention

    Historic homes often have wood in contact with masonry, crawl spaces, older additions, and complex rooflines that hide moisture. Large estate properties may include detached garages, carriage houses, porches, and landscape timbers that also need evaluation. Mulch piled against siding, firewood stored against the house, and poor drainage all raise risk. Finished basements and renovations can conceal framing, so inspectors sometimes cannot see everything, which is why scope and limitations matter.

    What the report can and cannot tell you

    A WDI report documents what was visible and accessible on the day of inspection. It typically does not guarantee that hidden areas are free of damage, and it may recommend a structural engineer or a general contractor to assess any damage found. Read the limitations section closely and ask the inspector to explain inaccessible areas, such as spaces behind finished walls or under insulation.

    How lenders and contracts treat it

    Some lenders and loan programs require a clean WDI report, and some buyers order one even when it is optional. In both states, the purchase agreement and the inspection contingency timeline determine your options, so schedule the inspection early. In New Jersey, the attorney review period offers additional structure for negotiation, while in Pennsylvania the contract’s inspection contingency governs your window. Your agent and attorney can confirm the precise deadlines for your contract.

    Negotiating when activity is found

    Findings usually lead to one of several outcomes: the seller arranges treatment and repair before closing, offers a credit, adjusts the price, or the buyer withdraws within the contingency period. Ask for the treatment method, proof of a licensed provider, any warranty or renewal terms, and a written scope for structural repairs. For ongoing protection, ask whether an existing termite bond or service contract can transfer to you, and what it covers.

    Practical steps after you buy

    • Keep soil, mulch, and firewood away from the foundation.
    • Fix leaks, gutters, and drainage that keep wood damp.
    • Schedule periodic inspections, especially in older structures.
    • Keep records of treatments and warranties for resale.

    Choosing a licensed inspector and reading the scope

    Look for a state-licensed pest control or inspection professional who is willing to explain findings on site, ideally during the walk-through with your general home inspector. Ask whether the inspection includes detached structures, decks, fences, and crawl spaces, and what areas will be inaccessible. A thorough inspector will probe suspect wood, check moisture-prone areas, and note conditions such as wood-to-soil contact, wet crawl spaces, and failed flashing that make the house vulnerable even if no insects are present today.

    Treatment methods and what to ask the seller

    Treatment may involve liquid soil barriers, bait systems, or localized wood treatments, depending on the insect and the structure. Ask which method is proposed, whether the work comes with a written warranty, how long it lasts, and what the renewal terms are. If a seller has a long-standing service contract, request the history of inspections and treatments. A documented, continuous program is reassuring on an older home, while an undocumented history merits more caution and a closer look by a structural professional.

    Repairs versus replacement

    Damage found during a sale ranges from superficial to structural. Cosmetic repairs to trim or flooring are very different from replacing a sill plate or joist. When damage is more than minor, get a written repair scope from a qualified contractor or engineer before agreeing to a credit, so the amount reflects the true cost. Historic homes can also have material-matching and preservation considerations that raise costs, so factor those in when you negotiate.

    Frequently asked questions

    Is a termite inspection required when buying a home?

    It depends on the lender, loan type, and your contract. Even when it is optional, it is a smart precaution for older and larger homes.

    Does a clean report mean the house is free of termite damage?

    Not necessarily. The report reflects visible, accessible areas on inspection day and may not detect hidden damage. Ask about the limitations.

    Who pays for termite treatment found during a sale?

    That is negotiable and governed by your contract. Sellers often treat or credit the buyer, but outcomes vary, so negotiate within your contingency deadline.

    Ready to talk through your plans? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation about luxury real estate in Philadelphia and South Jersey.

  • Rate Locks, Extensions, and Float-Downs: A Jumbo Mortgage Timing Guide for Luxury Buyers

    For luxury buyers, a mortgage rate lock is one of the most consequential and least understood decisions in the transaction. On a large jumbo loan, even a small movement in rate can change the monthly payment meaningfully, and a missed lock deadline can complicate a closing. This guide explains how rate locks, extensions, and float-down options work so you can plan alongside your lender and your agent in Pennsylvania and New Jersey.

    What a rate lock actually is

    A rate lock is a lender’s commitment to hold a specific interest rate and pricing for a defined period, provided your loan file stays materially the same. Locks are tied to a loan program, a loan amount, and assumptions about your credit, assets, income, and the property. If those assumptions change, the lock terms can change too.

    Until you lock, your rate floats with the market. Some buyers lock at application, others wait for a contract or for a specific stage in underwriting. Neither approach is universally right; the choice depends on your risk tolerance and your timeline.

    Choosing a lock period that matches your closing

    Lock periods are commonly offered in increments, and longer locks typically cost more in rate or points. The key is to match the lock to a realistic closing date, with a cushion. Consider the factors that lengthen timelines in the Philadelphia region:

    • Pennsylvania and New Jersey contract timelines, including inspections and, in New Jersey, the attorney review period.
    • Appraisal scheduling, which can take longer for unique, historic, or estate-style properties.
    • Condo or co-op documentation and board approvals.
    • Title work, surveys, and municipal certificates of occupancy in New Jersey.
    • Complex income documentation for self-employed and high-net-worth borrowers.

    Lock extensions and what they cost

    If closing slips past the lock expiration, lenders typically offer extensions priced by the number of days. Extensions are far cheaper than relocking at a worse rate, but they still cost money. Ask your lender up front how extensions are priced and who bears the cost if the delay stems from the seller, the title company, or an appraisal issue. Your purchase agreement may allocate responsibility, so raise the topic before you sign.

    Float-down options

    A float-down lets you capture a lower rate if the market improves after you lock, usually for a fee or a slightly higher locked rate, and often with conditions such as a minimum improvement threshold and a limited window. Whether it is worth it depends on the cost and how long your lock runs. Request the terms in writing and compare them with simply paying for a slightly longer standard lock.

    Protecting your lock through underwriting

    Most lock problems are self-inflicted. Avoid opening new credit, financing furniture, moving large sums between accounts without documentation, or changing jobs during the process. For jumbo and portfolio loans, underwriters scrutinize assets closely, so respond to document requests quickly. Coordinate with your lender before any change to the property, the loan amount, or the down payment.

    Questions to ask your lender

    • When can I lock, and what is the lock period cost at different lengths?
    • What is your extension fee schedule?
    • Do you offer a float-down, and under what conditions?
    • What events can change my locked terms?
    • How long do you expect appraisal and underwriting to take for this property type?

    This article is general education and not financial or lending advice; confirm all terms with a licensed mortgage professional.

    Coordinating the lock with contract deadlines

    Your lock should be built backward from the closing date in your purchase agreement. List every milestone that has to occur first: inspection and negotiation, appraisal, underwriting conditions, insurance binding, title commitment, survey where applicable, and the final loan documents. Then add a cushion for the unexpected. In a competitive luxury deal, a buyer who can show a lender-approved, locked loan with realistic timing may present a stronger offer than one still floating, so discuss with your agent how financing certainty reads to sellers.

    Points, credits, and the lock

    Rate and cost trade off. A lower rate may require discount points paid at closing, while a higher rate may come with a lender credit. When you lock, you are locking a specific combination, so make sure the closing cost estimate you review matches the lock confirmation. If you negotiated seller concessions toward a rate buydown, confirm with your lender how those funds will be applied and whether program limits apply, then ensure the contract language lines up with the lender’s rules.

    Special considerations for jumbo and non-traditional borrowers

    Jumbo loans, portfolio loans, and asset-based programs often involve more manual underwriting, and lender timelines can vary. Borrowers with business income, equity compensation, trusts, or multiple properties should expect more documentation. Build extra time into both the contract and the lock, and consider engaging your lender before you start touring so that documentation is ready the day you find the right home.

    Frequently asked questions

    When should I lock my mortgage rate?

    There is no single right moment. Many buyers lock once they are under contract and have a realistic closing date, while others lock earlier for certainty. Discuss your risk tolerance and timeline with your lender.

    What happens if my lock expires before closing?

    Your lender may offer an extension for a fee, or you may need to relock at current market pricing. Ask about extension costs before locking and plan a cushion into your closing date.

    Is a float-down worth paying for?

    It can be if you lock early and expect rates may fall, but the fee and conditions matter. Compare the cost with a standard lock and get the terms in writing.

    Ready to talk through your plans? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation about luxury real estate in Philadelphia and South Jersey.

  • Westtown and Thornbury, Pennsylvania: A Chester and Delaware County Guide for Luxury Home Buyers

    Westtown and Thornbury, Pennsylvania: A Chester and Delaware County Guide for Luxury Home Buyers

    Westtown and Thornbury sit along the line where Chester and Delaware Counties meet, a few miles south of West Chester and a short drive from the Main Line, Wilmington, and Philadelphia International Airport. For luxury buyers who want rolling land, historic stone houses, and strong public and independent school options without paying Main Line premiums, this corner of the Brandywine region deserves a close look. Here is how to think about it.

    Where Westtown and Thornbury fit in the region

    Westtown Township lies in Chester County, while Thornbury Township straddles the county line, with parts in Chester and Delaware Counties. That geography matters more than most buyers expect: school districts, property tax structures, and municipal ordinances can differ from one side of a road to the other. Always confirm the exact municipality and school district for any address rather than relying on a mailing-address town name.

    The area blends early American farmland, post-war subdivisions, and newer executive neighborhoods. Stone farmhouses and converted barns share the landscape with colonial revivals and contemporary builds on multi-acre lots, and you will find both quiet cul-de-sac enclaves and long country roads.

    The housing stock luxury buyers will find

    • Historic stone farmhouses and manor homes. Fieldstone and early Pennsylvania farmhouse construction, often expanded over centuries. These reward careful inspection of foundations, roofing, mechanical systems, and any additions.
    • Executive colonials and estate-style homes. Larger custom and semi-custom homes on one to several acres, frequently with finished lower levels, three-car garages, and pool-ready yards.
    • Land and small equestrian-style properties. Some parcels offer pasture, outbuildings, or conservation-minded acreage. Fencing, drainage, and zoning for animals all deserve verification.

    Because older and larger properties here often rely on private wells and on-lot septic systems, budget time for water testing and septic evaluation. Our guides on wells, septic systems, and acreage walk through that process in detail.

    Lifestyle and everyday convenience

    Westtown is known for its long-established independent school presence, and the surrounding area offers open space, trails, and farm-to-table dining. West Chester Borough, with its restaurants, shops, and cultural calendar, is a short drive away. Routes toward Route 202, Route 1, and Route 100 make commuting to Wilmington, King of Prussia, the Main Line, and Center City workable, though rush-hour patterns vary, so test your own commute at the times you will actually drive it.

    Buyers who value privacy often prefer the more rural stretches, while those who want neighbors and walkable errands may lean closer to West Chester. Spending a weekend morning and a weekday evening in the neighborhoods you are considering tells you far more than a listing description.

    Pricing and valuation principles

    Luxury values in this area are driven by lot size and usability, condition and quality of any renovation, school district assignment, proximity to West Chester, and privacy. Unique homes can be difficult to price with simple comparables, so a thoughtful analysis weighs adjustments for acreage, outbuildings, and historic character rather than leaning on price per square foot alone. We do not publish figures here because they shift; James can provide current, address-specific guidance.

    Due diligence checklist for Westtown and Thornbury purchases

    • Confirm the municipality, county, and school district for the exact parcel.
    • Order well-water quality and flow tests and a septic inspection where applicable.
    • Inspect stone foundations, chimneys, slate or older roofing, and historic wiring.
    • Review easements, conservation restrictions, and any floodplain or wetland areas on the survey.
    • Check permits for additions, finished basements, and pools.

    Working with a local agent on a Westtown or Thornbury search

    Because the municipal and school boundaries here are so fine-grained, local knowledge saves real time. A knowledgeable agent can tell you which side of a township line a property sits on, which roads tend to carry commuter traffic, how a particular neighborhood handles snow removal and road maintenance, and which homes have historically drawn strong interest from relocating executives and families tied to the area’s schools. That context turns a long list of listings into a short list worth touring.

    Seasonality and touring tips

    Country properties look very different across seasons. Spring reveals drainage problems and how a yard handles saturated ground, while winter exposes road conditions, heating performance, and the true amount of sun a house receives. When possible, tour promising properties more than once and in different weather. Ask sellers for utility histories, well and septic records, and any documentation of past renovations or restoration work on historic structures. Those records are especially valuable on stone farmhouses where changes accumulated over generations.

    Planning for ownership costs

    Beyond the purchase price, estate-style properties in this area carry ongoing costs that deserve a line in your budget: landscaping and tree care, driveway and fence maintenance, septic pumping and well servicing, roof and chimney upkeep on older structures, and insurance that reflects replacement cost for custom or historic construction. Speak with an insurance professional early, since older homes with specialty materials such as slate or custom millwork can be priced differently than newer builds.

    Frequently asked questions

    Is Thornbury in Chester County or Delaware County?

    Both. Thornbury Township has portions in each county, so verify the county and school district of any specific address before assuming how taxes or schools apply.

    Do homes in this area usually have public water and sewer?

    Many larger and older properties use private wells and on-lot septic, while some neighborhoods are served by public systems. Confirm the utilities for each property and budget for testing.

    How is this area different from the Main Line?

    Generally you find more acreage, a more rural feel, and a different price profile, with a somewhat longer commute to Center City. Individual homes vary widely, so compare specific properties rather than broad labels.

    Ready to talk through your plans? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation about luxury real estate in Philadelphia and South Jersey.

  • Wet Basements, Sump Pumps, and Waterproofing: A Luxury Buyer’s Guide for Older Philadelphia and South Jersey Homes

    Wet Basements, Sump Pumps, and Waterproofing: A Luxury Buyer’s Guide for Older Philadelphia and South Jersey Homes

    In the Philadelphia region, many of the most charming homes share a quiet vulnerability: the basement. Stone foundations, older rowhomes, river-adjacent lots, and hillside properties can all encounter moisture over time. For luxury buyers, a finished lower level, wine cellar, or home theater can lose value quickly if water management has been neglected. This guide explains what to look for, the common solutions, and what questions to ask before closing.

    Why water shows up in older regional homes

    Many historic Philadelphia and South Jersey homes were built with stone, brick, or early masonry foundations designed in an era before modern waterproofing. Soil conditions, grading, and aging drainage can all let moisture reach the interior. High water tables near rivers, creeks, and parts of the Jersey coast add to the challenge, and heavy rain events stress older drainage systems further.

    Clues to look for during a showing

    You can learn a great deal on a first visit by paying attention to:

    • White, chalky mineral deposits on masonry walls, called efflorescence.
    • Musty smells, especially in closed-up lower levels.
    • Fresh paint or new drywall on only some walls, which may conceal past staining.
    • Dehumidifiers running continuously, or sump pumps with visible discharge lines.
    • Gutters, downspouts, and ground sloping toward rather than away from the foundation.

    Common systems and what they do

    Interior drainage systems collect water at the base of the walls and direct it to a sump pump. Exterior waterproofing involves excavating around the foundation to apply membranes and drainage, which is more invasive and costly but addresses water before it enters. Simple grading, gutter extensions, and downspout repairs resolve many problems at modest cost. Sump pumps should have a backup, whether a battery system or a water-powered unit, since storms often coincide with power outages.

    Ask who installed any system, when, and whether a transferable warranty exists. Documentation matters, particularly for finished spaces that rely on the system working.

    Inspection and due diligence

    A general home inspection is a starting point, but properties with a history of moisture often justify a specialist. A structural engineer can evaluate cracks and movement, while a waterproofing professional can assess drainage options. Review seller disclosures carefully, and ask directly about past water entry, repairs, and insurance claims. In New Jersey and Pennsylvania, disclosure requirements and contract terms differ, so rely on your attorney and agent to interpret what the seller has stated.

    Finished basements and luxury features

    If the lower level includes custom millwork, wine storage, or media rooms, find out how those finishes were built. Materials placed directly against masonry can trap moisture, while well-designed assemblies leave room for drainage and airflow. Climate control is critical for wine and art, so verify that humidity management is reliable and appropriately sized.

    Insurance considerations

    Standard homeowners policies often exclude certain kinds of water damage, such as groundwater seepage or flood. Sump pump failure and sewer backup typically require separate endorsements. Speak with your insurance professional before closing to understand coverage and any limits, particularly for finished spaces and valuable contents.

    Selling a home with a water history

    For sellers, transparency and documentation are the best strategy. A clear record of repairs, warranties, and drainage improvements reassures buyers and supports your price. Addressing visible issues before listing, and providing receipts for professional work, helps keep negotiations focused and inspection surprises to a minimum.

    Maintenance habits that protect a lower level

    Even a well-built system needs care. Keep gutters clean and downspouts extended several feet away from the foundation, test the sump pump a few times a year by pouring water into the pit, and replace batteries in backup units on schedule. Store belongings off the floor in unfinished areas and keep an eye on humidity levels with an inexpensive monitor. Small habits like these prevent the slow moisture problems that often damage finished spaces before anyone notices.

    Budgeting for correction

    Costs vary enormously depending on the cause and scope, from minor grading and gutter work to extensive excavation. Instead of relying on a single number, collect at least two written estimates from reputable, insured contractors and ask what each proposal does and does not include. Having that information before your inspection period ends gives you real negotiating power and helps you decide whether the home is the right fit.

    Questions to ask the seller and your inspector

    Before you commit, ask the seller when the lower level last had water, what was done in response, and whether any insurance claims were filed. Ask your inspector to note the age and condition of the sump pump, the discharge location, and any signs of past repairs. If the home sits near a creek, river, or tidal area, review flood maps and elevation information as part of your due diligence. These conversations rarely take long, and they often reveal the most useful information about a home you are considering seriously.

    Finally, consider the long view. A home with a well-documented drainage system and a history of careful maintenance can be a better purchase than a dry-looking home with no records at all.

    Frequently asked questions

    Is a damp basement a deal breaker in an older home?

    Not necessarily. Many older homes manage moisture successfully. The key is understanding the cause, the cost to correct it, and whether existing systems are documented and working.

    Should I get a specialist inspection for basement moisture?

    If you see signs of past or current water entry, a waterproofing specialist or structural engineer can give you a clearer picture than a general inspection alone.

    Does homeowners insurance cover basement flooding?

    Coverage varies. Groundwater seepage, flood, and sewer or sump backup are often excluded unless you add specific coverage, so review your policy with your insurance professional.

    Ready to talk? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for guidance tailored to your situation and current figures for your target area.

  • Inspection Negotiations: Repair Requests, Credits, and Price Reductions for Luxury Buyers in Pennsylvania and New Jersey

    Inspection Negotiations: Repair Requests, Credits, and Price Reductions for Luxury Buyers in Pennsylvania and New Jersey

    Few moments in a luxury purchase test a deal like the days after the home inspection. The report arrives, the list of findings looks long, and both sides must decide what is worth negotiating. Handled well, the process protects the buyer without souring a deal; handled poorly, it can unravel an otherwise strong contract. Here is how repair requests and credits typically work in Pennsylvania and New Jersey, and how to approach them strategically.

    Know your contract deadlines first

    The inspection contingency in your agreement sets the timeline for delivering requests, and the rules differ by state and by the specific contract. In New Jersey the attorney review period and contingency terms shape the process, while Pennsylvania agreements set their own inspection periods. Missing a deadline can waive your leverage, so confirm dates the moment the contract is signed and have your agent and attorney track them.

    Separate the findings into categories

    Not every item in an inspection report deserves a negotiation. A useful way to sort findings is:

    • Safety and health issues, such as electrical hazards, active leaks, or gas appliance concerns.
    • Major systems, including roofing, structure, heating and cooling, and plumbing.
    • Deferred maintenance that is expected in any older home and is typically a buyer responsibility.
    • Cosmetic items, which are rarely worth raising in a luxury negotiation.

    Focusing on the first two categories keeps your requests credible and shows the seller you are being reasonable.

    Repairs versus credits versus price reductions

    There are three common ways to resolve findings. A seller can complete repairs before closing, issue a credit at settlement, or reduce the price. Each has trade-offs. Repairs give you a fixed outcome but depend on the quality of the contractor, which you may not control. Credits let you choose your own professionals and manage the work yourself, though lenders may have limits on how credits can be applied. A price reduction can affect the appraisal picture and carries tax and loan implications, so discuss it with your lender.

    For significant systems like roofs, chimneys, or structural work, many buyers prefer credits or price adjustments so they can hire specialists they trust. For small safety items, a seller repair with receipts can be efficient.

    Get specialist opinions before you negotiate

    A general inspector will often recommend a further evaluation by a specialist for items such as chimneys, sewer lines, stucco, or older electrical panels. Pursuing those opinions within your inspection window gives you real cost estimates to anchor your request. Negotiating with a written estimate is more persuasive than negotiating with a general complaint, and it prevents overpaying or underestimating a problem.

    How luxury and historic homes differ

    High-end and historic properties often have unusual systems, original materials, and features such as slate roofs, plaster walls, or older mechanical equipment. Some quirks come with the territory, and a seller may reasonably decline to repair items that reflect the age of a well-kept home. Your goal is to separate genuine defects from character and to price the real risk accurately.

    Keeping the deal healthy

    Tone matters. A concise, organized request with supporting documentation lands better than a long list of grievances. Prioritize a handful of meaningful items, explain your reasoning, and be prepared to compromise. In competitive situations where you waived contingencies or shortened timelines, your options may be narrower, which is why deciding your priorities before you make an offer pays off later.

    Documenting your findings

    Keep a written record of what you learn: the inspector’s report, specialist estimates, quotes you obtain, and the seller’s responses. If the negotiation changes the contract, make sure every agreement is captured in a signed addendum rather than a verbal understanding or a casual email. Clear documentation protects both parties and ensures that repairs or credits appear correctly at settlement.

    Also plan for a final walk-through before closing. Confirm that agreed repairs were completed, that receipts or permits are provided where appropriate, and that no new damage has occurred since the inspection.

    Timing and market conditions

    Your leverage depends on the market, the property, and how many other buyers are interested. In a balanced market, thoughtful requests are often well received. In a fast market, sellers may have alternatives, and an aggressive list can cost you the home. Your agent can help you calibrate requests to local conditions, and I am glad to discuss current activity in your target area.

    A note on appraisals and lender requirements

    If your loan requires repairs for safety or habitability, the lender may insist that specific items be completed before closing. Conventional and jumbo lenders each have their own standards, and an appraiser may flag visible defects such as peeling paint, roof wear, or missing handrails. Ask your loan officer early which findings could affect underwriting so you can build those items into your negotiation instead of discovering them days before settlement.

    Remember also that a repair completed by an unlicensed worker can create problems later. Ask for contractor names, licenses, insurance, and permits where required, and keep copies in your closing file.

    Frequently asked questions

    Can I ask the seller to fix everything in the inspection report?

    You can ask, but sellers rarely agree to every item. Prioritizing safety issues and major systems makes your requests more likely to be accepted.

    Are seller credits always allowed with my loan?

    Lenders can limit how much a seller may contribute and how credits are applied, so confirm the rules with your lender before negotiating.

    What if the seller refuses any repairs?

    Depending on your contract, you may be able to accept the home as is, negotiate further, or terminate within the contingency period. Review your options with your attorney before the deadline passes.

    Ready to talk? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for guidance tailored to your situation and current figures for your target area.

  • Concordville and Thornton, Pennsylvania: A Delaware County Guide for Luxury Home Buyers

    Concordville and Thornton, Pennsylvania: A Delaware County Guide for Luxury Home Buyers

    Concordville and Thornton sit in the quiet southwestern corner of Delaware County, where Concord Township meets Thornbury Township and the Chester County line. For luxury buyers who want mature trees, preserved open space, and a short drive to Wilmington, the Main Line, and Kennett Square, this pocket offers a different rhythm than the denser inner-ring suburbs. This guide explains what the area is like, what homes tend to look like, and what high-end buyers should weigh.

    Where Concordville and Thornton fit in the region

    Concordville is an unincorporated community within Concord Township, centered around Route 1 and Route 202, with Thornton just to the south and east along the Chester County border. The area sits between the Brandywine Valley to the west and the more suburban Glen Mills corridor to the east. Buyers often find it appealing precisely because it feels more rural than the Main Line while remaining close to major highways.

    Because this is a township-based market rather than a walkable downtown, the appeal is lifestyle driven: space, privacy, and access to open land. Buyers who need a train-station, sidewalk-to-restaurant lifestyle may prefer Media or Swarthmore instead.

    The housing stock

    Expect a mix of property types, which is typical of the larger-lot parts of Delaware County:

    • Converted farmhouses and stone homes with original fieldstone walls, often renovated and expanded over decades.
    • Custom and semi-custom executive homes on multi-acre parcels, frequently built in recent decades with open kitchens and finished lower levels.
    • Neighborhood developments with consistent lot sizes, shared amenities, and a more predictable resale profile.
    • Small estate and horse-friendly parcels toward the Chester County edge, where acreage and outbuildings matter as much as the house.

    Land, utilities, and what to verify

    On larger parcels, always confirm whether the property is served by public water and sewer or by a private well and on-lot septic system. These systems affect inspections, financing timelines, and long-term maintenance planning, so request records and schedule specialist inspections early. Older stone homes may also have mixed-era wiring, plumbing, and heating that deserve a thorough review.

    Acreage brings additional questions: where the boundaries actually run, whether there are easements for utilities or neighbors, and whether any portion is subject to preservation or conservation restrictions. A current survey and a careful title review are worth the time before you commit.

    Lifestyle and everyday convenience

    Daily errands in this part of the county are typically a short drive away, with shopping centers along Route 1 and a wide choice of restaurants in nearby Chadds Ford, Glen Mills, and West Chester. Cultural draws in the Brandywine Valley, including museums, gardens, and seasonal events, are close enough to be part of regular life rather than occasional outings.

    Commuters should test their actual routes at peak hours. Highway access is a strength, but the drive to Center City or into Delaware depends on traffic, so a real trial run beats a map estimate.

    Schools and school-district boundaries

    School assignment in this area is determined by the specific school district for the address, and boundaries can shift between neighboring townships over short distances. Verify the district and attendance zone for any property directly with the district rather than relying on a listing description. Families considering private or independent schools should weigh drive times, since many of the region’s well-known independent schools are reachable but not adjacent.

    Pricing and negotiation considerations

    Prices in a market defined by acreage and custom construction vary widely, and recent comparable sales may be limited. That makes it important to evaluate each property on its own merits: lot quality, condition of major systems, quality of renovations, and the buyer pool a home will appeal to when you eventually sell. I do not quote specific price figures here because they change; contact me for current activity in the area.

    Working with a local agent in a township market

    Township markets reward local knowledge. Properties can be reached by different school boundaries, municipal rules, and utility arrangements within a few miles, and listing descriptions do not always capture those differences. A local agent can help you compare homes across Concord, Thornbury, Birmingham, and nearby Chester County townships so you understand the trade-offs rather than relying on a single address.

    It also helps to think about how a home will perform when you sell. Features with broad appeal, such as flexible floor plans, quality kitchens, usable outdoor space, and a well-maintained roof and mechanical systems, tend to support resale more reliably than highly personalized finishes.

    Taxes, insurance, and ongoing costs

    Delaware County properties carry school, county, and municipal real estate taxes, and the combined burden depends on the specific district and assessed value. Estimate the full monthly cost of ownership, including taxes, insurance, utilities, landscaping, and maintenance of larger grounds. Properties with acreage, ponds, long driveways, or outbuildings can carry meaningful upkeep costs that are easy to underestimate during a first showing.

    Frequently asked questions

    Is Concordville part of Delaware County or Chester County?

    Concordville is in Concord Township, Delaware County, though it sits close to the Chester County line, which is why many buyers also compare it with nearby Chester County towns.

    Do homes in this area typically have well and septic?

    Some do, especially on larger parcels, while others connect to public water and sewer. Confirm the specific utilities for any address and schedule the appropriate inspections.

    Who is this area best suited for?

    Buyers who value space, privacy, and highway access to Wilmington, the Main Line, and Center City, and who are comfortable relying on a car for daily life.

    Ready to talk? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for guidance tailored to your situation and current figures for your target area.