Blog

  • Hospitals and Healthcare Access: What Luxury Buyers Should Know About Medical Proximity in Philadelphia and South Jersey

    Greater Philadelphia is one of the most medically rich regions in the country, anchored by academic medical centers, children’s hospitals, and specialty practices. For many luxury buyers, particularly those planning to stay in a home for decades or relocating from out of state, proximity to quality care is a quiet but powerful factor in choosing a location.

    Why healthcare access influences home choice

    Buyers consider medical access for different reasons: a household with young children wants strong pediatric care nearby, empty nesters weigh future needs, and executives who travel value predictable access to specialists. Unlike many amenities, healthcare access rarely shows up in listing photos, so buyers need to research it deliberately.

    Center City and University City

    Living in or near Center City, Rittenhouse, Washington Square West, or University City places residents close to several major academic hospitals and a dense concentration of specialists. Many city residents can reach appointments on foot or with a short ride, which is a real lifestyle advantage for buyers who prefer not to depend on driving.

    The Main Line and western suburbs

    Main Line communities offer a mix of hospital campuses and outpatient centers, and residents can reach Center City facilities by car or regional rail. When touring in Wayne, Bryn Mawr, Villanova, or Ardmore, map the drive times to the hospitals and practices you would actually use, at the times of day you would travel.

    South Jersey

    Communities such as Haddonfield, Moorestown, Cherry Hill, and Voorhees are served by regional hospitals and specialty groups on the New Jersey side, and many residents also use Philadelphia institutions via the bridges. Check whether your insurance network includes the facilities you prefer, since networks can differ across state lines.

    Practical steps for buyers

    • List the specialties and hospitals that matter most to your household.
    • Test real drive times from a candidate address at rush hour.
    • Confirm your health insurance network before you decide.
    • Consider future needs, such as single-level living and a first-floor bedroom suite.
    • Ask your agent about proximity to urgent care and emergency services, not only flagship hospitals.

    Shore and second-home considerations

    If you are buying at the Jersey Shore, remember that off-season access to care can be more limited than in the inland suburbs, and summer traffic can lengthen travel times. Second-home buyers should identify the nearest emergency facility and understand how far specialty care sits from the property.

    What this means for resale

    Healthcare proximity tends to support long-term demand, especially among downsizers and relocating professionals. While no single factor guarantees value, locations that combine access to care with good schools, transit, and amenities usually appeal to a broad pool of future buyers.

    Building a healthcare-informed search

    Start by identifying the care relationships you already have and the ones you expect to need. Primary care, pediatrics, cardiology, orthopedics, oncology, and maternity services are all common considerations, and the best nearby option may vary by specialty. Create a simple map of the hospitals and clinics you would use, then overlay it with the neighborhoods on your shortlist. Looking at both normal-day and rush-hour drive times will give a more realistic picture than a straight-line distance.

    Home features that support health and independence

    Healthcare thinking also shapes what buyers look for inside the house. Features such as a first-floor primary suite, wide doorways, a zero-step entry, a flexible room that could become a caregiver suite, and space for a home office or wellness area can all support long-term living. Carriage houses and guest suites can also accommodate visiting family or live-in help. Considering these items now can help you avoid costly renovations later.

    Planning for the long term

    Some buyers decide that a Center City condominium with concierge service and walkable medical access is the best long-term fit, while others prefer a suburban home with a level lot and room for family. There is no single right answer; what matters is aligning the home, the location, and the care you expect to need. Your agent can help you compare options across Philadelphia, the Main Line, and South Jersey so that your decision reflects both lifestyle and practicality.

    Questions to ask during tours and showings

    When you visit a candidate home or neighborhood, ask the agent which hospitals and urgent-care centers residents typically use, how traffic behaves at different hours, and whether seasonal events or construction affect access. Neighbors are often a valuable source of local knowledge. If you or a family member has an ongoing medical relationship, schedule a test drive to that practice from the property during a realistic appointment time. These small steps turn an abstract concern into practical, address-specific information and help you choose a home with confidence.

    Frequently asked questions

    Which area has the best hospital access?

    Center City and University City offer the densest concentration of academic hospitals and specialists, but suburban and South Jersey locations also have strong options. The best choice depends on your needs and commute.

    Does insurance network matter when choosing where to live?

    Yes. Confirm that the hospitals and physicians you prefer are in your network, especially if you are crossing between Pennsylvania and New Jersey.

    Does medical proximity affect home values?

    It can support demand, particularly among older and relocating buyers, but it is one factor among many. Your agent can help you weigh it alongside others.

    Ready to talk through your options? Contact James Kennedy, luxury real estate advisor serving Philadelphia and South Jersey, at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation and current market figures.
  • Seller Financing and Purchase-Money Mortgages: How Private Financing Works in Luxury Real Estate in Pennsylvania and New Jersey

    Seller Financing and Purchase-Money Mortgages: How Private Financing Works in Luxury Real Estate in Pennsylvania and New Jersey

    Most luxury home purchases are financed through banks or paid for in cash, but a third path exists: the seller acts as the lender. Seller financing, usually documented as a purchase-money mortgage, can make sense for unusual properties, self-employed buyers, or sellers who want steady income and tax flexibility. It is also easy to get wrong, so understanding the mechanics before you propose it is essential.

    What seller financing actually is

    In a seller-financed deal, the buyer makes a down payment to the seller and signs a promissory note for the remaining balance. The note is secured by a mortgage recorded against the property, so if the buyer defaults, the seller has a legal path to recover the home. Terms, including interest rate, payment schedule, and any balloon payment, are negotiated between the parties rather than set by a bank.

    When it can make sense

    • A distinctive estate, equestrian property, or land parcel that conventional appraisers and lenders find hard to evaluate.
    • A buyer with substantial wealth but irregular income that traditional underwriting struggles to document.
    • A seller who owns the property free and clear and prefers an income stream to a lump sum.
    • A transaction where speed or flexibility matters more than the lowest possible rate.

    Risks for the seller

    The seller carries credit risk. If the buyer stops paying, recovering the property can involve a lengthy and costly legal process, and the home may return in worse condition. Sellers should verify the buyer’s finances thoroughly, require a meaningful down payment, insist on proof of homeowner’s insurance naming them as a protected party, and keep property taxes current through escrow or documented payments. If the seller still has an existing mortgage, a due-on-sale clause may prevent this approach entirely without lender consent.

    Risks for the buyer

    Buyers should expect rates that are often higher than prevailing bank rates, and balloon payments that require refinancing or payoff on a set date. If market conditions or credit change before the balloon comes due, refinancing may be harder than anticipated. Buyers also need to confirm clear title, a proper recorded mortgage, and written terms for what happens if a payment is late.

    Legal and tax considerations

    Both Pennsylvania and New Jersey have rules that affect lending disclosures, recording, and consumer protections, and federal rules can apply depending on how often a seller provides financing. Sellers may be able to spread capital gains over time through installment treatment, but the tax outcome depends on individual facts. This is not an area for do-it-yourself paperwork: each party should have a real estate attorney and a tax advisor review the structure.

    Alternatives to consider

    Depending on the situation, a bridge loan, portfolio loan, or an assumable mortgage may achieve similar goals with less risk. A knowledgeable agent can help compare the options and bring the right professionals to the table.

    How to structure the deal responsibly

    If you decide to explore private financing, begin with the end in mind. Agree on the purchase price, down payment, interest rate, amortization schedule, and term, and decide in advance how late payments, prepayment, and default will be handled. A clear written plan prevents disputes later and makes it easier for attorneys to draft clean documents. Many sellers also ask for a personal guarantee or additional collateral when the buyer is purchasing through an LLC or trust, which is common among higher-net-worth buyers.

    Title, insurance, and servicing

    Even in a private deal, a title search and owner’s title insurance remain wise investments, because they protect against defects that could undermine the mortgage or the buyer’s ownership. Insurance should name the seller as mortgagee so that proceeds protect the loan after a loss. Some parties hire a professional loan servicer to collect payments, track escrow, and send annual statements, which keeps the relationship businesslike and creates a clear payment record.

    Exit planning

    Every seller-financed deal should have a defined ending. Buyers should plan how they will refinance or pay off a balloon, and sellers should understand what they will do if payoff is delayed. Talking through these scenarios at the start is far easier than negotiating them under pressure. A thoughtful advisor team, including an attorney, accountant, and an experienced agent, can model the numbers and help both sides decide whether the structure truly serves their goals.

    Questions to ask before you propose it

    Buyers should ask whether the seller owns the property free and clear, whether any existing lender must consent, and how the seller will respond if a payment is missed. Sellers should ask how the buyer’s liquidity, credit history, and other obligations look, and whether the buyer has the means to refinance at maturity. Both sides should consider how property taxes, insurance, and major repairs will be allocated during the term. Treating the arrangement as a serious lending relationship, not a casual favor, protects everyone and keeps the transaction on solid footing.

    Frequently asked questions

    Is seller financing common in luxury real estate?

    It is not the norm, but it appears periodically for unusual properties or special circumstances. Most luxury buyers still use jumbo loans or cash.

    Does the buyer still need a down payment?

    Yes. Sellers typically require a substantial down payment to protect themselves, and the amount is a negotiated term.

    Who should draft the documents?

    Real estate attorneys for both sides should draft and review the note, mortgage, and related agreements. Standard purchase agreement forms alone are not sufficient.

    Ready to talk through your options? Contact James Kennedy, luxury real estate advisor serving Philadelphia and South Jersey, at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation and current market figures.
  • Royersford, Spring City, and Limerick, Pennsylvania: A Upper Montgomery and Chester County Guide for Luxury Home Buyers

    Royersford, Spring City, and Limerick, Pennsylvania: A Upper Montgomery and Chester County Guide for Luxury Home Buyers

    Where Montgomery and Chester counties meet along the Schuylkill River, Royersford, Spring City, and Limerick Township offer something many luxury buyers struggle to find closer to the city: space, newer construction, and river-town character at the same time. These communities sit beyond the traditional Main Line, which is precisely why buyers who want land, privacy, and a more relaxed pace increasingly look here.

    Three communities, three different personalities

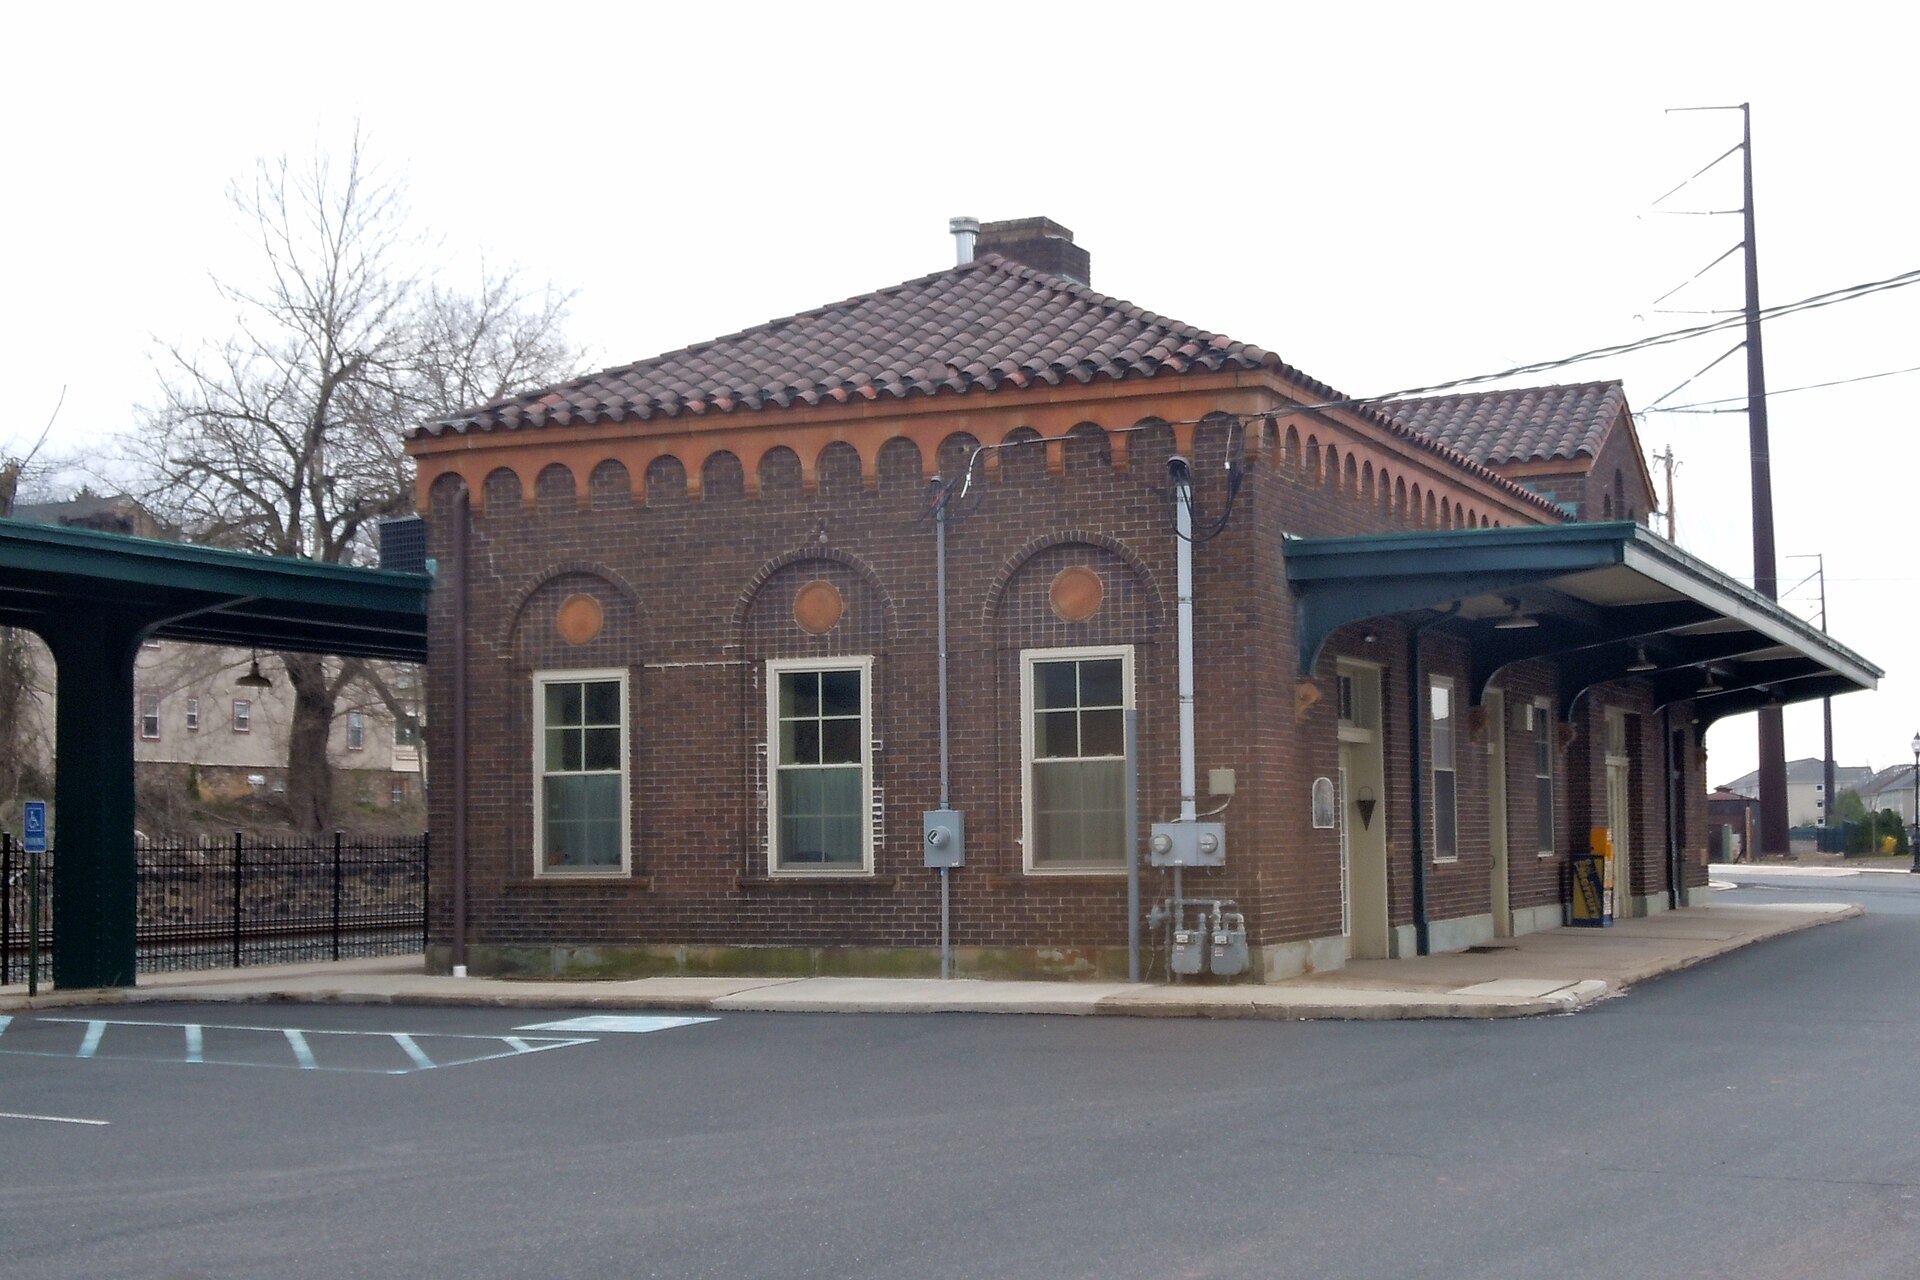
    Royersford and Spring City are river boroughs with walkable main streets, brick and stone twins, and Victorian homes that reward careful restoration. Limerick Township, by contrast, is largely suburban and rural in feel, with newer subdivisions, executive homes on larger lots, and open space that appeals to buyers who prioritize yard and privacy over walkability.

    Because the three communities are so different, a productive search starts by deciding which lifestyle matters most: a restored borough home within walking distance of local restaurants and the river trail, or a newer estate-style home with a three-car garage and room for a pool.

    What luxury buyers typically find

    • Newer executive homes in Limerick with open floor plans, finished lower levels, and modern mechanical systems.
    • Restored Victorian and early-twentieth-century homes in Spring City’s historic district, where period details are a major draw.
    • Custom and semi-custom homes on multi-acre lots along the edges of the townships.
    • Occasional converted or adaptive-reuse properties tied to the area’s industrial history.

    Inventory at the very top of the price range is thinner here than in the Main Line or Center City, so patience and a clear brief matter. Buyers who hire an agent to monitor new and off-market opportunities often see properties before they are widely advertised.

    Commuting and connectivity

    Residents typically reach Philadelphia, King of Prussia, Malvern, and the Route 422 corridor by car, and the region’s major employers in pharmaceuticals, technology, and healthcare sit within a reasonable drive. Test your actual commute at the hours you would travel before you fall in love with a house, because the Route 422 corridor can be congested at peak times.

    Historic districts and renovation rules

    Spring City in particular has a nationally recognized historic character, and a home inside a designated district can come with review requirements for exterior changes. If you plan to replace windows, add a porch, or alter a facade, confirm what approvals apply before you commit. Older homes also warrant specialized inspections for roofing, chimneys, wiring, and moisture.

    Schools, recreation, and everyday life

    School districts in this area differ by township, so verify the assigned district for any specific address directly with the district rather than relying on a listing. Outdoor amenities, including the Schuylkill River Trail, nearby parks, and regional golf, are a significant part of the appeal for active households.

    Tips for buyers and sellers

    • Buyers: walk the neighborhood on a weekday evening and a weekend morning to feel its rhythm.
    • Buyers: ask about flood-plain status for any home near the river or its tributaries.
    • Sellers: emphasize land, privacy, and lifestyle in marketing, since these homes compete on different strengths than Main Line properties.
    • Sellers: price against truly comparable homes, not just those in the same zip code.

    Market positioning and value

    Compared with the Main Line, the Schuylkill River towns generally offer more house and land for the same budget, which is the core of their appeal. That does not mean they are uniformly cheaper; well-restored borough homes and well-sited custom properties can command strong prices because comparable inventory is scarce. Rather than relying on general impressions, ask for a comparative analysis built on recent, truly similar sales, and be cautious about relying on automated estimates, which often struggle with unique homes.

    Taxes, utilities, and ownership costs

    Property tax rates differ across municipalities and school districts, and reassessments can change the picture over time. Before you make an offer, ask about the current tax bill, and then discuss with your agent and lender how it might change after a sale. Homes on larger lots may rely on private wells or septic systems, which call for dedicated inspections and testing. Heating fuel, generator capacity, and driveway maintenance are also real costs on larger properties, and they are worth budgeting for alongside the mortgage.

    Making your search efficient

    Because these communities are spread out, a focused search saves time. Define your must-haves, such as acreage, a first-floor primary suite, a home office, or walkability, and tour a small number of strong candidates in a single day. Buyers coming from the city often underestimate how much outdoor maintenance a larger property requires, so plan for landscaping, snow removal, and seasonal upkeep. Sellers in these areas benefit from professional photography that captures land and setting, since a home’s surroundings are a large part of its value.

    Frequently asked questions

    Is Royersford or Spring City better for luxury buyers?

    It depends on your priorities. Royersford offers a larger main-street scene and easier access to commercial amenities, while Spring City offers a quieter, more historic setting. Many buyers tour both before deciding.

    Do these towns have newer luxury construction?

    Yes. Limerick Township and surrounding areas include newer executive homes and some custom builds, though the highest-end inventory is limited and can be tight.

    Should I check flood risk near the Schuylkill River?

    Yes. Review FEMA flood maps and ask your insurance agent for a quote early, since flood coverage can affect both monthly costs and lender requirements.

    Ready to talk through your options? Contact James Kennedy, luxury real estate advisor serving Philadelphia and South Jersey, at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation and current market figures.
  • The Final Walk-Through: A Luxury Buyer’s Checklist Before Settlement in Pennsylvania and New Jersey

    The final walk-through is the last opportunity to confirm that the home you are about to purchase is in the condition you agreed to buy. In a luxury transaction, where finishes, systems, and custom features carry significant value, this short visit deserves careful preparation. It is not a second inspection, but it is your chance to catch problems while you still have leverage.

    Here is how to approach the final walk-through when buying in Philadelphia or South Jersey, what to check, and what to do if something is wrong.

    When the Walk-Through Happens and What It Is For

    The walk-through typically occurs within a day or two of settlement, sometimes the morning of closing. Its purpose is to confirm that the property is in substantially the same condition as when you signed the agreement, that any negotiated repairs were completed, and that items included in the sale remain. The exact terms depend on your agreement of sale, so review it with your agent and attorney beforehand.

    Bring a Checklist

    Systems and utilities

    • Run the heating and cooling, and confirm each zone responds
    • Test hot water at multiple fixtures and flush toilets
    • Run the dishwasher, disposal, oven, cooktop, and other appliances that convey
    • Check garage doors, openers, gates, and security or smart-home components

    Condition of the home

    • Look for new water stains on ceilings, walls, and around windows
    • Open and close windows and doors, and test locks and keys
    • Inspect floors, walls, and finishes for damage from the seller’s move
    • Confirm that fixtures, window treatments, and other included items remain

    Negotiated repairs

    • Bring the repair addendum and any receipts or contractor invoices. Verify that work was completed, look at the quality, and ask for permits or warranties where relevant.

    Special Considerations for Luxury Homes

    Larger homes have more to verify. Allow extra time for outbuildings, pool equipment, irrigation, generators, wine storage, elevators, and any custom lighting or audio systems. Ask the seller to provide manuals, remote controls, access codes, and service contacts. If a pool is open or seasonal, confirm whether the equipment has been properly opened or winterized.

    For new construction, the walk-through often overlaps with the builder’s punch-list process. Document every item in writing and agree on a completion schedule and, where appropriate, a holdback or escrow for unfinished work.

    What If You Find a Problem?

    Raise the issue immediately with your agent and attorney, and photograph it. Depending on the problem and your agreement, options may include having the seller correct it before closing, agreeing to a credit at settlement, holding funds in escrow until the work is finished, or, for serious issues, delaying the closing. Put any agreement in writing, signed by all parties, so that the resolution is documented and enforceable. Your attorney or settlement agent can help structure a credit or escrow holdback properly, and your lender must typically be informed of any changes to the price or terms before closing. In a luxury transaction, where repairs can involve specialty trades and longer lead times, an escrow holdback tied to a clear completion deadline is often more practical than a rushed fix. Avoid assuming something will be sorted out after you take possession, since your leverage generally decreases once the transaction is complete.

    Before You Arrive: Preparation That Pays Off

    Request a copy of your inspection report, the repair addendum, and the list of included items a few days ahead. Ask your agent to confirm that the seller has moved out and that utilities remain on so that you can test everything. If major work was done, such as a new roof, electrical upgrades, or a renovated kitchen, ask for the contractor’s name, invoices, permits, and warranties.

    In Philadelphia, rowhomes and older city properties may involve party walls, basements, and roof decks that deserve special attention. In South Jersey, pay attention to crawl spaces, sump pumps, and grading, particularly after heavy rain. Shore homes call for checks on bulkheads, outdoor showers, and flood-related features.

    Documents to gather at settlement

    • Keys, garage remotes, gate codes, and alarm information
    • Manuals and warranties for appliances and systems
    • Contact information for service providers who maintain the pool, landscaping, or HVAC
    • Any association documents, move-in rules, or elevator reservation requirements

    Treat the walk-through as part of your due diligence rather than a formality. A focused, unhurried visit can save thousands of dollars and many weeks of frustration after you move in.

    Tips for a Smooth Walk-Through

    • Schedule it for daylight hours so you can see the exterior and interior clearly
    • Bring your phone to photograph conditions and a charger to test outlets
    • Take your time, even if the closing schedule feels tight
    • Keep your inspection report with you for reference

    Frequently asked questions

    Is the final walk-through the same as a home inspection?

    No. The inspection occurs earlier and evaluates the home’s overall condition. The walk-through is a final check that the property is as agreed and that negotiated repairs are finished.

    How long should a luxury home walk-through take?

    Plan for at least an hour, and longer for large estates or properties with extensive systems and outbuildings.

    Can I refuse to close if something is wrong?

    This depends on your agreement of sale and the nature of the issue. Speak with your agent and real estate attorney right away so that you understand your rights and options before settlement.

    Ready to talk about your plans? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation about luxury real estate in Philadelphia and South Jersey.

  • Mortgage Pre-Approval for Luxury Buyers: Documents, Proof of Funds, and How to Strengthen Your Offer

    In a competitive luxury market, an offer is only as strong as the buyer behind it. Sellers and their agents evaluate not just the price on the page but the likelihood that you will actually close. A well-prepared financing package can be the difference between winning a home in Rittenhouse, Haddonfield, or on the Main Line and watching it go to another buyer at a lower price.

    This guide walks through how pre-approval works for higher-priced purchases, the documents lenders typically request, and how to present your strength to sellers in Pennsylvania and New Jersey.

    Pre-Qualification vs. Pre-Approval

    Pre-qualification is a quick estimate based on information you provide, and it generally carries little weight with a seller. A true pre-approval involves a lender verifying your income, assets, credit, and debts, and issuing a letter that states a loan amount and program. For luxury purchases, sellers expect a full pre-approval from a recognized lender, and many agents will ask to speak with your loan officer before advising a client to compete.

    Documents Luxury Buyers Should Expect to Provide

    Larger loans and more complex finances usually mean more documentation. Common requests include:

    • Recent pay records, W-2s, and tax returns, typically for the past two years
    • Business tax returns, profit-and-loss statements, and K-1s for self-employed buyers and business owners
    • Statements for checking, savings, brokerage, and retirement accounts, usually covering the most recent two to three months
    • Documentation of the source of any large deposits
    • Gift letters if family members are contributing to the purchase
    • Information on other real estate you own, including mortgages, leases, and taxes

    Starting this gathering process early prevents surprises. Large unexplained transfers between accounts are a common cause of delay, so keep your paper trail clean before you apply.

    Proof of Funds and Asset Verification

    For buyers using substantial down payments or paying cash, a proof-of-funds letter or recent account statements may accompany the offer. When assets are held in investment accounts, ask your lender how they will count them, since lenders often apply their own valuation rules to stocks, bonds, and retirement funds.

    Buyers who plan to sell a current home to fund the next one should discuss bridge financing, home sale contingencies, or other solutions with their lender before writing an offer, because these choices affect how sellers view the proposal.

    Making Your Offer Stronger

    • Fully underwritten pre-approval: some lenders offer a verified approval in which underwriting is largely complete before you make an offer, which reduces the risk of last-minute issues.
    • Realistic appraisal planning: unique luxury homes can be difficult to appraise. Discuss how you would handle a shortfall before you submit your offer.
    • Flexible timing: a closing date that fits the seller’s plans can matter as much as a small price difference.
    • Responsive team: a loan officer, attorney, and agent who return calls quickly signal reliability.

    Avoiding Mistakes During the Loan Process

    Once you are pre-approved, avoid opening new credit lines, financing furniture, changing jobs, or moving large sums without speaking to your lender. Lenders typically re-verify credit and employment shortly before closing, and changes can jeopardize approval. Also remember that a pre-approval is not a final commitment; it depends on the property, appraisal, and title meeting the lender’s requirements.

    Pennsylvania and New Jersey Considerations

    In Pennsylvania, buyers commonly sign an agreement of sale with a financing contingency that gives a set period to secure a mortgage commitment. In New Jersey, the attorney review period gives both sides a short window after signing to have counsel review the contract. In either state, coordinating your lender, attorney, and agent early helps you meet deadlines and avoid unnecessary stress.

    Property type matters too. Condominiums and co-ops may require additional lender review of the building’s finances, reserves, and owner-occupancy ratios, which can add time. Historic and unique homes can raise appraisal questions, and homes with wells, septic systems, or older mechanical systems may require specialized inspections that interact with your loan terms.

    A practical timeline

    • Several weeks before touring: speak with two or three lenders and compare programs, pricing, and service
    • Before your first showing: obtain your pre-approval letter and confirm the amount fits your comfort level, not just the maximum
    • At offer: have your lender ready to speak with the listing agent if asked
    • Under contract: lock your rate when advised, order the appraisal, and deliver documents promptly

    A pre-approval amount is a ceiling, not a target. Consider your overall financial picture, including taxes, insurance, reserves, and planned renovations, when deciding how much to borrow.

    Frequently asked questions

    How early should I get pre-approved before shopping for a luxury home?

    Ideally before you begin touring seriously. Lenders can take days to weeks to review complex finances, and having an approval in hand lets you move quickly when the right home appears.

    Does pre-approval lock my interest rate?

    No. Pre-approval confirms how much a lender is willing to lend under stated conditions. A rate lock is a separate step, usually taken once you are under contract, and your lender can explain the available options.

    Can self-employed buyers get pre-approved for a luxury purchase?

    Yes, though lenders usually require more documentation, such as multiple years of business and personal returns. Some buyers also explore alternative programs, and a lender experienced in high-balance loans can advise on the best fit.

    Ready to talk about your plans? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation about luxury real estate in Philadelphia and South Jersey.

  • Lower Providence, Eagleville, and Audubon, Pennsylvania: A Montgomery County Guide for Luxury Home Buyers

    Lower Providence, Eagleville, and Audubon, Pennsylvania: A Montgomery County Guide for Luxury Home Buyers

    Lower Providence Township sits in the heart of Montgomery County, tucked between the Schuylkill River and the Perkiomen Creek, within a short drive of Valley Forge, Collegeville, and the King of Prussia corridor. For luxury and move-up buyers, the communities of Eagleville, Audubon, and the surrounding township offer a combination that is increasingly hard to find: larger lots, newer and well-maintained construction, strong highway access, and a quieter pace than the Main Line.

    This guide explains how to think about the area, what types of homes you are likely to find, and the practical questions that matter when you are buying or selling here.

    Where Lower Providence Fits in the Regional Picture

    The township is anchored by Route 422 and Route 363, which makes commutes to Center City, King of Prussia, Conshohocken, Collegeville, and the Wayne and Malvern business corridors manageable by car. Rail access is not as direct as in many Main Line towns, so buyers who commute to Center City by train should map their route carefully before committing.

    Open space is a defining feature. Valley Forge National Historical Park, the Schuylkill River Trail, and the Perkiomen Trail give residents miles of walking, running, and cycling without leaving the neighborhood. Buyers who value outdoor life as part of daily routine often rank this area highly for that reason alone.

    Home Styles and Property Types

    Executive colonials and traditional estates

    Much of the township’s higher-end inventory is made up of traditional colonial and Georgian-inspired homes on half-acre to multi-acre lots, many built from the 1980s onward and updated since. Expect generous primary suites, finished lower levels, three-car garages, and rear yards with room for a pool.

    Newer enclaves and custom homes

    Smaller newer developments and occasional teardown or custom builds appeal to buyers who want modern open layouts, higher ceilings, and current mechanical systems without taking on a renovation. When comparing, look closely at the builder, the lot, and how the home sits relative to neighbors.

    Historic and rural-feeling properties

    Near the creek and river corridors you will sometimes find older stone farmhouses and character homes. These carry the usual considerations of older properties, including well and septic questions, floodplain proximity, and renovation history.

    What Luxury Buyers Should Evaluate

    • Flood and creek proximity: parts of the township lie near the Schuylkill and Perkiomen. Ask for the FEMA flood zone determination and any insurance history on the specific parcel.
    • School district boundaries: the township is served by the Methacton School District. Confirm assignment for any specific address directly with the district rather than relying on a listing description.
    • Traffic and noise: visit at rush hour and on a weekend. Proximity to 422 and 363 can be an asset for convenience and a drawback for sound.
    • Taxes: Pennsylvania school and municipal taxes vary by municipality. Review the actual tax bill and consider how a reassessment could affect it.

    Selling a Luxury Home in Lower Providence

    Sellers in this market benefit from emphasizing what buyers cannot easily replicate: lot privacy, trail access, commute convenience, and well-kept systems. Professional photography, twilight exteriors, and a clear story about recent capital improvements such as roofs, HVAC, and kitchens help a listing stand apart.

    Pricing should rest on carefully selected comparable sales that reflect lot size, finish level, and condition rather than a simple per-square-foot average. A pre-listing walkthrough with an experienced agent can identify inexpensive fixes that protect your negotiating position.

    Lifestyle and Everyday Conveniences

    Daily life here tends to revolve around the car, which is typical of Montgomery County’s suburban townships. Shopping and dining are close at hand in Collegeville, Phoenixville, King of Prussia, and along the 422 corridor, while the Perkiomen Trail and Valley Forge offer recreation just minutes from home. Buyers who want a walkable village center should compare this area with nearby borough-style towns, and those who prioritize space and privacy often find the trade-off worthwhile.

    Healthcare, corporate employers, and higher education institutions in the surrounding region add to the area’s stability as an executive housing market. When touring, spend time at the grocery store, on the trails, and on the roads you would use each day, because the feel of a neighborhood is often what separates two otherwise similar houses.

    Questions to ask before making an offer

    • How old are the roof, HVAC systems, and water heaters, and have they been serviced?
    • Are there easements, drainage swales, or utility corridors on the lot?
    • Is the property on public sewer and water, and what are the annual costs?
    • What have comparable homes with similar lots and finishes sold for recently?

    Frequently asked questions

    Is Lower Providence considered a luxury market?

    It is a strong move-up and executive market with pockets of luxury homes on larger lots and in newer enclaves. Buyers seeking the highest price tiers in the region often compare it with the Main Line and Chester County, while valuing its relative space and convenience.

    What are the main attractions for buyers?

    Convenient highway access, proximity to Valley Forge and the regional trail network, larger lots than many closer-in suburbs, and a wide range of well-maintained single-family homes.

    How should I check flood risk on a home near the creek or river?

    Ask your agent for the flood zone determination, request any prior flood or insurance claim disclosures, and obtain an insurance quote before you finish your inspection period.

    Ready to talk about your plans? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation about luxury real estate in Philadelphia and South Jersey.

  • Resale Certificates and Association Documents: What Luxury Condo and HOA Buyers Should Review in Pennsylvania and New Jersey

    Resale Certificates and Association Documents: What Luxury Condo and HOA Buyers Should Review in Pennsylvania and New Jersey

    When you buy a condominium, townhome, or home in a planned community, you are buying into an association as well as a property. In both Pennsylvania and New Jersey, the documents that describe that association are a central part of the purchase. Understanding what to request, what to read, and what to question can protect a luxury buyer from expensive surprises.

    Why association documents matter

    The association’s financial health, rules, and obligations directly affect your monthly costs, your freedom to renovate, and your eventual resale. A beautiful unit in a poorly managed building can be a difficult asset to own and to sell.

    Pennsylvania resale certificates

    In Pennsylvania, sellers in condominiums and planned communities are generally required to provide a resale certificate and related governing documents to the buyer. These typically include information on regular assessments, any unpaid assessments, capital expenditures planned, and the status of reserves. Pennsylvania law gives buyers a limited statutory window to cancel after receiving these documents, so the timing of delivery matters. Ask your attorney or agent to confirm the current rules and deadlines.

    New Jersey practices

    In New Jersey, buyers typically obtain documents such as the master deed, bylaws, rules and regulations, budgets, and financial statements through the seller or the association’s management. Attorney review under the contract gives buyers an important opportunity to examine these materials before the contract becomes final. Because practices vary, make the request early.

    What to read first

    • Budget and financial statements: Look at income, expenses, delinquencies, and trends over several years.
    • Reserve study: A thoughtful reserve plan suggests a building prepared for roof, facade, and elevator work.
    • Meeting minutes: Minutes often reveal disputes, planned projects, or deferred maintenance long before they show up in a budget.
    • Litigation disclosures: Pending legal matters can affect financing and insurance.
    • Insurance coverage: Understand what the master policy covers and what you need to insure yourself.

    Rules that affect daily life

    Review restrictions on rentals, pets, renovations, parking, signage, and exterior changes. High-end buyers often plan significant interior work, so find out about approval procedures, contractor insurance requirements, work-hour limits, and elevator use rules before you commit.

    Fees and what they include

    Confirm what the monthly fee covers, such as utilities, staff, amenities, and exterior maintenance, and ask about any capital contributions or transfer fees due at settlement. Fees that look comparable between buildings may cover very different services.

    Financing and lender requirements

    Lenders scrutinize associations for owner-occupancy ratios, delinquency rates, and pending litigation. A building that does not meet standards can limit buyers to cash or portfolio loans, which narrows your future resale market.

    Red flags to raise

    Warning signs include sharply rising fees, thin reserves, frequent special assessments, a high number of delinquent owners, and a pattern of deferred maintenance. None is automatically disqualifying, but each deserves a clear answer and, where appropriate, a negotiation.

    How the documents affect resale

    The same documents that protect you as a buyer will be requested by your own future buyer. Buildings with healthy reserves, clear rules, and well-kept records tend to sell more smoothly, and lenders are more comfortable approving loans for them. When comparing two similar units, favor the one whose association has a track record of planning ahead for major projects rather than relying on emergency assessments.

    Working with your attorney and agent

    Your agent can help you request the right documents early and compare buildings against one another. Your attorney can interpret the legal provisions, including how assessments are enforced, what liens an association can place, and what happens to unpaid dues at settlement. In a luxury purchase, the cost of that review is small relative to the value at stake.

    A practical review checklist

    Gather the declaration or master deed, bylaws, rules, current budget, last two to three years of financial statements, the reserve study, recent meeting minutes, insurance certificates, and any notices of upcoming assessments. Read them with a highlighter, list your questions, and bring them to your agent and attorney before your contingency or review period expires.

    Special considerations for luxury buyers

    At the higher end, buyers often combine units, add private storage, or plan major renovations, all of which are governed by association rules and sometimes by board approval. Ask about precedent: has the association approved similar projects before, and under what conditions? A building that welcomes thoughtful improvements can add real value, while one that resists change may limit what you can do with the space you are buying.

    Frequently asked questions

    How long do I have to review association documents?

    The timeframe depends on the state and contract. In Pennsylvania there is a statutory cancellation window tied to receiving the resale certificate, so confirm the current rule with your attorney. In New Jersey, review typically happens during the attorney review period and any contract contingencies.

    Who pays for the resale certificate?

    Fees for preparing association documents are commonly paid by the seller or are allocated under the contract, but practice and local rules vary. Check the agreement of sale and ask early.

    Can I negotiate if I find problems in the documents?

    Yes. Concerns about reserves, pending assessments, or litigation can support a price adjustment, a seller credit, or in some cases a decision to walk away within your contractual rights.

    Ready to talk through your plans? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation about luxury real estate in Philadelphia and South Jersey.

  • Construction-to-Permanent Loans: How to Finance a Custom Luxury Home Build in Greater Philadelphia and South Jersey

    Construction-to-Permanent Loans: How to Finance a Custom Luxury Home Build in Greater Philadelphia and South Jersey

    Building a custom luxury home usually means financing in two phases: paying for construction as it happens, then settling into a long-term mortgage. A construction-to-permanent loan, sometimes called a one-time-close loan, combines both into a single transaction. For buyers of land and custom homes in Chester County, Bucks County, Montgomery County, and South Jersey, understanding how these loans work can prevent costly surprises.

    How a construction-to-permanent loan works

    During construction, the lender releases funds in stages, known as draws, as work is completed and inspected. Borrowers typically pay interest only on the amount drawn. When construction ends and a certificate of occupancy is issued, the loan converts to a standard permanent mortgage, often without a second closing. That single closing can save fees and remove the risk of being unable to qualify later.

    Construction-only versus one-time-close

    A construction-only loan is short term and must be paid off or refinanced when the home is complete. This offers flexibility, such as shopping for the best permanent rate later, but it means qualifying twice and carrying market risk between the two. A one-time-close loan offers certainty, though the rate structure and any lock or float-down features should be reviewed carefully.

    What lenders look for

    • Strong credit and reserves: Lenders usually want to see liquidity to cover overruns and delays.
    • A qualified builder: Many lenders vet the builder’s licensing, financial condition, and track record.
    • Detailed plans and budget: Plans, specifications, and a line-item cost breakdown are generally required.
    • An appraisal based on plans: The home is appraised on its projected completed value, which can be difficult for unique properties with few comparable sales.

    The land question

    If you already own the lot, its value can often count toward your equity contribution. If you are buying the land at the same time, the land purchase may be folded into the loan. Raw land with no utilities, or land requiring a well and septic system, can complicate underwriting, so confirm early what a lender will accept.

    Budgeting for the unexpected

    Luxury custom builds are prone to change orders, material price swings, and weather delays. Prudent buyers set a contingency reserve, commonly discussed as a meaningful percentage of the construction budget, and keep it separate from the draw schedule. Ask your lender how change orders are handled and whether additional funds can be drawn if the budget grows.

    Permits, inspections, and local approvals

    Municipal approvals in the Philadelphia region and South Jersey vary by township. Zoning, setbacks, stormwater requirements, and environmental review can all affect timing. Interest accrues while you wait, so a realistic timeline is part of a realistic budget.

    Jumbo considerations

    Most luxury construction loans exceed conforming limits, so they behave like jumbo loans, with tighter underwriting, larger down payment expectations, and rate structures that differ from conventional loans. Some lenders offer portfolio programs, which are especially helpful for unique homes.

    Protecting yourself

    Use a written construction contract with a clear scope, schedule, and payment terms. Confirm the builder carries appropriate insurance, and consider having an independent professional review draw requests against actual progress. A real estate attorney can review both the loan documents and the contract.

    Comparing lenders and programs

    Not every lender offers construction financing, and those that do structure it differently. Ask about the rate during construction versus after conversion, the length of the construction period, extension fees if the build runs long, and whether interest-only payments apply during the build. Local banks and credit unions with in-house underwriting sometimes show more flexibility on unusual homes than large national lenders, while national lenders may offer more rate and lock options. Collect written quotes from several lenders and compare total costs, not just the headline rate.

    The draw process in practice

    Before each draw, an inspector typically verifies that the work being billed has been completed. Builders often need to front costs until the draw is released, so make sure your builder is comfortable with the schedule. Keep lien waivers current, because unpaid subcontractors can file liens that cloud your title. Your title company and attorney can explain how holdbacks and final payments work in your state.

    After the build

    Once the home passes final inspection and a certificate of occupancy is issued, the loan converts. Confirm in advance what documents the lender will require, such as a final appraisal, proof of insurance, and a final survey. Plan for landscaping, driveways, and finishing work that may fall outside the original budget, and keep funds available so the project does not stall just short of completion.

    Building your team early

    The strongest custom-home projects begin with the right team assembled before ground is broken: a lender experienced in construction financing, an architect or designer, a reputable builder, a real estate attorney, and a title company familiar with draw administration. Aligning these professionals around one budget and one schedule reduces friction and gives lenders confidence in the project, which can translate into smoother approvals and fewer delays.

    Frequently asked questions

    Can I lock my rate before construction starts?

    Many one-time-close programs allow a rate lock at closing, sometimes with a float-down option, but terms vary by lender. Ask specifically how long the lock lasts and what it costs.

    What happens if construction runs over budget?

    You may need to bring additional funds, or the lender may allow a change order if the appraised value supports it. This is why a contingency reserve is so important.

    Is a construction loan harder to get than a regular mortgage?

    Generally yes, because the lender is financing a home that does not yet exist. Expect more documentation, builder vetting, and higher reserve requirements.

    Ready to talk through your plans? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation about luxury real estate in Philadelphia and South Jersey.

  • Mantua and Harrison Townships, New Jersey: A Gloucester County Guide for Luxury and Executive-Home Buyers

    Mantua Township and Harrison Township sit in the heart of Gloucester County, a short drive from Wenonah, Pitman, Mullica Hill, and the Route 55 and I-295 corridors that lead to Philadelphia and the shore. For luxury buyers who want space, newer construction, and a quieter pace than the inner Camden County suburbs, these two townships deserve a careful look.

    The character of the two townships

    Both townships blend long-established residential streets with newer planned communities and pockets of open land. Harrison Township, which shares the Mullica Hill postal identity in part, is known for larger-lot subdivisions and executive-style homes built in recent decades. Mantua Township offers a wider range, from modest older neighborhoods to newer developments and acreage on its more rural edges. The practical result is that luxury-level homes here are often large, relatively new, and set on generous lots rather than historic and walkable.

    What luxury buyers typically find

    • Executive and custom homes: Large floor plans, finished basements, three-car garages, and outdoor living areas are common in newer subdivisions.
    • Acreage and semi-rural properties: Some parcels offer privacy, room for outbuildings, and in certain cases well and septic systems.
    • Newer systems: Younger homes often mean more modern mechanicals, though builder-grade finishes may deserve a closer look.

    Commuting and access

    Access to Route 55, Route 322, and I-295 makes drives to Center City Philadelphia, the airport, and the Delaware River bridges manageable, while the shore is reachable on a weekend morning. Commute times vary widely with traffic, so test the drive at the hours you would actually travel before committing to a specific street.

    Schools, services, and community life

    Public school districts differ by township and even by neighborhood, and boundaries should always be verified directly with the district rather than assumed from a listing. Beyond schools, buyers often weigh proximity to the dining and shops of Mullica Hill and Pitman, parks and open space, and the convenience of nearby medical and retail centers.

    Due diligence specific to this area

    Because many properties here are newer or semi-rural, several items deserve attention:

    • Private well and septic: Confirm testing requirements and the age and condition of the system on non-sewered parcels.
    • Drainage and grading: Newer developments can have stormwater basins and grading issues worth a close look.
    • HOA rules: Review governing documents for fence, pool, and exterior-change restrictions.
    • Farmland assessment: If a property carries a farmland assessment, understand the rollback tax implications before closing.

    Pricing and value

    Value in these townships tends to be driven by lot size, school district, condition, and the quality of the builder and finishes. Because comparable sales can be sparse for the largest or most custom homes, a thoughtful analysis of recent closings and active competition matters far more than a rule of thumb. For current figures, reach out directly.

    Who tends to be happy here

    Buyers who prioritize space, newer construction, and value per square foot compared with closer-in suburbs often find these townships appealing. Buyers who want a walkable downtown and historic architecture may prefer Haddonfield or Collingswood, with Mullica Hill offering a village-style middle path.

    Questions to ask before you make an offer

    Every township has its own rhythm, so a little homework goes a long way. Walk the neighborhood at different times of day, noting traffic, noise, and how well the common areas and roadways are maintained. Ask about planned development nearby, since open land in Gloucester County can change character over a few years. Request recent utility bills, tax information, and any homeowner association documents early. Speak with neighbors if you can, and compare at least two or three competing streets before settling on one.

    Timing and negotiation

    Larger executive homes often take longer to sell than entry-level properties, which can create room to negotiate on price, credits, or closing timeline. At the same time, genuinely well-presented homes on desirable lots can draw competition quickly. Having your financing pre-approved for a jumbo amount, understanding your inspection priorities, and knowing your walk-away number lets you act decisively when the right house appears. A local agent who tracks both active and recently sold luxury listings can help you read which situation you are in.

    Planning for the long term

    Think beyond the first year. Consider how the home will serve you as your household changes, what ongoing maintenance a larger lot requires, and how property taxes compare with neighboring towns. New Jersey property taxes vary meaningfully from one municipality to the next, so review the actual tax bill and consider how a reassessment could affect carrying costs.

    Working with a local luxury agent

    Gloucester County moves differently from Haddonfield or Rittenhouse Square, and the right guidance depends on understanding which subdivisions hold value, which builders have strong reputations, and how recent sales compare to current asking prices. A local advisor can also help you weigh the trade-offs between these townships and neighboring Mullica Hill, Wenonah, and Pitman so that you buy where your priorities are best served.

    Frequently asked questions

    Is Mantua or Harrison Township better for luxury buyers?

    Neither is universally better. Harrison Township tends to offer more large-lot executive subdivisions, while Mantua offers a broader mix including acreage. The right fit depends on your school district, commute, and style preferences.

    Do homes here use well and septic?

    Some do, particularly on larger or more rural parcels, while others are on public water and sewer. Always confirm utilities for the specific address and budget for appropriate testing.

    How do these townships compare to Mullica Hill?

    Mullica Hill offers a historic village center with dining and shops, while the surrounding townships provide the larger lots and newer homes. Many buyers shop all three together.

    Ready to talk through your plans? Contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com for a confidential conversation about luxury real estate in Philadelphia and South Jersey.

  • Living Near Philadelphia’s Great Parks and Trails: A Luxury Buyer’s Guide to Green-Space Addresses

    For many affluent buyers, the most valuable amenity is not inside the house. It is the park, trail, or tree canopy just beyond the front door. Philadelphia is unusual among major American cities for the scale of its park system, and that green space influences which neighborhoods feel calm, walkable, and resilient.

    Why green space matters to luxury buyers

    Parks provide daily recreation, buffer noise, and preserve views. Over time, homes bordering protected open space often benefit from the knowledge that the surrounding landscape is unlikely to be developed. That does not guarantee appreciation, but it supports long-term desirability, particularly when paired with good schools and transit.

    Wissahickon Valley and the Northwest

    The Wissahickon Valley is a defining feature of Northwest Philadelphia. Neighborhoods such as Chestnut Hill, Mount Airy, Roxborough, and East Falls offer residents access to wooded trails, creek scenery, and a sense of retreat that is rare inside a major city. Housing in these areas ranges from historic stone single-family homes to carefully maintained twins, and many buyers value the combination of architecture and trail access.

    Fairmount Park and the river corridor

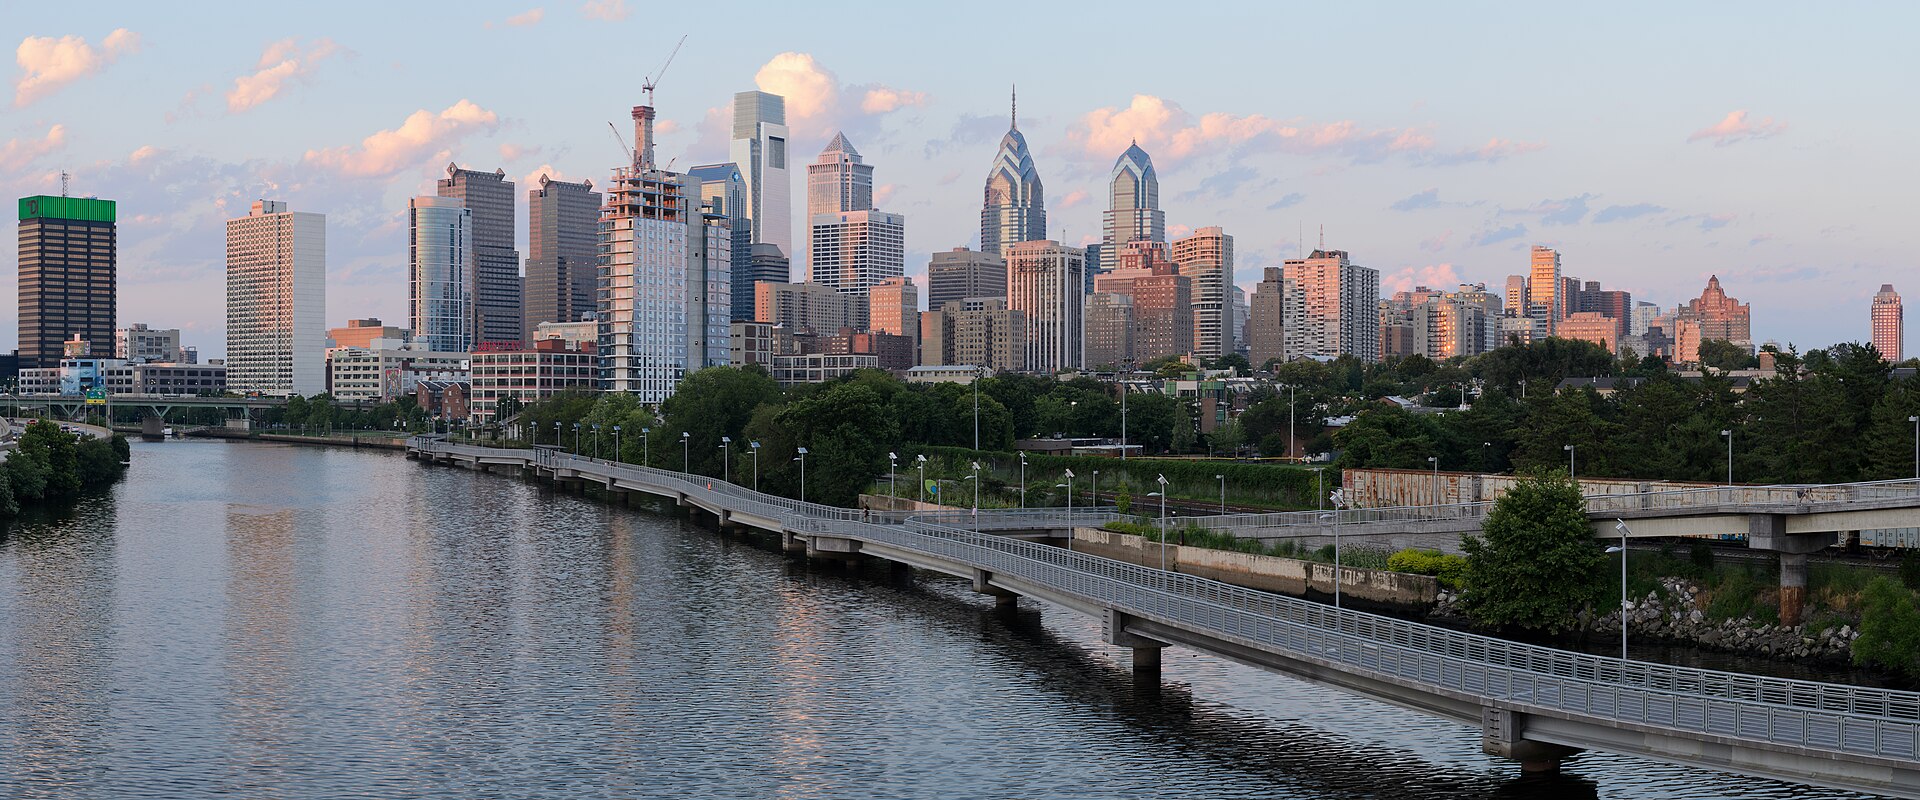
    Fairmount Park and the Schuylkill River Trail connect Center City with neighborhoods like Fairmount, Brewerytown, East Falls, and Manayunk. Buyers who prioritize running, cycling, and riverfront views often target addresses within an easy walk of the trail network. Condominiums with river or park views can offer a different version of this lifestyle for buyers who prefer low-maintenance living.

    Parks and open space in the suburbs

    Outside the city, regional parks, preserved farmland, and township open space shape the character of towns on the Main Line, in Chester and Bucks Counties, and across South Jersey. In many communities, trails and preserved land define the character of the area, giving estate buyers room and privacy even in established neighborhoods.

    What to evaluate when buying near green space

    Ownership and protection

    Not every green-looking area is permanently protected. Ask whether nearby land is public parkland, preserved through easements, or privately owned and potentially developable.

    Floodplain and drainage

    Creeks and rivers add beauty, but low-lying parcels can be affected by flooding or stormwater. Review flood maps, insurance requirements, and the property’s history.

    Trees and maintenance

    Mature trees are an asset, but they require pruning, storm preparation, and sometimes permits for removal. Have large trees assessed during due diligence.

    Noise, access, and privacy

    Homes adjacent to trailheads may enjoy convenience but see more foot traffic. Visit at different times of day and week before deciding.

    Pairing green space with other priorities

    The best purchase rarely rests on one feature. Consider commuting, schools, dining, and the condition of the home alongside the park. A beautiful setting can offset a longer commute for some buyers, while others prefer a smaller footprint close to Center City.

    Seasonal considerations

    Visit prospective neighborhoods in more than one season. Summer foliage can hide views and traffic, while winter reveals both. Spring and fall bring crowds on popular trails, which can matter for parking and privacy.

    Everyday lifestyle benefits

    Beyond the investment angle, living near green space shapes how a household spends its time. Morning runs, weekend bike rides, dog walks, and quiet evenings in the woods become part of ordinary life rather than occasional outings. Families often value having safe, scenic places for children to play, while empty nesters appreciate easy walking and nature without yard maintenance.

    Condos, townhomes, and single-family options

    Green-space living does not require a large house. In Philadelphia, condominiums along the river corridor and near Fairmount Park deliver trail access with building amenities and less upkeep. Townhomes and twins in Northwest neighborhoods balance character and convenience. Estate buyers in the suburbs may prefer acreage that creates its own park-like setting. The right format depends on how much maintenance you want and how much privacy you value.

    Community involvement and stewardship

    Friends-of groups, conservancies, and neighborhood associations help maintain many parks and trails. Buyers who care about the long-term health of their surroundings sometimes find that involvement creates community and a stronger connection to the neighborhood. Ask neighbors and local organizations what projects are underway, since improvements to trails, bridges, and public spaces can enhance quality of life over time.

    Preparing your search

    Create a short list of the parks and trails you use most, then map neighborhoods within a comfortable walk, bike ride, or short drive. Tour homes at the times you would actually use the trails, and bring a pair of walking shoes. Many buyers learn more from thirty minutes on the nearest path than from a second showing inside the house, and the experience helps you decide which setting truly fits your daily routine.

    Frequently asked questions

    Do homes near parks sell for more?

    Often they are more desirable, but pricing depends on the home’s condition, the neighborhood, and the specific setting. A park location is one factor among many.

    Are park-adjacent homes at higher flood risk?

    Some are, particularly near creeks and rivers. Always check flood maps and consult an insurance professional before making an offer.

    Which Philadelphia neighborhoods offer the most direct park access?

    Chestnut Hill, Mount Airy, Roxborough, East Falls, and Fairmount are known for proximity to major parks and trails, though many other areas also have excellent green-space access.

    Ready to talk through your options? Contact James Kennedy, luxury real estate advisor serving Philadelphia and South Jersey, at 215-267-8479 or jameskennedy@unlockedteam.com for current local guidance.