Category: Market Insights

  • Gifted Down Payments and Family Financing: What Philadelphia & South Jersey Luxury Buyers Should Know

    Gifted Down Payments and Family Financing: What Philadelphia & South Jersey Luxury Buyers Should Know

    At the luxury level, it is common for a purchase to involve more than a single buyer’s own savings and income. Parents help adult children with a down payment, spouses receive family gifts toward a shared purchase, and in some cases extended family co-invest in a second home or a Shore property. None of this is unusual, but it does add documentation steps that can slow down or even derail a closing if they are not handled correctly from the start.

    Why Family Financing Is Common at the Luxury Level

    Jumbo loans and larger purchase prices mean larger down payments in absolute dollar terms, even when the percentage down is unchanged. It is not unusual for a family to want to help a buyer avoid a larger loan, secure a better rate by improving the loan-to-value ratio, or simply enable a purchase that timing alone would otherwise delay. Lenders are well accustomed to this at the luxury level, but they require specific documentation to distinguish a genuine gift from an undisclosed loan, since a hidden liability can change a buyer’s true debt-to-income picture.

    Gift Letters and Documentation Lenders Require

    Most lenders require a signed gift letter stating the donor’s relationship to the buyer, the exact dollar amount, the property address, and explicit language confirming the funds are a gift with no expectation of repayment. Beyond the letter, lenders typically want to see the funds move from a documented account belonging to the donor into the buyer’s account, along with bank statements showing the source of those funds on the donor’s side. The goal is a clean paper trail: money that can be traced from an identifiable account to the buyer, with no unexplained cash deposits along the way.

    Buyers should loop in their lender before funds move, not after, since the specific sequencing and documentation requirements can vary by loan program and by lender.

    Seasoning Requirements and Paper Trails

    Many loan programs have “seasoning” requirements, meaning funds need to sit in the buyer’s account for a certain period, or be clearly documented as a gift, before they can be counted toward a down payment or reserves. Large, unexplained deposits close to a purchase can trigger additional underwriting questions and delay a closing timeline. Families planning to help with a purchase are generally well served by moving the gift funds as early as practical once a purchase is anticipated, and by keeping clear records of the transfer rather than relying on memory later in the process.

    Co-Borrowing, Co-Signing, and Joint Ownership

    Beyond a straightforward gift, some families structure a purchase with a parent or relative as a co-borrower or co-signer, or with more than one generation on the title. Each approach has different implications for whose credit and income qualify the loan, whose name appears on the deed, and how the property would be handled later in an estate or in the event of a sale. These are structural decisions that benefit from input by a real estate attorney and, where the amounts are significant, a financial or estate planning advisor, since the right structure depends on each family’s specific goals rather than a one-size-fits-all answer.

    Keeping the Timeline on Track

    The most common way family financing derails a closing is timing: gift funds that move too close to closing, a gift letter that is missing required language, or a donor’s bank statement that raises its own questions during underwriting. Buyers working with family support should build in extra time at the start of the process, share the lender’s specific gift documentation requirements with the donor early, and avoid any last-minute transfers once a closing date is set.

    Tax and Estate Planning Considerations

    Family gifts toward a home purchase can intersect with federal gift tax rules and, for larger transfers, a donor’s lifetime exemption. Most routine down-payment gifts fall well within annual exclusion amounts, but families structuring a larger contribution, or combining gifts from multiple relatives toward one purchase, should talk with a tax professional or estate planning attorney before funds move rather than after. The right approach also depends on whether the family views the contribution as a one-time gift or as part of a longer-term plan, such as an early step in transferring wealth across generations, which is a conversation best had with an advisor who knows the family’s full financial picture.

    A Note on Private Family Loans

    Some families prefer a private loan rather than an outright gift, often to preserve flexibility or to formalize an expectation of repayment. Where that is the plan, the arrangement should be documented as an actual loan, with a promissory note, a market-appropriate interest rate, and clear terms, since an informal arrangement that a lender later discovers was intended as a loan rather than a gift can affect a buyer’s qualifying debt-to-income ratio. Buyers considering this route should discuss it with both their lender and an attorney before the funds are transferred, so the loan can be properly disclosed and does not create a problem during underwriting.

    Frequently asked questions

    Does a gifted down payment need to come from a relative?

    Loan programs generally define who qualifies as an acceptable gift donor, and this is usually limited to family members or, in some cases, a close and clearly documented relationship. A lender can confirm exactly who qualifies under a specific loan program before funds move.

    Can gift funds be used for the entire down payment on a luxury purchase?

    It depends on the loan program and the loan-to-value ratio. Some programs allow gift funds to cover the entire down payment, while others require the buyer to contribute a minimum amount from their own funds, particularly on larger jumbo loans. This is worth confirming with a lender at the very start of the process, before an offer is written.

    Should a family gift be documented even on an all-cash purchase?

    Yes. Even without a mortgage, title companies and settlement agents may ask about the source of large deposited funds as part of standard anti-money-laundering procedures, so a clear gift letter and paper trail is worth having regardless of financing.

    If you are planning a luxury purchase in Philadelphia or South Jersey with help from family and want to understand how to structure it cleanly, James Kennedy can help connect you with lenders and attorneys experienced in these transactions. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Short-Term Rental Rules for Luxury Homes in Philadelphia: What Owners and Investors Should Know

    Short-Term Rental Rules for Luxury Homes in Philadelphia: What Owners and Investors Should Know

    Some luxury buyers in Philadelphia are drawn not just to a home or condo itself but to the possibility of renting it out short-term when it is not in use — whether that means an occasional Airbnb listing for a pied-a-terre, or a more active rental strategy for an investment property. Unlike the Jersey Shore, where short-term rentals are woven into the seasonal economy, Philadelphia treats short-term rentals as a distinct, regulated category within city licensing and zoning code. Any buyer considering this as part of their plan should understand the framework before making an offer, not after.

    Why This Matters for Luxury Buyers

    Short-term rental potential can be a meaningful part of the value proposition for a high-end condo or a pied-a-terre purchased partly as an investment. But it can just as easily become a liability if a building’s association prohibits it, if a property sits in a zoning district that restricts it, or if a buyer simply did not budget for licensing and compliance requirements. Because the rules touch city licensing, zoning, condo or HOA governance, and tax reporting all at once, it is worth treating short-term rental viability as its own line item in due diligence rather than an assumption.

    Philadelphia’s Licensing Framework

    Philadelphia regulates short-term rentals — generally defined as rentals of fewer than thirty consecutive days — through its Department of Licenses and Inspections, and the city distinguishes between different categories of short-term rental depending on factors like whether the owner lives in the property full-time, part-time, or not at all. Owner-occupied situations, where a resident occasionally rents a room or their whole home while traveling, are generally treated differently from non-owner-occupied investment rentals, which face additional zoning and licensing scrutiny. Because these rules and the specific license types involved can change, and because compliance requirements are detailed, buyers should verify current requirements directly with the city or with a real estate attorney rather than relying on secondhand summaries, including this one.

    Zoning and Neighborhood Restrictions

    Beyond licensing, Philadelphia’s zoning code affects where certain categories of short-term rental are permitted outright, permitted with additional approval, or not permitted at all. Zoning treatment can vary meaningfully by neighborhood and by the specific base zoning of a property, which means two similar-looking properties on different blocks can face different rules. This is a case where a pre-offer conversation with the city, a zoning attorney, or an experienced local agent can save significant time and expense compared with discovering a restriction after closing.

    HOA and Condo Building Restrictions

    Even where city rules would allow a short-term rental, many condo and HOA governing documents in Philadelphia’s luxury buildings prohibit or tightly restrict rentals under thirty or ninety days, regardless of what the city permits. Building boards frequently view short-term guests as a lifestyle and security concern for other owners, and rental restrictions are one of the more common — and more strictly enforced — provisions in luxury building bylaws. Any buyer counting on short-term rental income from a condo purchase should request and read the building’s current rules on rentals before going under contract, not after closing.

    Insurance and Tax Considerations

    A property used for short-term rental typically needs insurance coverage suited to that use; a standard homeowner’s policy written for owner-occupancy may not adequately cover short-term guest stays, and insurers increasingly ask directly about rental activity when underwriting or renewing a policy. Short-term rental income is also generally taxable and often subject to hotel or occupancy-type taxes in addition to ordinary income tax, with reporting requirements that differ from long-term residential leasing. Because insurance and tax treatment both depend on the specifics of a given property and owner’s situation, this is an area where a qualified insurance broker and a tax professional should be part of the pre-purchase planning conversation.

    Weighing Short-Term Rental Against a Long-Term Leasing Strategy

    For buyers weighing whether a Philadelphia luxury property should be rented short-term or leased on a traditional long-term basis, it helps to think through the trade-offs deliberately rather than defaulting to whichever model sounds more profitable. Short-term rental can generate stronger income during peak periods and gives the owner more personal use of the property between guest stays, but it also comes with more active management, higher turnover-related wear, and the licensing and zoning complexity described above. A traditional long-term lease is typically simpler to manage, faces far less regulatory friction, and is usually the default assumption most condo and HOA boards are comfortable with — but it also means giving up flexible personal use of the home and generally produces a steadier, if less headline-grabbing, return. Many buyers find that the right answer depends less on which model earns more on paper and more on how much hands-on involvement they actually want, and whether the specific building or neighborhood realistically supports short-term use at all.

    Working Backward From the Building or Block

    Because so much of the real constraint here is set at the building or neighborhood level rather than by a buyer’s own preferences, it is worth working backward: start with the specific building’s rules or the specific block’s zoning before falling in love with a rental income projection. An agent who knows a given condo association’s rental history, or who can point to how a neighborhood’s zoning has actually been enforced in practice, can save a buyer from the common mistake of assuming rental flexibility that a property simply does not have.

    Frequently asked questions

    Can I run an Airbnb in any Philadelphia condo I buy?

    Not necessarily. Even if city rules would permit it, many condo and HOA governing documents restrict or prohibit short-term rentals. Always review the specific building’s current rules before assuming rental income is possible.

    Is short-term rental treated the same in Philadelphia as at the Jersey Shore?

    No. Jersey Shore communities generally build seasonal short-term rentals into their local economy and regulatory framework, while Philadelphia treats short-term rentals as a more tightly licensed and zoned category within a primarily long-term residential market. The rules, required licenses, and enforcement approach differ meaningfully between the two.

    Who should I talk to before buying a property specifically for short-term rental income?

    A real estate attorney familiar with Philadelphia licensing and zoning, the specific condo or HOA board if applicable, an insurance broker who can confirm appropriate coverage, and a tax professional who can explain reporting obligations. Confirming all four before you buy is far easier than untangling a problem afterward.

    If a short-term rental strategy is part of your plan for a Philadelphia purchase, it pays to have local guidance before you write an offer. James Kennedy works with luxury buyers and investors throughout Philadelphia and South Jersey and can help you evaluate a property’s real rental potential. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Dual Agency and Designated Agency Explained: What Luxury Buyers and Sellers Should Know in Pennsylvania and New Jersey

    Dual Agency and Designated Agency Explained: What Luxury Buyers and Sellers Should Know in Pennsylvania and New Jersey

    In a competitive luxury market, it is common for the same brokerage — sometimes even the same agent — to have a relationship with both the buyer and the seller in a transaction. When that happens, Pennsylvania and New Jersey law require specific disclosures and, in many cases, offer a choice between dual agency and a structure called designated agency. Understanding the difference matters for any buyer or seller working with a boutique or high-volume brokerage where in-house cross-representation is more likely to come up.

    What Dual Agency Means

    Dual agency occurs when one agent represents both the buyer and the seller in the same transaction. Because that agent owes duties of loyalty and full disclosure to two parties whose interests are, at least in part, opposed — one wants the highest price and best terms, the other wants the lowest price and most favorable terms — dual agency necessarily limits what that agent can do for either side. A dual agent generally cannot advise either party on pricing strategy, cannot disclose one party’s confidential motivations to the other, and must remain neutral on negotiation strategy. Both Pennsylvania and New Jersey permit dual agency, but only with informed, written consent from both parties.

    Designated Agency as a Middle Path

    Many brokerages — particularly those handling a high volume of listings in a concentrated luxury market — prefer designated agency (sometimes called appointed agency) as an alternative. Under this structure, the brokerage as a whole may represent both the buyer and the seller, but two different agents within that brokerage are individually designated to represent each party. Each designated agent owes full fiduciary duties, including advice on pricing and negotiation strategy, to their own client only. This preserves more individual advocacy than dual agency while still allowing a brokerage to bring both sides of a transaction together under one roof, which is common when a listing agent’s own buyer client wants to see that agent’s own listing.

    How Pennsylvania Regulates These Relationships

    Pennsylvania’s real estate licensing law requires written disclosure of the agency relationship early in a transaction, typically through a consumer notice provided at first substantive contact. Dual agency is permitted with informed written consent from both parties, and Pennsylvania brokerages commonly use designated agency to allow individual agents within the same firm to advocate fully for their own clients even when the brokerage itself is technically dual. Buyers and sellers should read the specific disclosure language they are asked to sign carefully rather than treating it as a routine formality — it defines exactly what the agent can and cannot do on their behalf.

    How New Jersey Regulates These Relationships

    New Jersey similarly requires agency disclosure, delivered through a required consumer information statement early in the buyer or seller relationship. New Jersey law also recognizes disclosed dual agency with informed consent, and many New Jersey brokerages, like their Pennsylvania counterparts, use designated or appointed agency internally to give each party a dedicated advocate. In both states, a party who does not want to proceed under dual agency has the right to decline and, if needed, work with a different brokerage entirely for one side of the transaction.

    What Luxury Buyers and Sellers Should Ask

    Given how much is at stake in a high-value transaction, it is reasonable — and expected — to ask direct questions before signing any agency disclosure:

    • Is this a dual agency situation, a designated agency situation, or single-side representation?
    • If dual or designated agency applies, who specifically will be advising me on price and negotiation strategy?
    • What information will and will not be shared with the other party?
    • Do I have the option to work with a different agent or brokerage if I am not comfortable with the proposed structure?

    A brokerage that regularly handles luxury transactions should be able to answer these questions clearly and walk through the relevant disclosure forms line by line, well before an offer is drafted.

    Why This Comes Up More Often in a Concentrated Luxury Market

    Dual and designated agency situations tend to surface more frequently at the higher end of the Philadelphia and South Jersey markets than in the broader market overall. Luxury inventory is naturally more limited, and a small number of boutique brokerages and top-producing teams often handle a disproportionate share of high-end listings in a given neighborhood or town. That means a buyer touring luxury homes in, say, Rittenhouse Square or along the Main Line is statistically more likely to encounter a listing represented by the same brokerage — sometimes the same agent — they are already working with. Understanding agency structure ahead of time, rather than being surprised by it mid-showing, lets buyers and sellers make an informed decision in the moment rather than scrambling to evaluate a new disclosure form under time pressure.

    How This Can Affect Negotiation Strategy

    The practical impact of agency structure often shows up most clearly during negotiation. A buyer working with a single-side buyer’s agent can expect that agent to advise candidly on offer price, contingencies, and strategy based solely on the buyer’s interests. Under dual agency, that same advice is necessarily more limited, since the agent cannot ethically steer either party toward terms that disadvantage the other. Designated agency narrows that gap by preserving individual advocacy on both sides even within one brokerage, which is part of why many firms — including boutique luxury brokerages — favor it as their standard in-house structure rather than pure dual agency. Buyers and sellers who understand this distinction going in are better positioned to ask for the level of advocacy they actually want.

    Frequently asked questions

    Do I have to agree to dual agency if my agent’s brokerage also represents the seller?

    No. Both Pennsylvania and New Jersey require informed written consent before dual agency can proceed. If you are not comfortable with it, you can decline and, where necessary, work with a different agent or brokerage for your side of the transaction.

    Is designated agency the same as dual agency?

    No. In dual agency, one agent represents both parties. In designated agency, two different agents within the same brokerage are each designated to represent one party individually, preserving more individual advocacy than a single dual agent can offer.

    Does dual or designated agency affect commission?

    The agency structure itself does not set commission; commission terms are negotiated separately and disclosed in the listing agreement and buyer agency agreement. Ask your agent to walk through how compensation works alongside the agency disclosure so both are clear before you sign anything.

    Navigating agency relationships is one more detail worth getting right in a high-value transaction. James Kennedy represents luxury buyers and sellers throughout Philadelphia and South Jersey and is happy to walk you through exactly how representation works before you sign anything. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Wire Fraud and Closing Scams: Protecting a Luxury Real Estate Transaction in Philadelphia & South Jersey

    Wire Fraud and Closing Scams: Protecting a Luxury Real Estate Transaction in Philadelphia & South Jersey

    The single largest wire transfer most people ever send in their lives is often the one that closes on their home. That fact has not gone unnoticed by criminals. Real estate wire fraud, in which scammers intercept or spoof communications to redirect closing funds into a fraudulent account, has grown into one of the costliest forms of cybercrime in the country, and luxury transactions, with their large dollar amounts and multiple parties, are a particularly attractive target. Understanding how these scams work is the best defense a buyer or seller has.

    How Wire Fraud Targets Real Estate Closings

    Most real estate wire fraud follows a similar pattern. Criminals gain access to an email account belonging to one party in the transaction, often a buyer, agent, title company, or attorney, sometimes through a phishing email sent weeks earlier. They then quietly monitor the email thread until closing approaches. Just before funds are due, the scammer sends an email, made to look like it comes from the title company or settlement attorney, with “updated” wiring instructions directing the buyer’s funds to an account the criminal controls. By the time anyone realizes what happened, the money has often already been moved out of the country or dispersed across multiple accounts, making recovery extremely difficult.

    Why Luxury Transactions Are a Frequent Target

    Criminals follow the money. A transaction involving a $1.5 million home carries a far larger potential payout than an average sale, which makes luxury buyers and sellers disproportionately targeted. High-end deals also frequently involve more parties, attorneys, out-of-state buyers, trust or LLC entities, private lenders, which creates more email threads and more opportunities for a scammer to insert a convincing, well-timed message.

    Common Red Flags

    • An email claiming that wiring instructions have “changed” or been “updated,” especially arriving close to closing.
    • Urgent language pressuring you to wire funds immediately to avoid delaying settlement.
    • A sender email address that looks almost right but has a subtle misspelling or extra character.
    • A phone number listed in the suspicious email that differs from the one you already have on file for your title company or attorney.
    • Instructions to wire to a bank or account holder name that doesn’t match the title company’s established account.

    Best Practices Before You Wire a Dollar

    The core rule is simple and worth repeating to everyone involved in your transaction: never wire funds based solely on emailed instructions, and never trust a phone number provided in that same email. Instead, before closing begins, get your title company’s or settlement attorney’s wiring instructions verbally, in person or by calling a phone number you have independently verified, such as one from their official website or a prior, trusted communication. Confirm the instructions again by phone immediately before sending any funds, even if you received them earlier in the process. If anything about an email feels off, whether it’s tone, timing, or formatting, call the sender directly using a known number rather than replying to the email or using any contact information contained in it.

    Steps Your Transaction Team Should Already Take

    A well-run luxury transaction should have safeguards built in well before your closing date. Reputable title companies and real estate attorneys typically use secure client portals rather than email for sharing wiring instructions, may call to confirm instructions verbally, and will never ask you to make a last-minute change without a documented, verifiable process. If your title company or closing attorney cannot explain their wire fraud prevention protocol clearly, that alone is worth asking more questions about before you get anywhere near closing day.

    What to Do If You Suspect Fraud

    Speed matters more than almost anything else if a fraudulent wire has already been sent. Contact your bank immediately and request a wire recall, then file a report with the FBI’s Internet Crime Complaint Center (IC3.gov) and notify your title company, real estate attorney, and agent right away. Banks can sometimes freeze or claw back funds within the first 24 hours, but that window closes quickly, so acting the moment something seems wrong is far more effective than waiting to confirm your suspicions.

    Building a Trusted Team

    The strongest protection against wire fraud is working with an experienced agent, a reputable title company, and, when appropriate, a real estate attorney who take these risks seriously and communicate clearly about how and when funds will move. For out-of-state or international buyers unfamiliar with local closing customs, this guidance matters even more, since unfamiliarity with the process is exactly what scammers count on.

    Frequently asked questions

    Can a bank always reverse a fraudulent wire transfer?

    Not always, and success depends heavily on how quickly the fraud is reported. Funds moved to a fraudulent account are sometimes withdrawn or transferred elsewhere within hours, so immediate action gives you the best, though still not guaranteed, chance of recovery.

    Should I ever trust wiring instructions sent by email?

    Treat any emailed wiring instructions as unverified until you confirm them by phone using a number you sourced independently, not one provided in the email itself. This single habit prevents the vast majority of real estate wire fraud.

    Are cashier’s checks safer than wire transfers for closing funds?

    Many title companies and attorneys still accept wire transfers because they are fast and traceable, but ask your closing team what payment methods they support and whether they have a preference; some offer alternatives that reduce certain fraud risks. Whatever method you use, verify the recipient details independently before sending funds.

    Buying or selling a luxury home in Philadelphia or South Jersey involves more moving parts than most transactions, and having a team that takes security seriously matters. James Kennedy works closely with trusted title companies and attorneys throughout every closing. Call James at 215-267-8479 or email jameskennedy@unlockedteam.com to talk through your transaction with a team that protects your interests at every step.

  • Builder Warranties and New Construction Protections: What Luxury Buyers Should Know Before Closing on a New Home

    Builder Warranties and New Construction Protections: What Luxury Buyers Should Know Before Closing on a New Home

    Buying new construction feels, understandably, like the lowest-risk way to purchase a home — everything is new, nothing is worn out, and a builder stands behind the work. That confidence is generally well placed, but it’s worth understanding exactly what a builder warranty covers, how long different types of coverage last, and where the gaps typically show up. For a luxury buyer investing significantly in a new build, a clear-eyed understanding of these protections is as important as the finish selections.

    The Standard New Home Warranty Structure

    Most production and custom builders in the Philadelphia and South Jersey markets offer warranty coverage structured in tiers, often described informally as a “2-10” warranty, though exact terms vary by builder:

    • Workmanship and materials — typically covered for the first year, addressing issues like drywall cracks, paint defects, and minor workmanship problems that surface as a new home settles.
    • Systems coverage — often two years, covering major mechanical systems such as plumbing, electrical, and HVAC distribution.
    • Structural coverage — commonly extends up to ten years, but is narrowly defined to cover major structural defects, not everyday wear or cosmetic issues.

    These timeframes are common in the industry but are not guaranteed by law to look exactly this way — always read the specific warranty document your builder provides rather than assuming it matches this general structure.

    What’s Typically Covered vs. Excluded

    Structural warranties are usually written narrowly, covering defects that affect the load-bearing elements of the home rather than issues that are cosmetic, related to normal settling, or caused by a lack of maintenance. Appliances are almost always covered separately by the manufacturer, not the builder, so it’s worth keeping manufacturer warranty documentation organized from day one. Landscaping, minor cracking in concrete or drywall, and normal wear on high-traffic finishes are commonly excluded or covered for only a short initial period.

    Punch Lists and the Walkthrough Process

    Before closing, most builders schedule a pre-settlement walkthrough where the buyer identifies incomplete or unsatisfactory items — commonly called a punch list. This is the buyer’s opportunity to flag scratched surfaces, misaligned cabinetry, paint touch-ups, or anything that doesn’t match the agreed specifications. A few practices make this process go more smoothly:

    Getting the most out of your walkthrough

    • Schedule the walkthrough during daylight hours so imperfections are easier to spot
    • Bring painter’s tape or sticky notes to flag issues in person rather than relying on a written list alone
    • Get a written commitment and timeline from the builder for completing punch list items, ideally before or very close to closing
    • Take dated photos of any open items as a record

    Considerations in Pennsylvania and New Jersey

    Both Pennsylvania and New Jersey have legal frameworks that touch on new home construction and warranty obligations, and requirements can differ from one municipality or builder to the next. Rather than relying on general assumptions, buyers should ask their real estate attorney to review the specific builder’s warranty documents and purchase agreement before signing, and confirm how any state-specific consumer protections apply to the transaction. This is a case where a modest legal review fee upfront is inexpensive insurance against a much larger dispute later.

    Independent Inspections for New Construction

    It’s common for buyers to skip a professional inspection on new construction, reasoning that everything is brand new and presumably built to code. In practice, new homes can and do have defects — missed connections, incomplete flashing, or HVAC systems that aren’t balanced correctly — that a municipal code inspection may not catch. An independent, buyer-hired inspector, ideally one experienced with new construction specifically, can identify issues while the builder is still contractually and practically motivated to fix them, rather than after you’ve moved in and warranty conversations become more adversarial.

    Frequently asked questions

    Do I still need a home inspection on new construction?

    Yes. A municipal inspection confirms code compliance, but it isn’t the same as an independent, buyer-focused inspection looking for workmanship issues, incomplete details, or systems that aren’t functioning as intended. Many luxury buyers hire an independent inspector for new construction specifically to have documented leverage before closing, while the builder still has strong incentive to address findings.

    What happens if the builder goes out of business during the warranty period?

    This is one of the more important questions to ask before you buy, particularly for a smaller or regional builder. Some warranty programs are backed by third-party insurance that continues to provide coverage even if the builder closes, while others are only as strong as the builder standing behind them. Ask specifically whether the structural warranty is insured through a third party, and get the answer in writing.

    How long does a structural warranty typically last?

    Ten years is a common length for structural coverage in the industry, but the definition of what counts as a covered “structural defect” is usually narrow and specific to the warranty document. Always read the actual warranty terms rather than assuming a ten-year structural warranty covers everything wrong with the house for a decade — it generally does not.

    Whether you’re evaluating a new construction contract or comparing it against an existing home, James Kennedy can help you understand what you’re being offered and what questions to ask before you sign. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Rent-Backs and Post-Settlement Possession: How Luxury Sellers Stay in the Home After Closing in Pennsylvania and New Jersey

    Rent-Backs and Post-Settlement Possession: How Luxury Sellers Stay in the Home After Closing in Pennsylvania and New Jersey

    At the luxury end of the market, the closing date and the moving date are rarely the same day. A seller with a custom home under construction, a child finishing a school term, an international relocation, or simply forty years of belongings often needs to stay in the house for a period after settlement. The tool for that is a rent-back — also called a post-settlement possession agreement, use and occupancy agreement, or seller lease-back depending on who is drafting it.

    Used well, a rent-back is one of the strongest non-price concessions a buyer can offer, and one of the most valuable things a seller can negotiate. Used carelessly, it creates a landlord-tenant relationship nobody signed up for. Here is how to do it right on both sides of the river.

    What a rent-back actually is

    At settlement, ownership transfers to the buyer. A rent-back is a separate written agreement under which the seller — now no longer the owner — remains in possession of the property for a defined period, usually paying the new owner a daily or monthly amount and posting a security deposit held from proceeds.

    The key mental shift for sellers is this: the moment the deed records, you are occupying someone else’s house. Your homeowner’s policy no longer applies the way it did, your responsibilities are contractual rather than ownership-based, and the buyer is now carrying a mortgage on a property they cannot occupy.

    Why buyers agree to it

    In competitive luxury negotiations, a rent-back is often worth more to a seller than an extra increment of price. Sellers who are building or relocating value certainty of timing enormously. A buyer who can offer a flexible, generous possession period sometimes wins a property over a marginally higher offer that demands keys at the table.

    It also benefits buyers in ways that are easy to overlook. A rent-back period gives you a window to schedule contractors, take measurements, arrange deliveries, and finish your own sale without pressure — provided the agreement lets you access the property with reasonable notice.

    The financing constraint buyers must check first

    This is the single most common place rent-backs fail. Residential mortgage financing generally requires the buyer to occupy the property as a primary residence within a defined window after closing — commonly sixty days. A short rent-back typically fits comfortably inside that window. A long one may not, and can push the loan into a different occupancy classification with different terms.

    Before a buyer agrees to any post-settlement possession period, the lender needs to confirm in writing what is permitted. Do not rely on a loan officer’s verbal reassurance. Get it from underwriting. This applies to jumbo and portfolio loans as much as to conforming products, and the rules vary by lender.

    Pennsylvania: how it is usually handled

    In Pennsylvania transactions, post-settlement possession is generally documented through an addendum to the agreement of sale, prepared alongside the standard forms. The agreement should be negotiated and attached before the deal is deep into the process — not improvised the week of settlement, which is when it most often gets rushed and underspecified.

    Pennsylvania closings are typically handled through a title company rather than attorneys on both sides, so the possession terms need to be tight in the written addendum itself. There is no attorney review period to catch a vague clause after the fact.

    New Jersey: attorney review changes the rhythm

    New Jersey contracts pass through a statutory attorney review period, and both sides typically have counsel throughout. That is an advantage for rent-backs: your attorney can draft the possession agreement with the specificity it deserves, address insurance and liability directly, and coordinate with the title company on how the escrow is held.

    It is worth raising the possession request early — ideally in the offer itself — so it is inside the negotiation rather than a late request that a buyer may reasonably resist once they have planned their move.

    What the agreement must actually say

    A serviceable rent-back agreement covers, at minimum:

    • Exact end date and time. Not “approximately 30 days.” A date and an hour.
    • Daily rate and how it is paid. Often set to approximate the buyer’s daily carrying cost — principal, interest, taxes, and insurance — sometimes with a premium for longer stays.
    • Escrow held from seller proceeds. A meaningful sum retained at settlement, released after the buyer confirms the property was vacated in the agreed condition.
    • Holdover penalty. An escalating daily rate if the seller does not leave on time. This is the clause that actually gets people out.
    • Condition standard. The property is delivered in the same condition as at settlement, ordinary wear excepted, with a walkthrough at the end of the possession period.
    • Repairs and maintenance. Who handles a failed HVAC system or a roof leak during the possession period, and at what dollar threshold responsibility shifts.
    • Insurance. The buyer carries owner’s coverage; the seller should carry a renter’s or tenant policy for their own contents and liability. Both should confirm with their carriers in writing.
    • Utilities and access. Who pays, and on what notice the buyer may enter for measurements or contractor visits.

    Where rent-backs go wrong

    Three failure modes account for most problems. The first is the seller who does not leave, usually because their new construction slipped. The second is a major system failure during the possession period with no agreed allocation of responsibility. The third is a dispute over condition at the end — damage from the seller’s own move-out, which is precisely why the escrow and the final walkthrough exist.

    Every one of these is manageable with a well-drafted agreement negotiated early. None of them is manageable with a handshake and a friendly assumption that it will work out.

    Frequently asked questions

    How much should a seller pay for a rent-back?

    It is negotiable and varies with the deal. A common approach sets the daily rate near the buyer’s actual daily carrying cost, sometimes free for a short courtesy period and priced thereafter. In strong seller markets, short possession periods are frequently granted at no charge as part of the negotiation.

    Can a seller stay for several months after closing?

    Sometimes, but long occupancy periods raise real issues: lender occupancy requirements, potential landlord-tenant law implications, and insurance complications. Extended arrangements should be structured deliberately with counsel rather than treated as a longer version of a short rent-back.

    Does the seller become a tenant with tenant rights?

    That depends on how the agreement is written and how long the occupancy runs, and it is exactly why the document matters. A short, well-drafted post-settlement possession agreement is designed to be a limited license to occupy rather than a residential tenancy. This is a question for the attorney drafting the agreement, and it should be settled before signing, not after.

    If you are selling a home and need time after settlement, or you are writing an offer and wondering whether flexible possession could win you the house, I can structure it so both sides are protected. Reach James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Northampton Township and Richboro, Pennsylvania: A Bucks County Guide for Luxury Home Buyers

    Northampton Township and Richboro, Pennsylvania: A Bucks County Guide for Luxury Home Buyers

    Northampton Township sits in the center of Lower Bucks County, about twenty-five miles northeast of Center City Philadelphia. Its best-known village, Richboro, gives the township a recognizable name, and the surrounding areas of Holland and Churchville fill out a community that has quietly become one of the region’s most consistent choices for buyers who want space, strong public schools, and a short drive to both Philadelphia and central New Jersey. For luxury buyers, Northampton offers something increasingly hard to find: large, well-built homes on real acreage in a township that never became overbuilt.

    What Northampton Township is actually like

    Northampton is a township of villages rather than a single downtown. Richboro sits at the crossroads of Second Street Pike and Almshouse Road and functions as the commercial center. Holland, to the south, is the largest residential concentration. Churchville, to the west, holds the township’s oldest housing stock and the Churchville Nature Center, a 55-acre preserve with trails and a restored 1800s farmstead.

    What ties them together is open space. Northampton has been aggressive about preserving land, and the result is a township where subdivisions are separated by woods, farm fields, and parkland rather than running edge to edge. Tyler State Park, one of the largest state parks in southeastern Pennsylvania, borders the township to the north and gives residents nearly 1,700 acres of trails, the Neshaminy Creek, and a working farm landscape within a few minutes’ drive.

    The housing stock at the high end

    Northampton’s luxury inventory falls into three broad groups, and knowing which one you are shopping changes how you evaluate a house.

    Late-century custom estates

    The township saw substantial custom building from the 1980s through the early 2000s, and much of its highest-priced inventory comes from that era: large center-hall colonials and stone-and-stucco manor homes on one to three acres, often in small enclaves of a dozen homes or fewer. These properties tend to have the acreage and the room count that buyers want. What they need is scrutiny of systems and exteriors — roofs, HVAC, and in particular stucco and EIFS assemblies from the 1990s, which are a known regional issue and warrant a moisture inspection by a qualified specialist before you remove any contingency.

    Newer infill construction

    Because so much land is preserved, new construction in Northampton comes in small batches — a handful of homes on a subdivided parcel rather than a hundred-lot community. These offer current layouts, modern insulation and mechanicals, and often a builder warranty, but usually on smaller lots than the 1990s estates. Buyers frequently trade land for efficiency here.

    Older farmhouses and converted properties

    Scattered through Churchville and the northern edge of the township are original farmhouses, some dating to the 1700s and 1800s, occasionally with a barn or carriage structure. These are the most character-rich properties in Northampton and the most variable in condition. If you are drawn to one, budget for a specialist inspection covering structure, wiring, and any outbuildings, and confirm what is permitted before you plan an addition.

    Schools, commuting, and daily logistics

    Northampton is served by the Council Rock School District, which draws families from across Bucks County and is one of the primary reasons buyers focus on this township. Council Rock covers several municipalities, so confirm the specific elementary and secondary assignment for any address you are considering rather than assuming — boundaries do not follow township lines neatly.

    For commuting, Northampton is a driving community. Interstate 95 and the Pennsylvania Turnpike are both reachable, and the Newtown and Yardley areas connect you toward the Delaware River crossings into New Jersey. SEPTA Regional Rail service is not in the township itself; most rail commuters drive to a station in a neighboring community. If a train commute to Center City is essential to your household, map that drive at your actual departure time before you commit.

    How Northampton compares to its neighbors

    Buyers looking at Northampton are usually also considering Newtown, Yardley, Doylestown, or Warrington. A few honest distinctions:

    • Versus Newtown: Newtown has the walkable historic borough and the social center of gravity. Northampton has more land per dollar and a quieter, more residential character.
    • Versus Yardley: Yardley offers river-town charm and easier access to New Jersey and New York commutes. Northampton is more interior and more oriented toward Philadelphia.
    • Versus Doylestown: Doylestown is a destination borough with cultural institutions and a busy downtown. Northampton is less of a destination and more of a place to live well and privately.
    • Versus Warrington and Warminster: Northampton generally carries more preserved open space and larger typical lot sizes at the upper end.

    What to check before you write an offer

    A few items come up repeatedly in Northampton transactions:

    • Water and sewer. Parts of the township are on public water and sewer; others are on wells and septic. Confirm which, and if it is septic, order a full inspection and locate the system and its replacement area.
    • Stucco and exterior assemblies on 1990s-era construction, as noted above.
    • Open space and easements. A property that backs to preserved land is usually an asset, but read the easement language — some parcels carry conservation restrictions that limit what you can build.
    • Homeowners association scope. Many of the small enclaves have an association with limited but real authority over exteriors and additions.
    • Assessment versus market value. Bucks County assessments are based on an older base year; the ratio matters more than the raw number when you are estimating taxes.

    Who Northampton fits

    Northampton tends to suit buyers who want land and quiet without going as far north as central Bucks, who value the Council Rock schools, and whose commute is by car or is hybrid. It is a less obvious choice than Newtown or Doylestown, which often works in a buyer’s favor on price. It is a weaker fit for buyers who want to walk to dinner, or whose work requires a daily train into Center City.

    Frequently asked questions

    Is Richboro a separate town from Northampton Township?

    Richboro is a village and mailing address within Northampton Township, not a separate municipality. Holland and Churchville work the same way. All three share township government, services, and the Council Rock School District, so a “Richboro” address and a “Holland” address are both Northampton Township.

    Are homes in Northampton Township on well and septic?

    It varies by location. Public water and sewer serve much of the developed area, while some outlying and older properties rely on private wells and septic systems. Never assume — verify for the specific parcel, and if the property is on septic, make a full septic inspection part of your due diligence rather than relying on the standard home inspection.

    How does Northampton compare with the Main Line for a luxury buyer?

    They serve different priorities. The Main Line offers historic prestige, walkable town centers, and direct rail into Center City, generally at a higher price per square foot. Northampton typically offers more land and newer construction for the same money, in a car-oriented setting with excellent public schools. Buyers who want acreage lean Bucks; buyers who want walkability and rail lean Main Line.

    Talk through Northampton with someone who works this market

    If you are weighing Northampton Township against Newtown, Doylestown, or a move across the river, it helps to see the inventory side by side and understand what each property will actually cost to own. James Kennedy works with buyers and sellers across Philadelphia, Bucks County, and South Jersey and can walk you through current pricing, school assignments, and what is quietly available before it hits the market. Call 215-267-8479 or email jameskennedy@unlockedteam.com to start the conversation.

  • Title Insurance, Surveys, and the Settlement Table: A Luxury Buyer’s Guide to Closing in Pennsylvania and New Jersey

    Title Insurance, Surveys, and the Settlement Table: A Luxury Buyer’s Guide to Closing in Pennsylvania and New Jersey

    Most buyers put enormous energy into finding the right house and negotiating the right price, then treat closing as a formality. At the upper end of the market, that is a mistake. Higher purchase prices mean larger transfer taxes, more complex title histories, larger escrow balances, and more moving parts at settlement. The closing is also the last moment at which certain problems can be fixed without becoming permanently yours.

    This guide covers what actually happens between an accepted offer and the keys, in both Pennsylvania and New Jersey, and where luxury buyers should pay the closest attention.

    What a title search is actually looking for

    A title search is a review of the public record to confirm that the seller can convey clear ownership and to surface anything attached to the property that would survive the sale. The searcher is looking for items including:

    • Breaks in the chain of ownership — a deed that was never properly recorded, an heir who never signed off, a prior transfer with a defective signature.
    • Liens — unpaid mortgages, judgments against the owner, mechanics’ liens from contractors who were not paid, tax liens, and municipal charges.
    • Easements — utility rights of way, shared driveways, drainage rights, and access easements benefiting neighbors.
    • Deed restrictions and covenants — recorded limits on what can be built, altered, or operated on the property.
    • Open permits and municipal violations — in some jurisdictions these surface through the search or a separate municipal certification.

    On high-end properties, and especially on estate sales, historic homes, and properties that have been subdivided or expanded, these searches turn up more than they do on a routine transaction. That is precisely why the review matters.

    Title insurance: what the two policies do

    There are two policies, and buyers frequently misunderstand the difference.

    The lender’s policy

    Required by your lender if you are financing. It protects the lender’s interest in the property up to the loan amount. It does not protect you.

    The owner’s policy

    Optional, but this is the one that protects your equity. If a title defect emerges after closing — an undisclosed heir, a forged prior signature, a lien that was missed — the owner’s policy defends you and covers loss up to the policy amount. On a high-value purchase, and particularly on a cash purchase where no lender is requiring anything, an owner’s policy is the single most important protection available at closing. Cash buyers sometimes skip it to save money at settlement, which inverts the risk: they are the ones with the most equity exposed and no lender policy in place at all.

    An enhanced or extended owner’s policy is available in many cases and covers additional risks. Ask what the incremental cost is; on a large purchase it is frequently modest relative to the coverage.

    Surveys, and why they matter more on larger properties

    A survey establishes the property’s actual boundaries and locates improvements relative to those boundaries. It reveals encroachments — a neighbor’s fence, shed, or driveway sitting on your land, or your improvements sitting on theirs — as well as whether structures comply with setback requirements.

    On a city rowhouse, the survey question is usually simple. On acreage, on estate properties, on lots that have been subdivided, and on any property with outbuildings, pools, walls, or long driveways, a current survey is worth the cost. A prior owner’s survey from twenty years ago does not reflect what has been built since.

    If a survey turns up an encroachment, that is a solvable problem before closing — through an easement agreement, a boundary line adjustment, or a price adjustment. After closing, it becomes a dispute with your new neighbor.

    Pennsylvania and New Jersey: how closings differ

    Who runs the closing

    In Pennsylvania, settlements are commonly handled by title companies. In New Jersey, buyers and sellers are typically represented by attorneys, and New Jersey contracts include an attorney review period after signing during which either side’s attorney can disapprove or modify the contract. If you are buying in New Jersey, engage an attorney early — that review window is short and it is a genuine opportunity.

    Transfer taxes

    Both states impose transfer taxes, and the structure differs. Pennsylvania’s realty transfer tax is levied at both state and local levels, and Philadelphia’s local rate is meaningfully higher than most surrounding municipalities. The split between buyer and seller is customary rather than fixed and is negotiable in the agreement of sale.

    New Jersey has a realty transfer fee, and higher-priced residential sales can also trigger an additional fee commonly referred to as the mansion tax. The thresholds, rates, and which party pays have been the subject of legislative change, so confirm the current rules for your specific price point rather than relying on a figure you read previously. This is one of the largest line items on a high-end New Jersey closing and should be modeled accurately before you write the offer.

    Municipal requirements

    Many New Jersey municipalities require a certificate of occupancy or continued occupancy inspection before a sale can close, covering items like smoke and carbon monoxide detectors. Some Pennsylvania municipalities have their own use-and-occupancy requirements. These are typically the seller’s obligation but they can delay a closing if not handled early.

    Reading the settlement statement

    You will receive a closing disclosure or settlement statement before closing. Read it against your contract, line by line. The items that most often need correction:

    • Property tax proration. Pennsylvania and New Jersey bill on different cycles, and some jurisdictions bill in advance while others bill in arrears. Confirm the proration reflects the correct cycle.
    • Transfer tax allocation. Verify it matches what the contract says, not what is customary.
    • Utility and fuel adjustments. On homes with oil or propane, the remaining tank contents are typically adjusted for.
    • HOA or condominium fees and capital contributions. Confirm what is prorated and what is a one-time charge.
    • Credits negotiated after inspection. Make sure every agreed credit actually appears.
    • Escrow for taxes and insurance. On a large loan, the initial escrow deposit is a significant number. Confirm it.

    The final walkthrough

    Do it, and do it as close to closing as possible. You are confirming that the property is in the condition agreed, that agreed repairs were completed, that included fixtures and appliances are present, and that systems still function. On a luxury home this list is longer — check the mechanical rooms, run the heating and cooling, test the generator if there is one, confirm pool equipment operates, and verify that any items that were to convey are actually still in the house.

    Frequently asked questions

    Do I need an owner’s title policy if I am paying cash?

    Arguably you need it more. With no lender, no one else is requiring any title protection at all, and your entire purchase price is exposed to a defect in the chain of title. The premium is a small fraction of the amount at risk.

    Can I choose my own title company?

    Generally yes — buyers typically have the right to select their title provider, subject to what the contract says and to lender requirements. If a referral comes with an affiliated business disclosure, read it and know you are not obligated to use that provider.

    How far before closing should I have my financing finalized?

    As early as possible. Jumbo financing involves more documentation and more underwriting scrutiny than a conforming loan, and appraisals on unique high-end properties take longer. Build your contract timeline around a realistic underwriting schedule rather than an optimistic one, and stay responsive to your lender’s document requests throughout.

    If you are preparing to buy in Philadelphia or South Jersey and want the closing costs, transfer taxes, and timeline modeled accurately before you write an offer, I can walk you through it. Reach James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Lansdale and North Wales, Pennsylvania: A North Penn Guide for Luxury Home Buyers

    Lansdale and North Wales, Pennsylvania: A North Penn Guide for Luxury Home Buyers

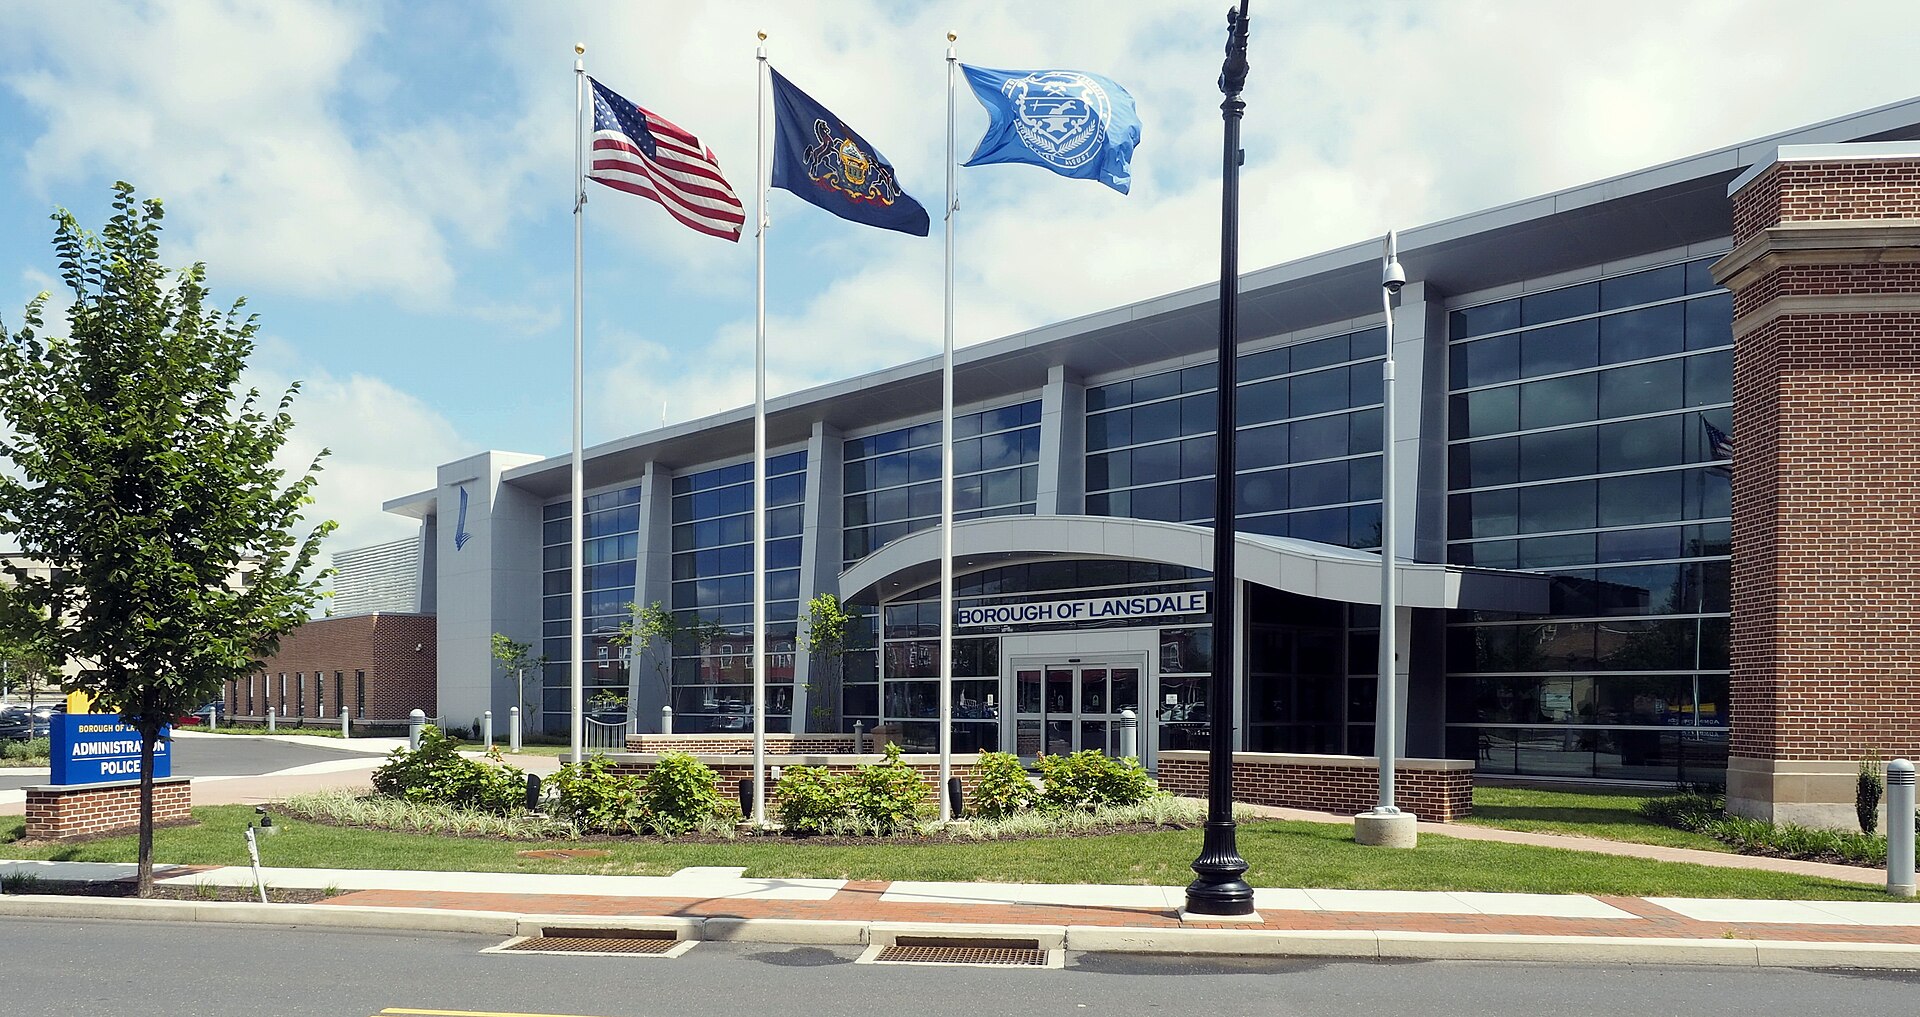
    Lansdale and North Wales sit in the heart of Montgomery County’s North Penn corridor, a stretch of Pennsylvania that gets less attention from luxury buyers than the Main Line but delivers a great deal for the money: real walkable town centers, direct rail into Center City, top-tier public schools, and a housing market that runs from restored Victorians to newer custom estates on multi-acre lots.

    Two Boroughs, Two Personalities

    Lansdale is the larger of the two — a borough with a genuine downtown, a grid of tree-lined residential streets, a brewery and restaurant scene along Main Street, and a regional rail station at its center. It has spent the last decade steadily investing in its core, and the result is a town where you can walk to dinner, a coffee shop, and the train.

    North Wales is smaller and quieter, a compact borough of about a square mile with its own train station, older housing stock, and a village feel. Both boroughs are surrounded by Upper Gwynedd, Montgomery Township, Towamencin, and Hatfield — townships that hold most of the area’s larger-lot and newer-construction inventory. When buyers say “Lansdale” or “North Wales,” they often mean a mailing address that extends well past the borough line, which is an important distinction for taxes and schools.

    Why the Township-Versus-Borough Distinction Matters

    A North Wales mailing address can sit in North Wales Borough, Upper Gwynedd Township, or Montgomery Township — each with its own tax rate, municipal services, and in some cases a different school district. Two homes a mile apart with identical addresses on paper can carry meaningfully different annual costs and different school assignments. Confirm the actual municipality and district for any specific property before you fall in love with it.

    The Housing Stock

    The high end of this market breaks into a few clear categories:

    • Restored Victorians and early-1900s homes in and near the borough cores, with wraparound porches, original millwork, and walkable locations. These are the properties that appeal to buyers who want character plus a town center.
    • Custom estates on one to five acres in the surrounding townships — the largest homes in the area, often with three-car garages, pools, and finished lower levels.
    • Newer luxury subdivisions from the 1990s through today, offering current floor plans, larger primary suites, and lower maintenance than a century-old house.
    • Executive homes on wooded lots tucked between the farm parcels that still define the northern edge of the county.

    Buyers relocating from the Main Line or from Center City are usually struck by how much house and land the North Penn corridor delivers relative to the same budget farther south and east. The trade is a longer commute and a less prestigious address, which some buyers care about a great deal and others not at all.

    Getting Around

    SEPTA’s Lansdale/Doylestown Regional Rail line runs through both boroughs, with stations in Lansdale, North Wales, and nearby Pennbrook, giving a one-seat ride into Jenkintown, Temple, and Center City. That rail access is the single most underrated feature of this market for buyers who want suburban space without giving up a train commute.

    By car, the area sits near Route 309, the Northeast Extension of the Pennsylvania Turnpike, and Route 202 — which means straightforward drives to the King of Prussia and Blue Bell business corridors, the Lehigh Valley, and Doylestown. Philadelphia International Airport is a longer haul than it is from the Main Line; budget accordingly if you travel often.

    Schools, Parks, and Daily Life

    The North Penn School District serves Lansdale, North Wales, and much of the surrounding township area and is one of the larger and better-regarded districts in Montgomery County. Portions of the broader area fall into other districts, so verify assignment by address. There is also a substantial private and parochial school presence within a short drive, plus easy access to the independent schools clustered around Blue Bell, Ambler, and Doylestown.

    For recreation, the area is well served by county and township parks, the Liberty Bell Trail, and nearby Peace Valley Park with its reservoir, trails, and boating. Golf and swim clubs are plentiful. The Lansdale downtown restaurant and brewery scene has grown noticeably, and Doylestown, Ambler, and Skippack are all short drives for a wider dining night out.

    What to Check Before You Buy

    • Well and septic on larger parcels. Many township properties on acreage are not on public water and sewer. Test the well, inspect the septic system, and understand the replacement cost and the setback rules if you plan an addition or a pool.
    • Stucco and EIFS. As in much of the Philadelphia suburbs, homes built in the 1990s and 2000s with synthetic stucco should have a moisture intrusion inspection regardless of how the exterior looks.
    • Original systems in historic homes. Knob-and-tube remnants, oil heat, and undersized electrical service are all common in borough Victorians. Insurers care about these; find out before you go under agreement.
    • Underground oil tanks. Any older home originally heated with oil should be checked for a buried or abandoned tank.
    • Homeowners associations. Newer subdivisions often carry HOA fees and architectural restrictions. Read the documents during your due diligence period, not after.
    • Assessment versus market value. Montgomery County assessments date to an older base year. Understand how your expected purchase price relates to the assessed value and whether an appeal is warranted.

    Who This Market Fits

    Lansdale and North Wales work well for families who want a strong public school district plus a walkable town center, for buyers who need real acreage without moving to Bucks or Chester County, for professionals commuting to Blue Bell, King of Prussia, or Center City by rail, and for anyone who wants their budget to buy meaningfully more house. They are less suited to a buyer whose priority is a prestige address or a five-minute drive to Center City.

    Frequently asked questions

    How does Lansdale compare with the Main Line for a luxury buyer?

    The Main Line generally offers older prestige, a denser concentration of very high-end homes, and a shorter trip into Center City. The North Penn corridor typically offers more land and more square footage for the same budget, along with strong public schools and a genuine small-town downtown. Buyers who care most about lot size and value tend to prefer Lansdale and North Wales; buyers who care most about address and proximity tend to prefer the Main Line.

    Is the train commute practical?

    For most people, yes. Both boroughs have their own Regional Rail stations on the Lansdale/Doylestown line with direct service into Center City. Many buyers here drive to a suburban office most days and take the train on the days they need to be downtown.

    What is the biggest mistake buyers make in this market?

    Assuming the mailing address tells them the municipality and school district. A North Wales or Lansdale address can sit in several different townships with different tax rates and, in some cases, different schools. Always confirm by parcel, not by postal address.

    Considering Lansdale, North Wales, or the wider North Penn area? I can pull current inventory across the boroughs and surrounding townships, confirm the municipality and school assignment for any address, and walk you through what your budget actually buys here versus elsewhere in the region. Reach James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Selling a Luxury Home From Out of State: A Remote Seller’s Guide for Philadelphia and South Jersey

    Selling a Luxury Home From Out of State: A Remote Seller’s Guide for Philadelphia and South Jersey

    Plenty of high-end homes in Philadelphia and South Jersey are sold by owners who no longer live in them. A job relocation happened a year ago. A second home became a first home somewhere warmer. An inherited property sits three states away. Selling a luxury property remotely is entirely workable — but it requires a different operating plan than selling a house you can walk through every morning.

    Decide early how decisions will get made

    The single biggest source of friction in a remote sale is decision latency. Offers, inspection responses, repair negotiations, and appraisal issues all run on short clocks. Before the property goes on the market, settle three things:

    • Who decides. If more than one owner is involved — siblings, a trust, spouses in different cities — agree in advance who has authority and what requires a group conversation.
    • How you will be reached. Establish the channel and the realistic response window across time zones.
    • What is pre-approved. Set advance parameters: a price floor, a repair credit ceiling, an acceptable settlement window. This lets your agent respond in hours rather than days.

    Consider a limited power of attorney — carefully

    If travel to settlement is impractical, a limited or specific power of attorney can allow someone to sign on your behalf. This is not a casual step. Title companies and lenders have their own requirements about the form, the recording, and how recently it was executed, and rules differ between Pennsylvania and New Jersey. Raise it with your real estate attorney and the title company early, not the week of closing. Many out-of-state sellers instead use remote or mail-away closings, where documents are notarized locally and returned — often the simpler path.

    Get the property presentation-ready without being there

    Vacant homes need more preparation, not less

    An empty luxury home shows its flaws. Scuffs, uneven paint, dated fixtures, and odd room proportions all read louder without furniture. At the high end, professional staging is usually worth the cost on a vacant property; buyers in this segment are buying a vision of living there, and empty rooms make that harder.

    Build a local vendor bench

    You will need reliable people on the ground: a cleaner, a landscaper, a handyman, a painter, and someone who can respond if a pipe leaks or an alarm trips. Your agent should be able to coordinate this, but agree upfront on how vendors get authorized and paid so that small jobs do not stall waiting for approval.

    Keep the property genuinely maintained

    Lawn and snow service, seasonal HVAC checks, and someone physically checking the house on a schedule are not optional. A vacant house that looks neglected invites lower offers, and a vacant house that is actually neglected invites real damage.

    Handle the vacancy risks

    • Insurance. Standard homeowners policies often restrict or exclude coverage once a home has been vacant for a set period. Tell your carrier the property is vacant and ask specifically about a vacancy endorsement or a vacant-property policy. Do not assume existing coverage carries over.
    • Water and freeze protection. In a Northeast winter, an unheated or unmonitored vacant home is a burst-pipe claim waiting to happen. Keep heat on, and consider a monitored temperature and water sensor.
    • Security and access. Use a documented showing system so you know who entered and when. Remove or secure valuables, and be thoughtful about interior photos if security is a concern.
    • Mail and deliveries. Forward mail and stop deliveries; accumulation signals vacancy from the street.

    Understand the tax and withholding mechanics before you list

    Out-of-state sellers face requirements that resident sellers do not, and they surprise people at settlement if raised late:

    • New Jersey requires nonresident sellers to address estimated gross income tax at closing, typically through the GIT/REP forms, with an estimated payment or an exemption claim filed at the time of deed recording.
    • Pennsylvania and Philadelphia impose realty transfer taxes, with the city and school district portions making Philadelphia’s combined rate notably higher than most of the surrounding suburbs. Who pays what is negotiable but customarily split.
    • Federal capital gains treatment depends heavily on whether the property was a primary residence, a second home, or a rental, and on your ownership and use history. Inherited property has its own basis rules.

    None of this is one-size-fits-all. Have your CPA or tax attorney review your specific situation before listing, so that your net-proceeds expectations are based on real numbers.

    Insist on a documentation-heavy marketing package

    Remote sellers cannot answer a buyer’s question by walking down the hall, so the listing itself has to answer more questions up front. That means professional photography and video, a floor plan, drone or aerial imagery where the lot matters, and clear documentation of improvements, warranties, and system ages. A pre-listing inspection is often worth considering for a vacant property, because it lets you address surprises on your own schedule instead of under a negotiating deadline.

    Plan for inspection and appraisal from a distance

    Expect to receive an inspection report you cannot personally verify. Your agent should walk the property and photograph or video every flagged item so you are responding to evidence rather than adjectives. On the appraisal, make sure your agent supplies the appraiser with a package of comparable sales and a list of improvements — particularly important for distinctive high-end homes where automated comparisons fall short.

    Frequently asked questions

    Do I have to attend settlement in person?

    Usually not. Most out-of-state sellers close by mail-away package or, where permitted, remote notarization, and in some cases through a properly drafted power of attorney. The right method depends on the title company, the lender on the buyer’s side, and state rules, so confirm the approach early rather than the week of closing.

    Should I leave the house empty or stage it?

    At the luxury price points, staging a vacant home is generally worth the cost. Empty rooms photograph poorly, make scale hard to read, and draw attention to imperfections. Even partial staging of the primary living spaces, kitchen, and primary suite makes a measurable difference in how the home presents.

    What is the most common mistake remote sellers make?

    Underestimating carrying costs and decision speed. A vacant luxury home costs money every month in taxes, insurance, utilities, and upkeep, and slow responses to offers and inspection requests can cost real dollars. Setting pre-approved parameters before listing solves most of it.

    If you own a home in Philadelphia or South Jersey and are selling it from out of state, James Kennedy can manage the preparation, vendors, marketing, and negotiation on the ground so you are not doing it by guesswork. Call 215-267-8479 or email jameskennedy@unlockedteam.com to talk through your situation.