
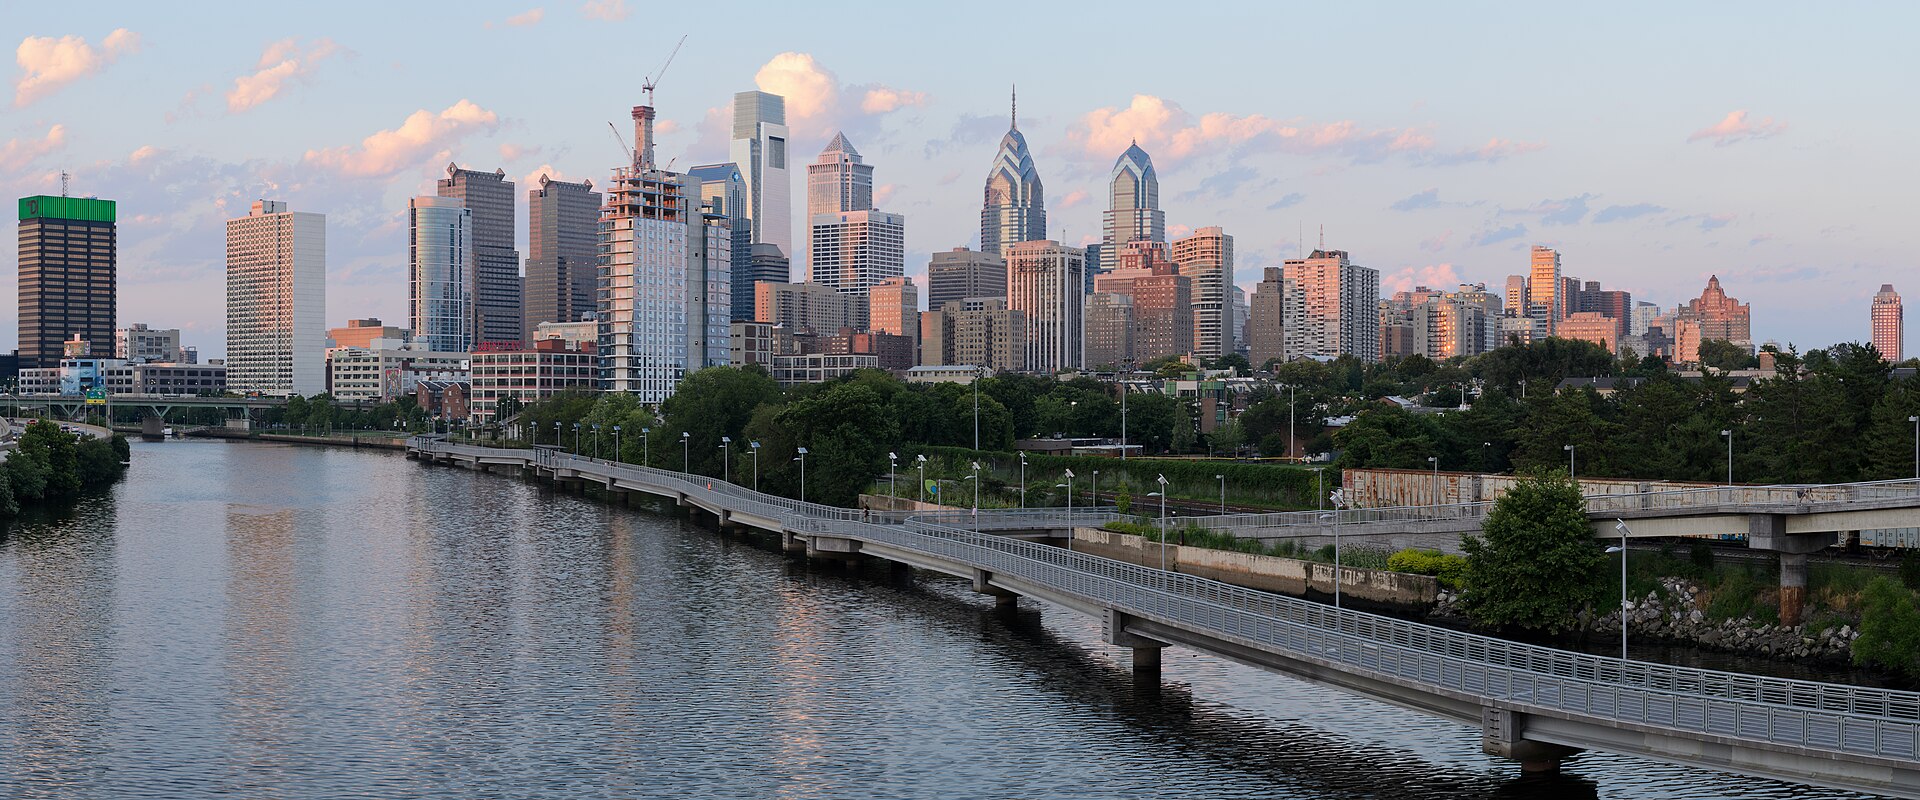
Most buyers shopping for a luxury apartment in Philadelphia assume every building is a condominium, where a purchase conveys a deed to a specific unit. A small number of the city’s most established buildings, concentrated mostly around Rittenhouse Square and a few other Center City blocks, are instead cooperatives—a fundamentally different ownership structure that is far more common in cities like New York but does exist here. Understanding how a co-op actually works matters before writing an offer, because the financing, the approval process, and even what you legally own are all different from a condo purchase.
Co-op vs. Condo: The Basic Legal Difference
In a condominium, a buyer purchases a deed to a specific unit along with an undivided interest in the building’s common areas. In a cooperative, a buyer does not receive a deed at all. Instead, the buyer purchases shares in a corporation that owns the entire building, and those shares come with a proprietary lease giving the shareholder the right to occupy a specific unit. This distinction sounds technical, but it shapes almost everything else about the transaction: how financing works, how the building is governed, and how much control the building’s board has over who is allowed to buy in.
Financing a Co-op Purchase
Because a co-op buyer is purchasing shares rather than real property, traditional mortgages do not apply in the same way. Instead, buyers typically use a share loan, a specialized form of financing secured by the shares and the proprietary lease rather than by a deed. Not every lender offers share loans, so buyers should confirm financing availability and terms early, ideally before touring units seriously, since the pool of lenders familiar with Philadelphia co-op transactions is smaller than the pool of lenders offering conventional or jumbo mortgages. Co-op boards also frequently impose their own minimum down payment requirements, often well above what a conventional lender would require, and some limit the percentage of the purchase price that can be financed at all.
The Board Approval Process
This is the step that surprises buyers coming from a condo background. A co-op board typically has broad discretion to approve or reject a prospective buyer, and that review goes well beyond a condo association’s standard background and financial check. Buyers should expect to submit a detailed financial package—tax returns, bank and investment statements, employment verification, and personal and financial references—and in many buildings, to sit for a formal interview with the board. Boards generally cannot discriminate on protected legal grounds, but they can decline an applicant based on financial qualifications or a subjective sense of fit, and they are not required to explain a rejection. Because this process can take weeks and carries real uncertainty, purchase contracts for co-ops are typically written with a board approval contingency, and buyers should build the timeline into any related sale or move.
Monthly Maintenance Fees and What They Cover
Instead of a condo fee, co-op owners pay a monthly maintenance charge, which typically covers not just building operations, staff, and reserves but also, in most Philadelphia co-ops, the building’s underlying mortgage debt service and property taxes, since the corporation itself is the taxpayer of record on the building. This means a co-op’s maintenance fee is often higher in absolute terms than a comparable condo fee, but it can also mean the shareholder’s individual property tax bill is folded into that single payment rather than assessed separately. Buyers should ask for several years of the building’s financial statements and reserve fund history, and should specifically ask about the building’s underlying mortgage, if any, since that debt is a shared obligation of every shareholder.
Reselling a Co-op Unit
Resale works differently too. Because a buyer of your unit will also need board approval, a co-op sale generally moves on a somewhat different timeline than a condo sale, and pricing can be affected by the perception of how selective and how slow a given building’s board is known to be. Well-run, established co-op buildings near Rittenhouse Square tend to hold value well among buyers who understand and want the building’s particular character, but the buyer pool is inherently smaller than for a comparable condominium, which is worth factoring into both purchase and long-term resale planning.
Property Taxes and the Co-op Structure
Because the co-op corporation, not the individual shareholder, is typically the taxpayer of record, owners do not receive a separate Philadelphia property tax bill the way a condo owner does. Instead, each shareholder’s proportional share of the building’s property tax obligation is built into the monthly maintenance charge. This has practical implications for buyers evaluating the Philadelphia homestead exemption and other owner-occupant tax programs, since eligibility and application can work differently for co-op shareholders than for deeded owners, and buyers should confirm the current treatment with the building’s managing agent and a qualified tax professional before assuming the same tax benefits apply as they would in a condominium.
Due Diligence Documents to Request
Before making an offer on a co-op unit, ask for the building’s proprietary lease and bylaws, at least two to three years of audited financial statements, the current reserve fund balance, minutes from recent board and shareholder meetings, and a summary of any pending litigation, special assessments, or major capital projects, such as roof, facade, or elevator work. Because the corporation’s overall financial health directly affects every shareholder’s maintenance obligation and the marketability of the shares, a buyer’s attorney experienced in cooperative transactions should review these documents closely, ideally before the buyer’s financial package is submitted to the board for approval.
Frequently asked questions
Are there many cooperative buildings in Philadelphia?
Co-ops are far less common in Philadelphia than in cities like New York, but a small number of established buildings, several near Rittenhouse Square, are organized this way. A local agent can identify which specific buildings are cooperatives versus condominiums before you tour.
Can I rent out a co-op unit in Philadelphia?
Subletting policies are set by each building’s board and vary widely, with many Philadelphia co-ops restricting or prohibiting rentals altogether. Confirm the building’s specific sublet policy before assuming you will be able to rent the unit in the future.
Is a co-op a good idea for an investor or a part-time resident?
Generally no. Board approval requirements, financing limitations, and frequent restrictions on subletting make most Philadelphia co-ops better suited to full-time owner-occupants than to investors or occasional second-home buyers.
If you are considering a cooperative purchase in Philadelphia or want help understanding a specific building’s board process and financials, contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com.