Category: Buying

  • Malvern, Pennsylvania: A Chester County Town Guide for Luxury Home Buyers

    Malvern, Pennsylvania: A Chester County Town Guide for Luxury Home Buyers

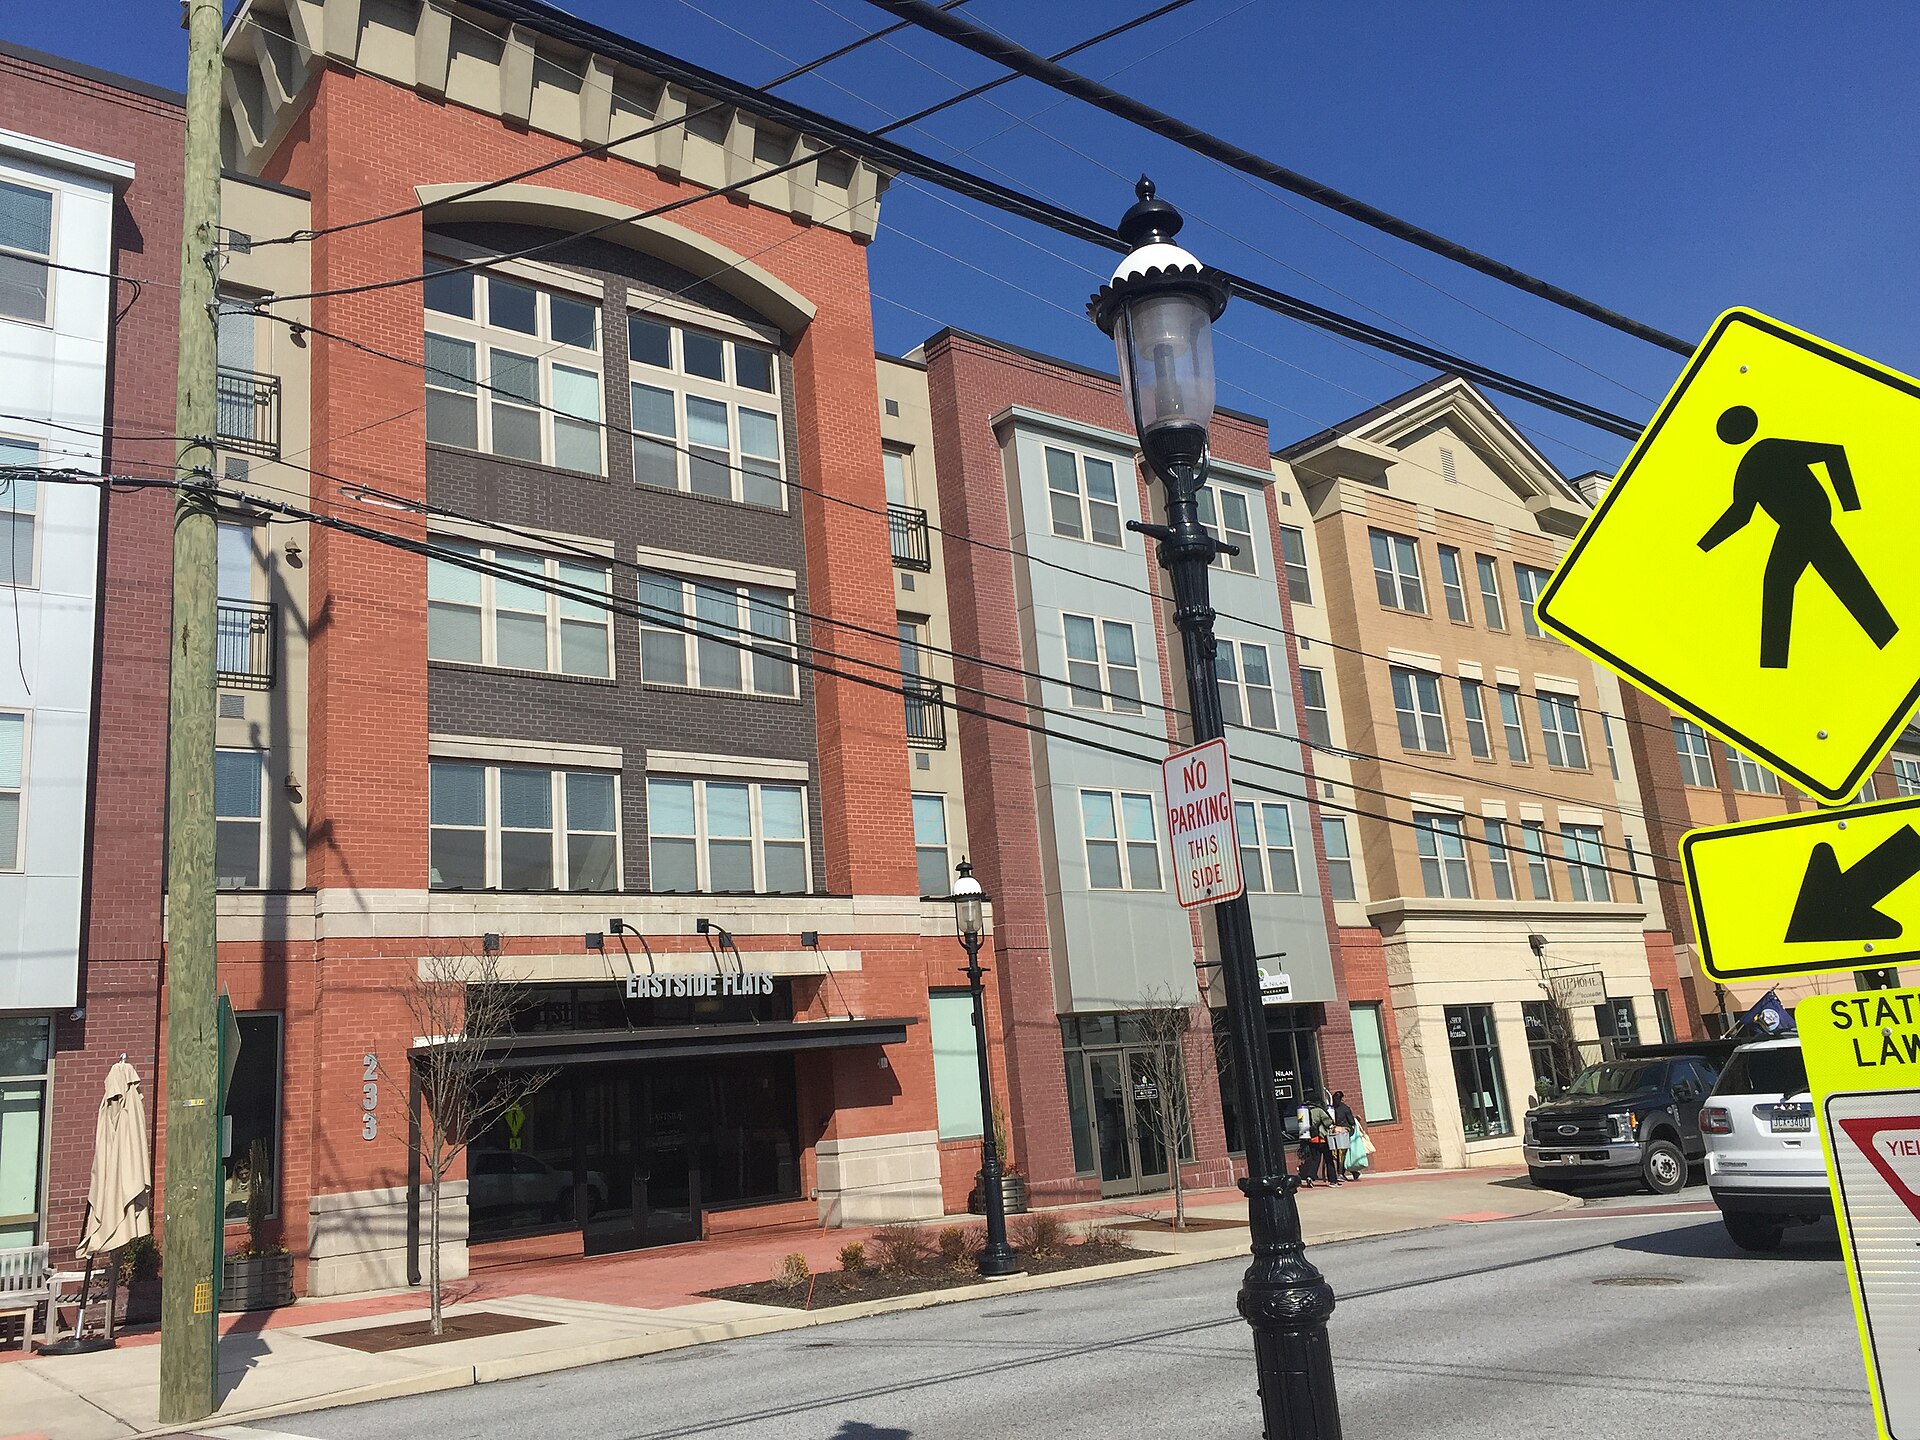
    Malvern sits a little further out the Paoli/Thorndale regional rail line than the classic Main Line towns, in Chester County proper, and it has built a reputation of its own: a compact, walkable historic downtown paired with one of the region’s stronger corporate and life-sciences employment bases nearby. For luxury buyers who want small-town scale without giving up commuter rail access, Malvern is worth a serious look.

    Where Malvern fits geographically

    Malvern Borough itself is small, but the name is often used more broadly to describe the surrounding area of East Whiteland and Charlestown Townships, which extend the town’s school districts and character into a wider swath of luxury inventory. This distinction matters for buyers: a Malvern mailing address can mean anything from a walk-to-town Victorian in the borough to a large estate lot on several acres well outside it.

    The housing stock

    Malvern’s market is genuinely varied:

    • In-borough historic homes — Victorian and early 20th-century houses within walking distance of downtown and the train station, prized for walkability more than lot size.
    • Newer luxury developments — Malvern has seen meaningful new construction in the past two decades, with planned communities offering larger, modern floor plans and community amenities.
    • Estate properties on acreage — moving out toward Charlestown and the surrounding countryside, buyers find larger parcels with more privacy, often with equestrian or conservation-adjacent land nearby.

    Why buyers choose Malvern

    The town’s draw is largely economic: Malvern and the surrounding Great Valley corridor host a concentration of corporate offices and life-sciences employers, which has made it a natural landing spot for executives and professionals who want a short commute to work without sacrificing the option of a train ride into Center City. Add a genuinely walkable downtown with local restaurants and shops, and Malvern offers a version of small-town living that still feels connected.

    Schools and community

    Most of Malvern falls within the Great Valley School District, which is a significant draw for families relocating to the area and a factor that shows up directly in home values across the district’s boundaries. Buyers should always confirm which district and specific school catchment a property falls into, since boundaries can shift between otherwise similar-looking streets.

    Getting around

    Malvern’s train station on SEPTA’s Paoli/Thorndale Line gives commuters a direct regional rail option into Center City Philadelphia, while the town’s proximity to Route 30, the Route 202 corridor, and the Pennsylvania Turnpike makes it convenient for drivers heading toward King of Prussia, the broader Great Valley employment corridor, or points further west into Chester County.

    The pace of change in Malvern

    Like much of the Great Valley corridor, Malvern has absorbed real growth over the past two decades as corporate campuses and life-sciences employers have expanded nearby. That growth has brought new restaurants and retail into the downtown core alongside the older storefronts, and it has pushed new luxury construction into the surrounding townships. Buyers who last looked at Malvern years ago may find both the town center and the surrounding housing options meaningfully different today.

    Taxes and municipal considerations

    As with any Chester County purchase, property tax rates and municipal services can vary between Malvern Borough and the surrounding townships, even for properties that share a Malvern mailing address. Buyers should request current tax figures and confirm which municipality and school district a specific property falls under before comparing it against other listings, since a like-for-like price comparison can be misleading if the tax burden differs.

    What to weigh before buying

    • Borough vs. township — confirm whether a property is inside Malvern Borough or in the surrounding townships, since taxes, ordinances, and walkability can differ meaningfully.
    • New construction vs. historic — buyers choosing between a newer development home and an in-borough historic property should weigh maintenance and character trade-offs carefully; a historic home inspection should specifically address older systems and any prior renovations.
    • Commute pattern — buyers who work in Great Valley’s corporate corridor may prioritize proximity to Route 202 over walking distance to the train station, and vice versa for Center City commuters.

    How Malvern compares to nearby towns

    Buyers cross-shopping Malvern often also consider Berwyn or Wayne along the Main Line for a similar rail-served, walkable-downtown feel, or West Chester for a larger, more urban borough experience with its own restaurant and retail scene. Malvern tends to appeal most to buyers whose work is centered in the Great Valley corridor rather than exclusively in Center City.

    Frequently asked questions

    Is Malvern considered part of the Main Line?

    Not traditionally. The Main Line refers specifically to towns along the original Pennsylvania Railroad’s Main Line corridor further east, such as Bryn Mawr, Villanova, and Wayne. Malvern sits further west in Chester County along the Paoli/Thorndale Line, though it shares some of the same commuter-suburb character.

    What draws luxury buyers to Malvern specifically?

    The combination of a walkable historic downtown, regional rail access to Center City, and proximity to the Great Valley corporate corridor is the core appeal. It suits buyers who want small-town scale with a strong local employment base nearby, rather than buyers whose priority is exclusively a Center City commute.

    Does Malvern have newer luxury construction, or is it mostly historic homes?

    Both exist. The borough itself skews historic, while the surrounding townships have seen more recent luxury development, including planned communities with larger modern floor plans. The right fit depends on whether a buyer prioritizes historic character and walkability or newer construction and acreage.

    For a closer look at current Malvern inventory, or to compare it against other Chester County and Main Line towns, contact James Kennedy at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Buying and Selling at the Same Time: A Luxury Homeowner’s Guide to Managing the Move

    Buying and Selling at the Same Time: A Luxury Homeowner’s Guide to Managing the Move

    For most luxury homeowners in Philadelphia and South Jersey, the next purchase does not happen in a vacuum — it happens while selling the home they already own. Coordinating two significant transactions at once is one of the most common sources of stress at the high end of the market, and also one of the most solvable. With the right sequencing, financing structure, and negotiation strategy, a simultaneous buy-and-sell can be orderly rather than chaotic. This guide walks through the main approaches and the trade-offs of each.

    The three basic strategies

    Sell first, then buy

    Selling first gives you certainty: you know exactly what your current home yielded, your proceeds are in hand, and you shop as a non-contingent buyer — a meaningful advantage when competing for coveted properties. The trade-off is housing between transactions. Common solutions include negotiating a post-settlement occupancy (rent-back) with your buyer, taking a short-term rental, or timing settlements close together. At the luxury level, rent-backs are often achievable because buyers of significant homes tend to have flexible timelines themselves.

    Buy first, then sell

    Buying first means you move once, on your schedule, and never risk being without a home. The challenge is carrying two properties and funding the purchase before your equity is unlocked. Affluent buyers have more tools here than most:

    • Bridge financing secured by the departing residence, repaid at its sale.
    • Home equity lines of credit established on the current home before it is listed.
    • Securities-backed lines of credit, which let buyers borrow against investment portfolios without selling positions or triggering gains.
    • Recasting a mortgage after the sale — buying with a larger loan, then applying sale proceeds to reduce the balance and payment.

    Each option has costs and suitability considerations, so coordinate with your lender and financial advisor early — ideally before you begin touring homes.

    The contingent purchase

    A home-sale contingency — making your purchase conditional on selling your current home — protects you from owning two properties, but it weakens your offer, especially for the most desirable listings where sellers can choose cleaner terms. Contingent offers work best when your current home is already under contract, when the home you are buying has been on the market a while, or when you can strengthen other terms such as price, deposit, and flexibility on settlement dates.

    Sequencing the two transactions

    The cleanest simultaneous moves are engineered backwards from the settlement dates. A few principles help:

    • Prepare the sale before you shop. Complete pre-listing preparation — staging decisions, repairs, photography — so your home can go live the moment your purchase timeline demands it.
    • Line up back-to-back or same-week settlements where possible, and build cushion days between them so a delay on one side does not cascade.
    • Use occupancy agreements as shock absorbers. A short rent-back on your sale, or delayed occupancy on your purchase, buys flexibility that money alone cannot.
    • Mind state differences. In New Jersey, the attorney review period adds a step after signing that Pennsylvania transactions do not have, which affects how quickly each side becomes firm. Cross-river moves between Philadelphia and South Jersey need calendars built with both processes in mind.

    Keeping leverage on both sides

    The paradox of a simultaneous move is that you want strength as a seller and as a buyer at the same time. A few habits protect your position: avoid signaling urgency in either negotiation; price your sale realistically rather than testing the market when your purchase depends on it; and keep your financing structure private until terms are agreed. Working with one agent who sees both sides of your move — rather than two uncoordinated ones — keeps strategy consistent and prevents one transaction from quietly undermining the other.

    The logistics layer

    Luxury moves involve more than furniture: art, wine collections, pianos, and household staff schedules all need lead time. Book specialty movers early, plan insurance coverage for items in transit, and decide what conveys with the sale well before negotiations begin so exclusions are documented cleanly. If a short gap between homes is unavoidable, climate-controlled storage and furnished interim rentals are far easier to arrange with weeks of notice than days.

    Frequently asked questions

    Should I sell my home before buying a new one?

    Selling first offers financial certainty and makes you a stronger, non-contingent buyer, but requires a housing plan for the gap — often solved with a rent-back from your buyer. Buying first suits owners with the financial capacity to carry or bridge two homes. The right answer depends on your liquidity, risk tolerance, and how rare your target home is.

    What is a bridge loan and do I need one?

    A bridge loan is short-term financing secured by your current home that funds a new purchase before your sale closes, repaid from sale proceeds. It is one of several tools — alongside HELOCs and securities-backed lines — that let luxury buyers purchase first. Whether it is right for you depends on carrying costs, timing, and your broader financial picture.

    Do home-sale contingencies work in the luxury market?

    They can, but they are weakest on the most competitive listings, where sellers prefer clean offers. Contingent offers succeed more often when your current home is already under contract or when you compensate with stronger price and terms. An experienced agent can gauge how a specific seller will weigh the contingency.

    Planning a move that involves both selling and buying? James Kennedy helps Philadelphia and South Jersey luxury homeowners engineer both transactions as one coordinated strategy — timing, financing structure, and negotiation. Call 215-267-8479 or email jameskennedy@unlockedteam.com for a confidential consultation.

  • Swarthmore, Pennsylvania: A Delaware County Town Guide for Luxury Home Buyers

    Swarthmore, Pennsylvania: A Delaware County Town Guide for Luxury Home Buyers

    Ask people who know Delaware County where its most quietly beautiful town sits, and Swarthmore comes up again and again. Built around the leafy campus of Swarthmore College — itself a nationally recognized arboretum — this small borough offers something increasingly rare: a genuinely walkable village center, a direct rail line to Center City Philadelphia, and a housing stock of stone colonials, Victorians, and Tudor revivals set on mature, tree-canopied streets. For luxury buyers who want character and community over sprawl, Swarthmore deserves a serious look.

    The setting: a town inside an arboretum

    Swarthmore’s identity is inseparable from the college that anchors it. The Scott Arboretum spreads across the campus, and its influence spills into the surrounding neighborhoods — the borough’s streets are lined with mature oaks, beeches, and flowering specimen trees that give even short walks a park-like feel. The Crum Woods, a wooded stream valley along Crum Creek, borders the campus and offers trails that residents treat as their own backyard.

    The effect on the residential streets is striking. Homes here are framed by landscape in a way that newer luxury communities spend decades trying to replicate. For buyers who value setting as much as square footage, this is Swarthmore’s signature advantage.

    The housing stock: character over volume

    Swarthmore is a small borough, and its inventory reflects that. Turnover is modest, and the best homes often attract attention quickly. What you will find, when homes do come to market, includes:

    • Stone and brick colonials from the early twentieth century, many with slate roofs, deep porches, and generous center-hall floor plans.
    • Victorians and shingle-style homes near the village center, prized for their detail and their walk-to-everything locations.
    • Tudor revivals and arts-and-crafts homes on the borough’s quieter streets, often on larger, beautifully planted lots.
    • A limited number of newer and expanded homes, typically renovations that preserve original facades while modernizing interiors.

    Because the borough is nearly built out, scarcity does much of the work of preserving value. Buyers should be prepared to act decisively when the right property appears, and sellers benefit from a market where distinctive homes rarely linger.

    The village center and daily life

    Swarthmore’s compact downtown sits directly across from the campus and the SEPTA station. The town center has grown noticeably livelier in recent years, with a farmers market, independent restaurants and cafes, a cooperative grocery, and community events that draw residents through the seasons. The college adds a steady calendar of lectures, concerts, and performances open to the public — a cultural amenity that most towns of this size simply cannot offer.

    Commuting and connectivity

    The Swarthmore station on SEPTA’s Media/Wawa Regional Rail line puts Center City within a comfortable train ride, making the borough practical for professionals who split time between home and a Philadelphia office. Drivers reach I-476 (the Blue Route) in minutes, which opens up the Main Line, the Philadelphia International Airport, and the broader region. For a town that feels tucked away, Swarthmore is remarkably well connected.

    Schools

    The borough is served by the Wallingford-Swarthmore School District, which has long been a draw for families and a meaningful support for property values. As with any luxury purchase, buyers weighing school considerations should look at fit for their own family rather than rankings alone — but the district’s reputation is a consistent part of why demand for Swarthmore homes stays strong.

    Who Swarthmore fits best

    Swarthmore rewards a particular kind of buyer: one who wants architectural character, walkability, and an engaged community more than gated privacy or new-construction finishes. Academics and professionals connected to the college, families drawn by the schools, and downsizers who want village life without leaving the Philadelphia area all compete for the same limited inventory. Buyers seeking large modern estates on multiple acres will generally look toward other parts of Delaware and Chester counties — nearby Wallingford, Media, and Newtown Square offer larger parcels — but for in-town elegance, Swarthmore has few regional peers.

    Advice for buyers and sellers

    For buyers, preparation matters more here than in high-inventory markets. Have financing fully arranged, know your must-haves, and work with an agent who hears about Swarthmore homes before they are broadly marketed. Older homes also reward careful due diligence: slate roofs, stone foundations, and vintage systems are part of the charm, and a thorough inspection helps you price their care into your offer.

    For sellers, presentation should honor the home’s character. Buyers come to Swarthmore for authenticity, so marketing that highlights original detail, landscape, and the walk-to-village lifestyle consistently outperforms generic staging. Because current market conditions vary street by street and season by season, a tailored pricing analysis matters more than any rule of thumb.

    Frequently asked questions

    Is Swarthmore a good place to buy a luxury home?

    Yes, for buyers who prize character, walkability, and community. Swarthmore offers distinguished early-twentieth-century architecture, an arboretum setting, strong schools, and rail access to Center City. Its small size means limited inventory, which supports long-term value but requires buyers to be ready to move quickly.

    How is the commute from Swarthmore to Center City Philadelphia?

    Swarthmore has its own station on SEPTA’s Media/Wawa Regional Rail line with direct service to Center City, and drivers can reach I-476 in minutes for access to the Main Line and Philadelphia International Airport. Most residents consider the commute one of the town’s practical strengths.

    What kinds of homes are available in Swarthmore?

    The borough’s stock centers on stone and brick colonials, Victorians, Tudor revivals, and arts-and-crafts homes, many on mature, planted lots near the village center. Large new-construction estates are rare; buyers wanting acreage typically look to surrounding Delaware and Chester County townships.

    Thinking about buying or selling in Swarthmore or elsewhere in Delaware County? James Kennedy specializes in luxury real estate across Philadelphia and South Jersey and can share current market data, off-market opportunities, and a pricing strategy tailored to your home. Call James at 215-267-8479 or email jameskennedy@unlockedteam.com to start the conversation.

  • Brigantine, New Jersey: A Luxury Buyer’s Guide to the Jersey Shore’s Quiet Barrier Island

    Brigantine, New Jersey: A Luxury Buyer’s Guide to the Jersey Shore’s Quiet Barrier Island

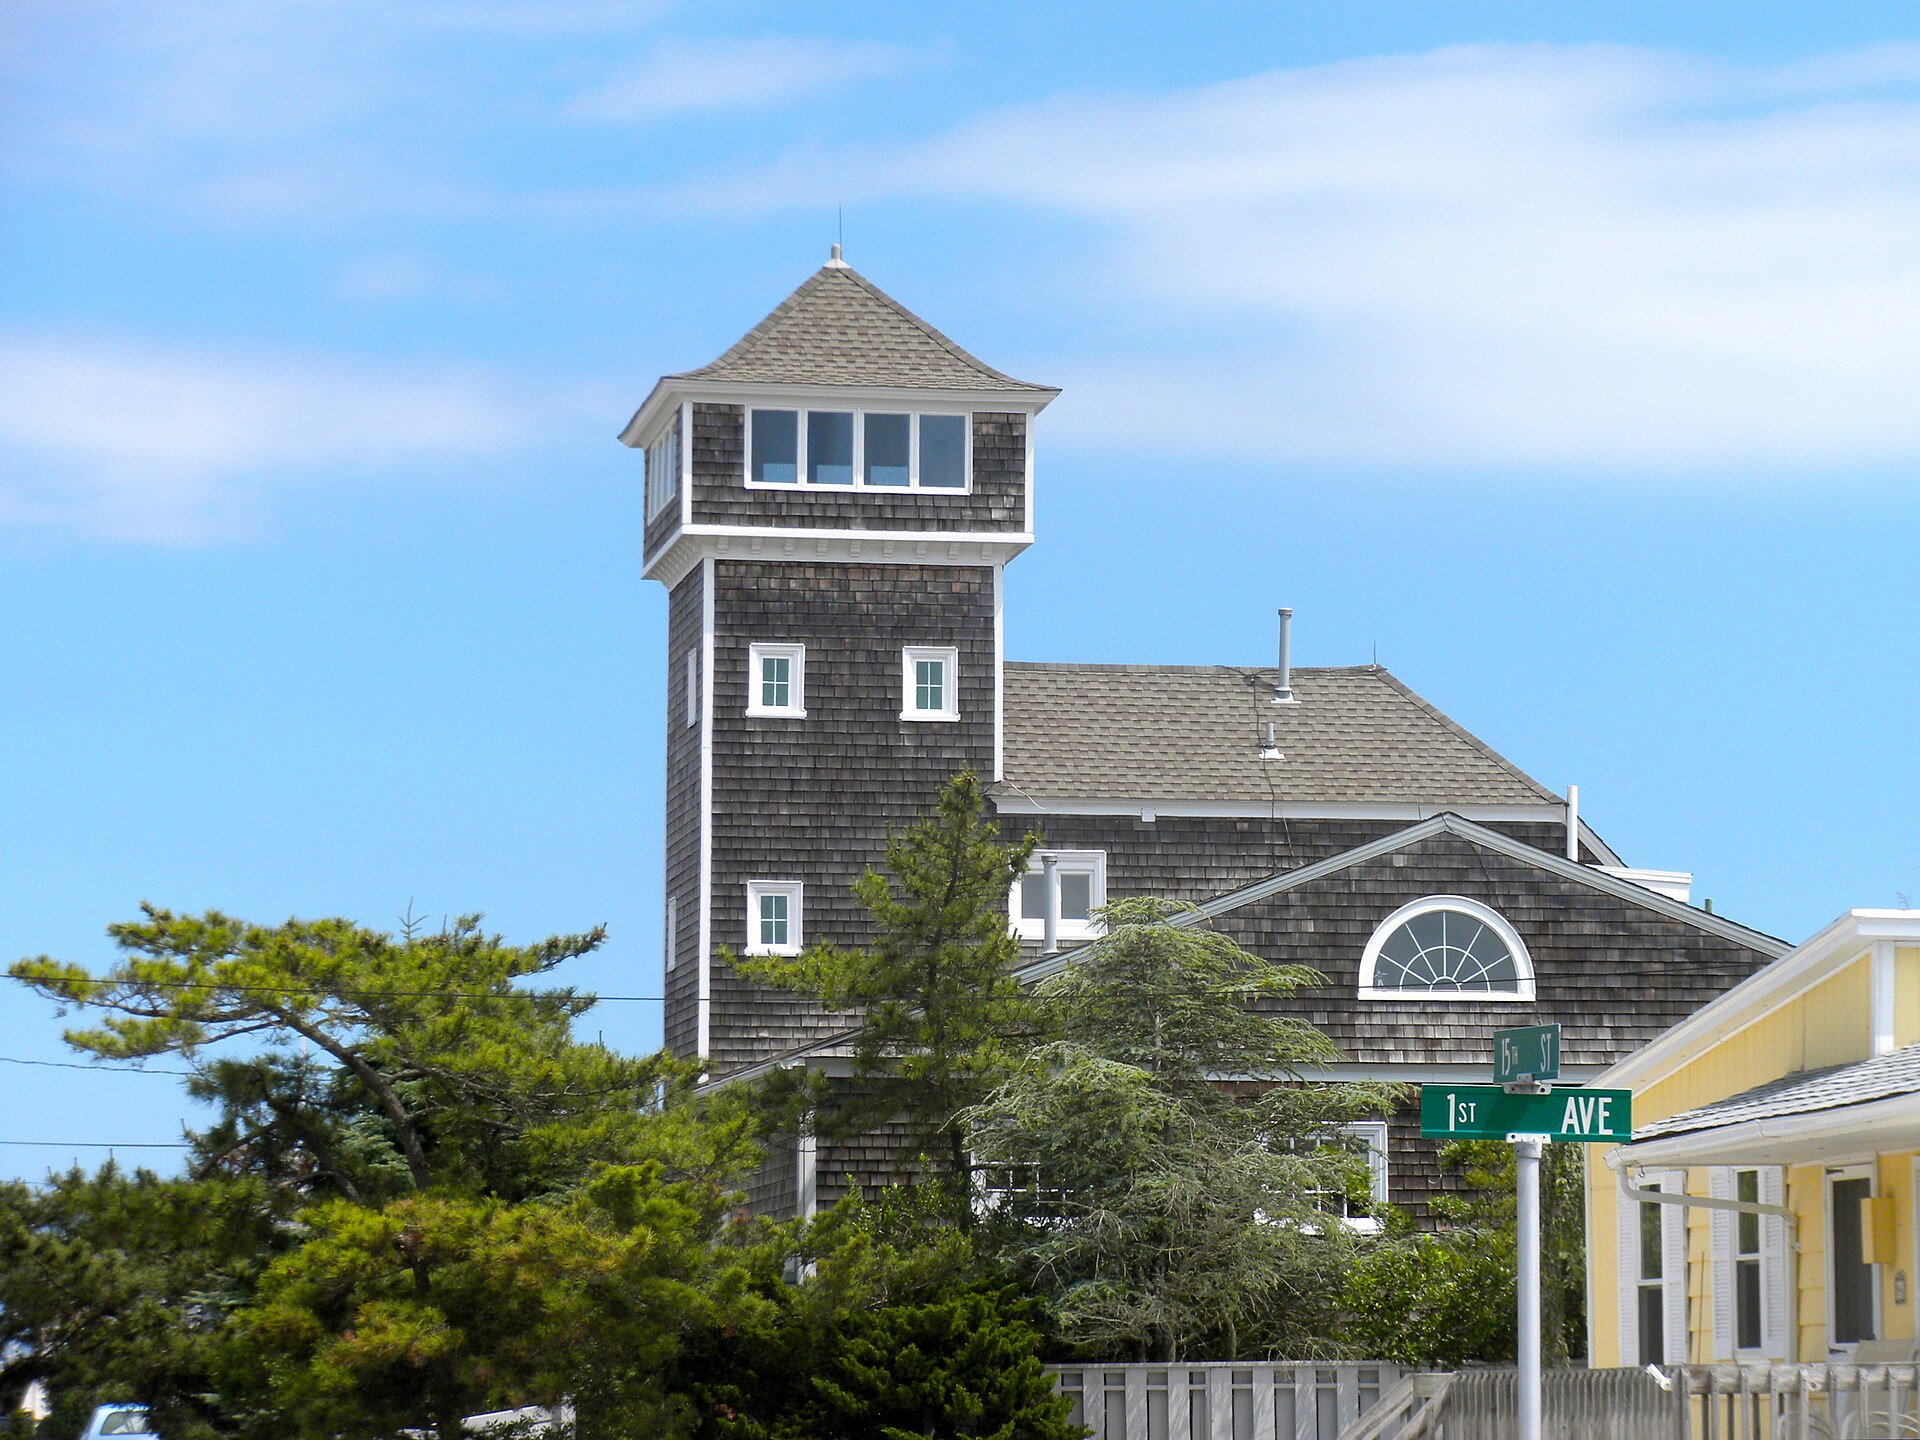
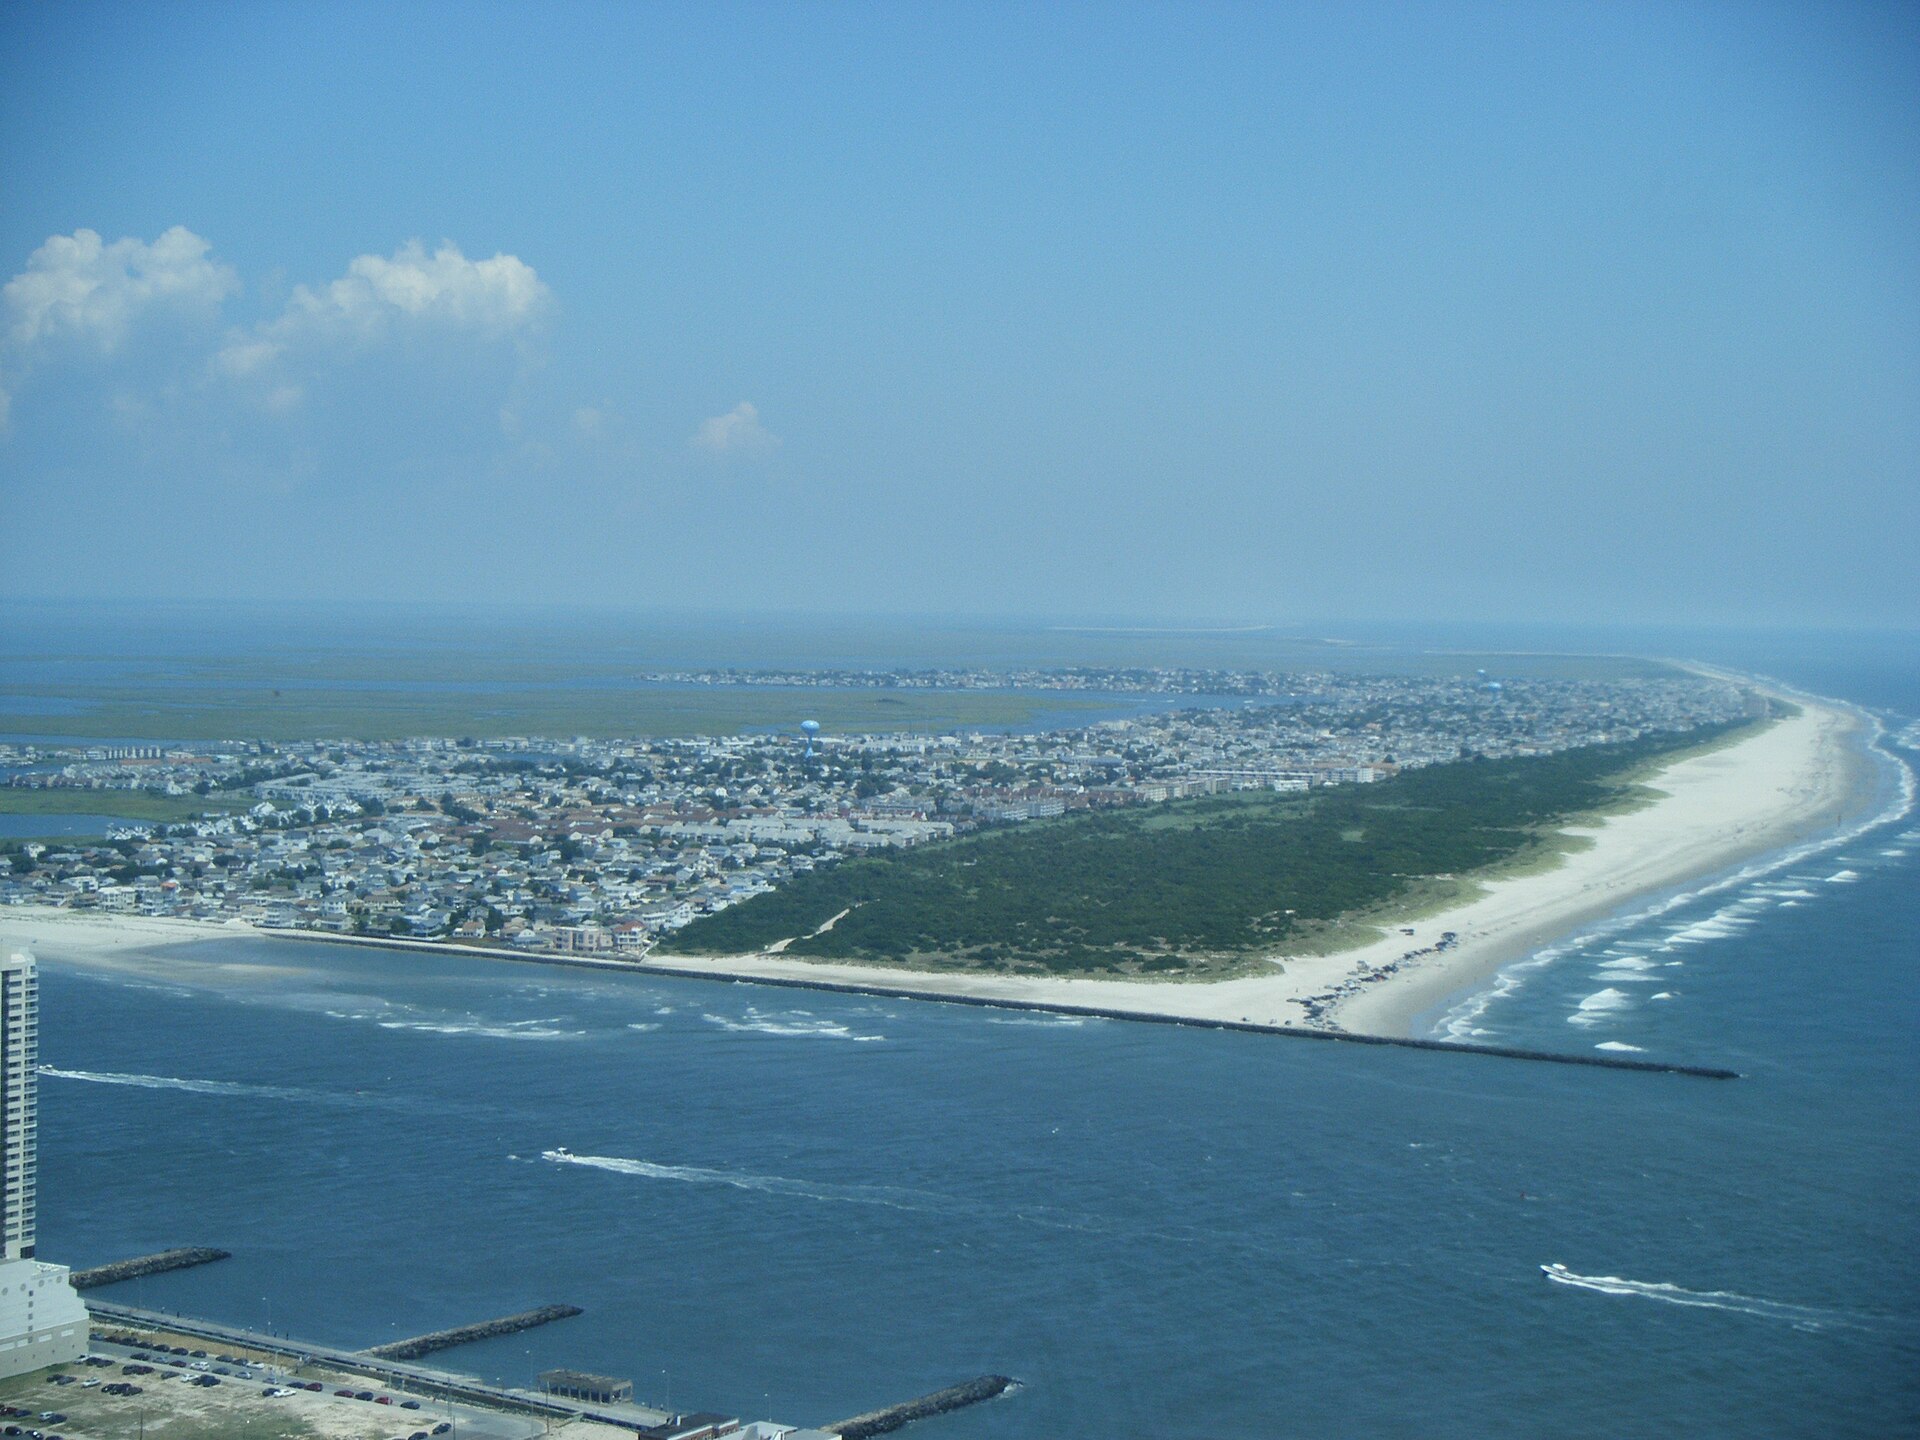
    Just north of Atlantic City, separated from the mainland by a short causeway, Brigantine occupies its own barrier island and has cultivated a reputation as one of the Jersey Shore’s more understated luxury markets. It lacks the boardwalk-and-casino energy of its neighbor to the south, and that is precisely the point: Brigantine draws buyers who want wide beaches, a protected natural landscape, and a genuinely residential, year-round community feel, without sacrificing proximity to Atlantic City’s dining, entertainment, and airport access.

    A Different Kind of Shore Town

    Many South Jersey shore towns cluster tightly around a commercial strip or boardwalk. Brigantine is built differently. Much of its northern end is occupied by the Edwin B. Forsythe National Wildlife Refuge, which permanently protects thousands of acres of marsh and dune habitat from development. That protected land does two things for buyers: it guarantees the area will never be overbuilt the way some coastal towns have been, and it gives residents direct access to some of the least crowded beaches and best birdwatching on the entire New Jersey coast.

    The Housing Stock

    Brigantine’s luxury inventory centers on oceanfront and bay-front homes, many of them substantial custom builds constructed or renovated in the last two decades to modern coastal-construction standards. Because the island is a genuine barrier island, elevation, flood zone designation, and construction type are especially important considerations for luxury buyers here, more so than in shore communities set further back from open water. Buyers should expect homes built on pilings, impact-rated windows, and other resilient construction features to be the norm rather than the exception among newer luxury properties.

    Bay Side Versus Ocean Side

    Brigantine offers meaningfully different lifestyles depending on which side of the island a buyer chooses. Oceanfront and ocean-block properties offer direct beach access and unobstructed ocean views, generally commanding the highest prices on the island. Bay-side properties, many with private docks, appeal strongly to boating buyers and often provide calmer water for kayaking, paddleboarding, and small-craft access, along with some of the area’s best sunset views. Buyers who plan to keep a boat should weigh bay-side access carefully, since not every property offers deep-enough water or a usable dock without further investigation.

    How Brigantine Compares to Other South Jersey Shore Towns

    Buyers comparing shore markets often weigh Brigantine against towns like Avalon, Stone Harbor, or Ocean City. Those towns offer more established downtown shopping districts and, in some cases, higher name recognition, but they also come with denser development and, especially in July and August, considerably more traffic and crowding. Brigantine’s trade-off is fewer boutiques and restaurants within its own borders in exchange for more open beach, more preserved land, and a noticeably quieter pace, while still being close enough to Atlantic City to access a full range of dining and entertainment when desired.

    Year-Round Versus Seasonal Living

    Unlike some shore towns that empty out significantly after Labor Day, Brigantine maintains a real year-round population, supported by its own school system and a business district that operates on a more consistent basis than purely seasonal shore towns. That said, the population and traffic still swell considerably in summer months, and buyers considering full-time residency should visit in both peak season and the off-season to get an accurate sense of the town’s rhythm across the year.

    Proximity to Atlantic City

    Brigantine’s location just across the inlet from Atlantic City is one of its most practical advantages. Buyers get a quieter, more residential setting while remaining minutes from Atlantic City’s casinos, restaurants, entertainment, and Atlantic City International Airport, which offers a level of convenience that towns further down the shore cannot match.

    What to Investigate Before Buying

    • Flood zone designation and current flood insurance costs for the specific property
    • Whether the home meets current base flood elevation requirements or would need to be raised
    • Bulkhead condition and dock permitting for bay-front properties
    • Rental history and local short-term rental regulations, if income potential is part of the plan

    Resale and Rental Potential

    Oceanfront and bay-front luxury homes on Brigantine have historically appealed both to full-time residents and to buyers interested in seasonal rental income, given the island’s proximity to Atlantic City’s tourism draw. Buyers weighing a rental strategy should confirm current local ordinances on short-term rentals, HOA or association rules where applicable, and realistic occupancy expectations outside of peak summer months before assuming any specific income figure.

    Frequently asked questions

    Is Brigantine connected to Atlantic City by road?

    Yes. Brigantine is connected to Atlantic City by the Brigantine Boulevard causeway, making the drive between the two just a few minutes under normal conditions.

    Does the wildlife refuge limit where homes can be built on the island?

    The Edwin B. Forsythe National Wildlife Refuge occupies a significant portion of northern Brigantine and is permanently protected from development, which effectively caps how much the island’s footprint can grow. Existing residential areas outside the refuge are unaffected by this restriction.

    Are flood insurance costs a major factor in owning on Brigantine?

    Because Brigantine is a barrier island, flood zone designation and insurance costs are an important part of evaluating any property here, and they can vary meaningfully from one address to another based on elevation and construction. Buyers should get specific flood insurance quotes for any property under serious consideration rather than relying on general assumptions.

    If Brigantine or another Jersey Shore luxury market fits what you are looking for, James Kennedy can walk you through the specifics of the island’s oceanfront and bay-side options. Reach him at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Kennett Square, Pennsylvania: A Chester County Town Guide for Luxury Home Buyers

    Kennett Square, Pennsylvania: A Chester County Town Guide for Luxury Home Buyers

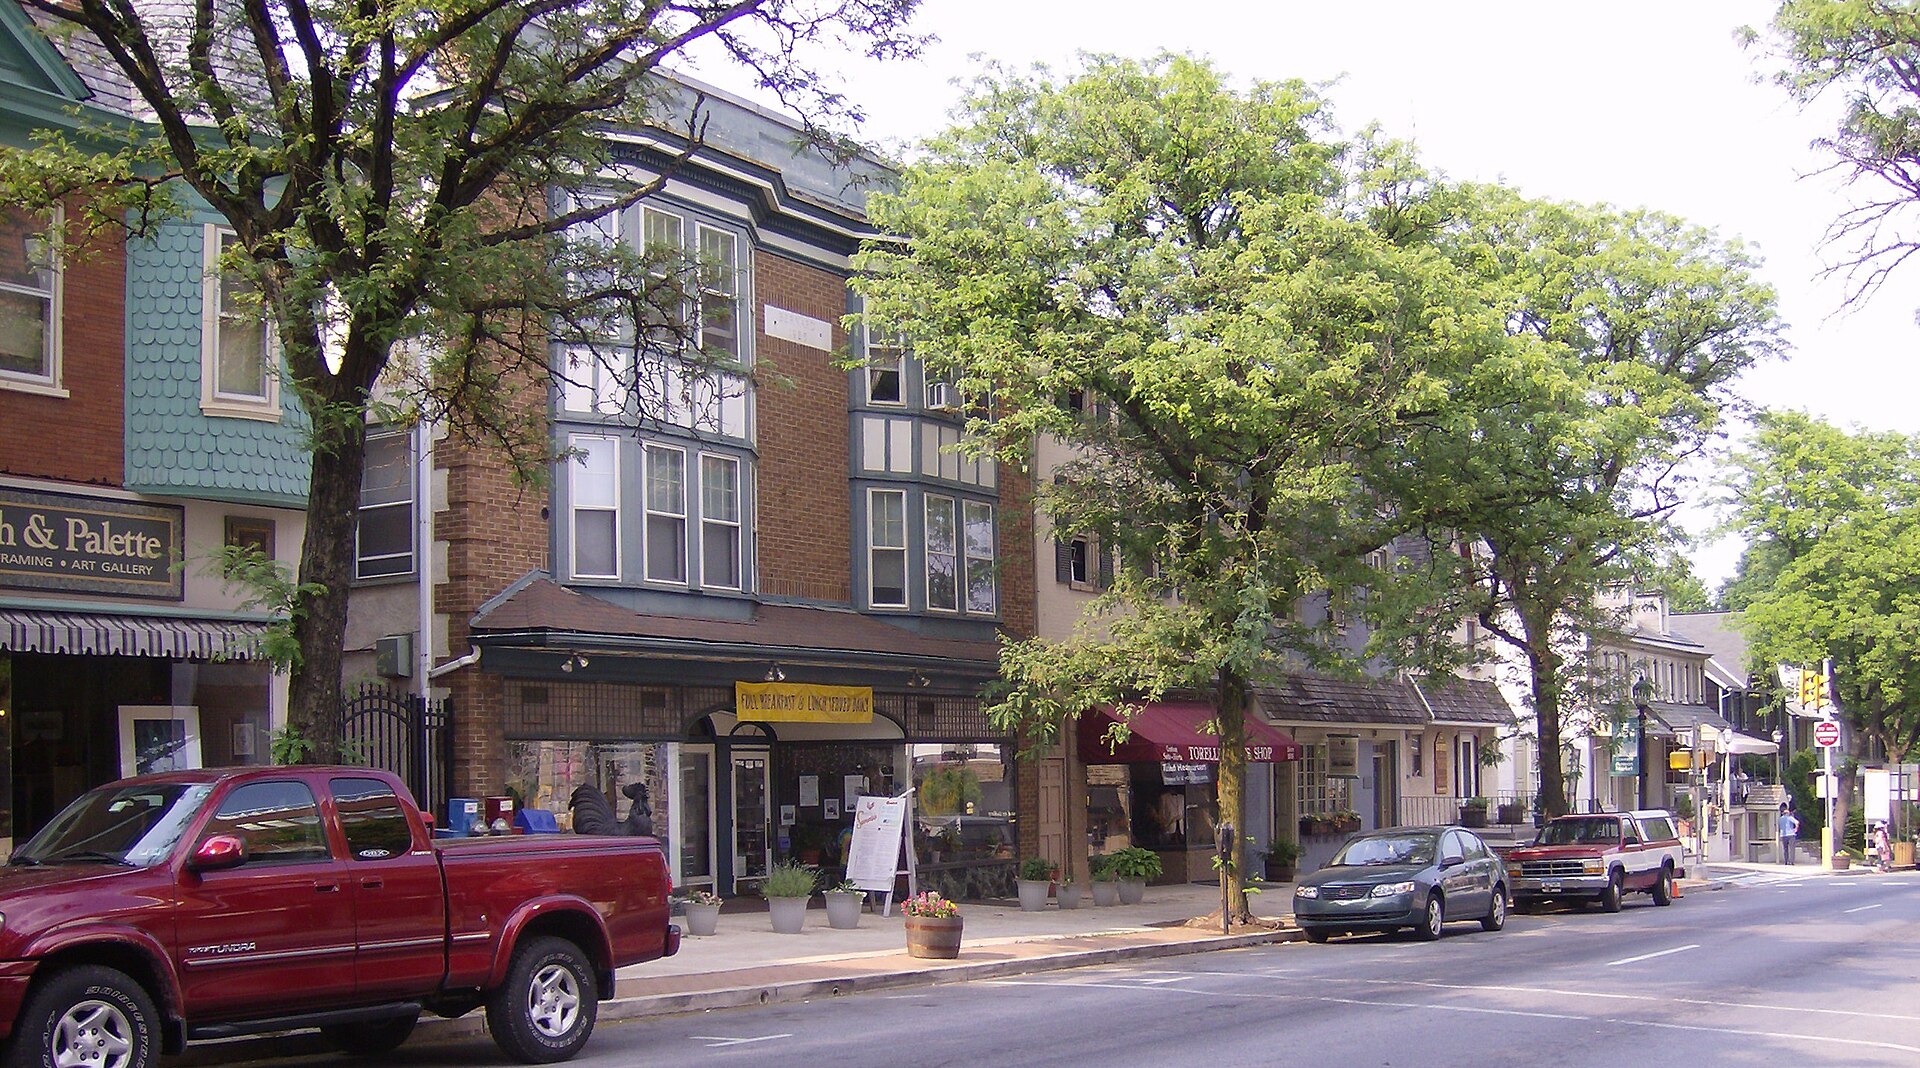
    Kennett Square sits in southern Chester County, roughly thirty-five miles from Center City Philadelphia, and has built a reputation well beyond its size thanks to its mushroom-farming heritage, a genuinely charming walkable downtown, and its proximity to Longwood Gardens. For luxury buyers who want a small-town feel with real culinary and cultural amenities, rather than a purely bedroom-community suburb, Kennett Square is worth serious consideration.

    What Draws Luxury Buyers to Kennett Square

    Unlike some Chester County towns that are primarily residential with a small commercial core, Kennett Square’s downtown functions as a genuine destination. State Street is lined with independent restaurants, wine bars, and shops that draw visitors from across the region, giving residents walkable access to a level of dining and culture that is unusual for a town of its size. That downtown vibrancy, paired with the surrounding countryside, gives Kennett Square a dual identity: a real Main Street town with estate-caliber properties just outside it.

    The Housing Stock

    Luxury buyers in the Kennett Square area typically consider a few distinct property types. In the borough itself, restored Victorian and early twentieth-century homes offer walkable-downtown living with historic character, though lot sizes are naturally more modest than in the surrounding townships. Just outside the borough, in areas like Kennett Township and East Marlborough Township, buyers find larger properties on multi-acre lots, including converted farmhouses, custom-built estate homes, and properties with equestrian facilities or preserved open space nearby. This range means a buyer can choose between in-town walkability and rural privacy without leaving the same school district or community identity.

    Land, Privacy, and Preservation

    One of the defining features of the Kennett Square area is the amount of preserved farmland and open space surrounding it, a legacy of active land conservation efforts in southern Chester County. For buyers who want acreage, mature trees, and long sightlines without feeling isolated from a town center, this combination of preserved landscape and a lively downtown is relatively rare within a reasonable commute of Philadelphia.

    Longwood Gardens and the Cultural Landscape

    Longwood Gardens, one of the premier public gardens in the country, sits just outside Kennett Square and is a significant part of the area’s identity and appeal. Beyond Longwood, the broader Brandywine Valley is home to museums, historic sites, and preserved battlefields, giving residents a level of cultural access that goes well beyond what is typical for a rural-adjacent town of this size.

    Commuting Considerations

    Kennett Square is not a rail-commute town in the way that Main Line communities are; residents typically drive to Wilmington, West Chester, or into the Philadelphia region via Route 1 or Route 202. Buyers who prioritize a car-free commute into Center City should weigh this carefully, while those who work remotely, commute by car, or work in the Wilmington or Delaware corridor may find the trade-off entirely worthwhile given what the area offers.

    Schools and Community

    The Kennett Consolidated School District serves the borough and much of the surrounding townships, and school quality is a factor many luxury buyers weigh heavily when comparing towns. As with any town, prospective buyers should evaluate current school data and boundaries directly, since they can shift over time and vary by specific address.

    How Kennett Square Compares to Other Chester County Towns

    Buyers cross-shopping Chester County often compare Kennett Square to West Chester, which offers a larger downtown and a more urban, borough-wide walkability, or to Chadds Ford and Newtown Square, which lean more toward large-lot estate living without the same concentration of restaurants and shops. Kennett Square tends to land in between: it has a real, active downtown like West Chester, but the surrounding countryside feels closer to what buyers expect from Chadds Ford. That middle position is a large part of its appeal, since it lets a buyer avoid choosing between a lively town center and open, rural acreage.

    Who Kennett Square Fits Best

    • Buyers who want walkable small-town amenities without sacrificing acreage and privacy nearby
    • Those drawn to a strong food and wine culture in a low-key, unpretentious setting
    • Equestrian buyers or those interested in preserved farmland and open space
    • Buyers comfortable with a car-based commute rather than a rail line into the city

    Resale and Long-Term Value

    Because Kennett Square’s downtown continues to draw new restaurants and small businesses, and because the surrounding preserved land limits how much new supply can ever come to market, well-maintained properties both in the borough and on the surrounding acreage have tended to hold buyer interest over time. As with any purchase, buyers should still evaluate a specific property’s condition, lot, and location within the broader market rather than assuming the town’s overall reputation guarantees any individual home’s performance.

    Frequently asked questions

    Is Kennett Square considered part of the Main Line?

    No. The Main Line refers specifically to communities along the historic Pennsylvania Railroad line west of Philadelphia, such as Bryn Mawr and Villanova. Kennett Square is in southern Chester County and has a distinct identity built around its downtown, farmland, and proximity to Longwood Gardens rather than a rail commuting culture.

    How far is Kennett Square from Philadelphia International Airport?

    It is roughly a thirty- to forty-minute drive under normal traffic conditions, making it a practical option for buyers who travel frequently but prefer a quieter, rural setting over city or close-in suburban living.

    Are there luxury new-construction options in the Kennett Square area, or is it mostly older homes?

    Both exist. The borough and surrounding townships have a strong stock of historic and character-driven homes, while newer custom construction is also available on larger parcels in the surrounding townships, so buyers are not limited to one style or era.

    If Kennett Square or another Chester County community might fit your search, James Kennedy can help you evaluate the options against your priorities. Reach him at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Buying Land and Building a Custom Luxury Home in Philadelphia & South Jersey

    Buying Land and Building a Custom Luxury Home in Philadelphia & South Jersey

    For some luxury buyers, the right home doesn’t exist yet on the resale market. Whether it’s a specific lot, a particular layout, or amenities that simply aren’t available in existing inventory, building a custom home is a legitimate path — but it’s a meaningfully different process than buying an existing property, with its own timeline, risks, and cost structure that buyers should understand before committing.

    Finding the right lot

    In and around Philadelphia and South Jersey, buildable luxury lots are scarcer than in areas with more open land, which means the search itself can take longer than expected. Infill lots in established city neighborhoods or close-in suburbs are typically small and may come with teardown costs, easements, or zoning constraints. Larger acreage in outlying Chester County, Bucks County, or South Jersey townships offers more flexibility but often requires more work upfront: perc testing for septic suitability, well feasibility, access and right-of-way confirmation, and a clear understanding of any conservation or agricultural restrictions tied to the land.

    Before committing to a lot, it’s worth commissioning a preliminary feasibility review — covering zoning, setback requirements, floodplain status, and utility access — so you know what you can actually build before you own the land.

    Zoning, permitting, and timeline

    Custom construction timelines are driven as much by municipal process as by actual building time. Zoning approvals, variances if needed, permitting, and inspections all add time, and the process varies significantly by municipality. Some townships move through residential permitting relatively quickly; others, particularly those with historic district overlays or more involved planning commission review, can add many months to a project. Buyers should ask early — ideally before finalizing land purchase — what a realistic permitting timeline looks like for that specific municipality, not just for custom construction in general.

    Choosing a builder and architect

    At the luxury end, the relationship between buyer, architect, and builder matters enormously. Look for a builder with a specific track record in the region and, ideally, in the exact township where you’re building, since local relationships with the permitting office and familiarity with local soil and construction conditions can meaningfully affect both timeline and cost. Ask to see completed projects in person, not just photos, and speak with past clients about how change orders, delays, and budget overruns were handled — these are the moments that reveal how a builder actually operates under pressure.

    Financing a custom build

    Construction financing works differently than a traditional mortgage. Most custom builds are financed through a construction loan that disburses funds in draws tied to completed phases of work, often converting to a permanent mortgage once the home is finished. Lenders experienced in high-value custom construction in this region can be more flexible and realistic about budgets and timelines than a generalist lender, so it’s worth seeking out a lender with specific experience in luxury construction lending rather than assuming any mortgage lender can handle the process equally well.

    Budgeting realistically

    Custom construction budgets should include meaningful contingency — typically well beyond what buyers initially expect — for site conditions discovered during excavation, material cost changes, and design changes made along the way. Buyers who go in expecting some fluidity in both budget and timeline tend to have a smoother experience than those who treat the initial estimate as a fixed number.

    Frequently asked questions

    Is it faster to buy an existing luxury home or build a custom one?

    In almost every case, buying an existing home is faster. Custom construction in this region, from land purchase through move-in, commonly takes well over a year once permitting, design, and construction are all accounted for. Building makes sense when the specific home you want doesn’t exist on the resale market, not as a faster alternative to buying.

    What is perc testing and why does it matter for South Jersey and Chester County lots?

    A percolation, or “perc,” test measures how well soil absorbs water and determines whether a lot without public sewer access can support a septic system. Many rural and semi-rural lots in South Jersey and Chester County rely on septic systems, so a lot’s perc test results can determine whether — and how large a home — it can support before you even design the floor plan.

    Should I hire an architect before or after buying the land?

    Ideally, involve an architect during the lot evaluation itself, even informally. An experienced architect can flag site constraints — slope, setbacks, tree preservation requirements, floodplain issues — that affect what’s actually buildable on a given lot before you’re financially committed to it.

    If you’re considering a custom build in Philadelphia or South Jersey, James Kennedy can help you evaluate land, connect with reputable local builders, and think through the trade-offs against buying an existing luxury home. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Titling a Luxury Home: Individual, Trust, or LLC Ownership in Pennsylvania and New Jersey

    Titling a Luxury Home: Individual, Trust, or LLC Ownership in Pennsylvania and New Jersey

    One of the questions that comes up later than it should in a luxury purchase is: whose name goes on the deed? For a starter home, the answer is usually simple. For a $1 million-plus purchase — especially a second home, an investment property, or a purchase involving multiple family members — how you title the property can affect your privacy, your liability exposure, your financing options, and your estate plan. This is not tax or legal advice; it’s an overview to help you have an informed conversation with your attorney and accountant before you’re staring at a closing table with a title company asking how you want the deed to read.

    Individual ownership

    Taking title in your own name, or with a spouse as tenants by the entirety (available in both Pennsylvania and New Jersey for married couples), is the simplest and most common approach. It’s straightforward for financing — lenders are set up to underwrite individual and joint borrowers efficiently — and it avoids the added cost and complexity of maintaining a separate legal entity. The tradeoff is that your ownership is public record tied directly to your name, and the home is generally exposed to your personal liabilities the same way any other personally-titled asset would be.

    Revocable living trusts

    Many luxury buyers, particularly those already working with an estate planning attorney, title real estate in a revocable living trust. The main appeal is probate avoidance: property held in a properly funded trust typically passes to beneficiaries without going through the probate process, which can be slower and more public than a trust-based transfer. A revocable trust does not provide meaningful liability protection during your lifetime, since you generally retain control of the assets, but it can simplify what happens to the property later and keep the succession plan out of the public probate record.

    Financing a purchase in a trust is very manageable — most major lenders handle trust-titled purchases routinely — but it’s worth confirming with your lender and title company early, since document requirements (trust certification, trustee authority) add steps to underwriting that are easy to plan for but frustrating to discover at the last minute.

    LLCs and other entities

    Buyers purchasing a second home, an investment property, or a property intended for eventual rental income sometimes use an LLC. The appeal is liability containment — separating the risks of that specific property from your other personal assets — and, for some buyers, an added layer of privacy, since the LLC rather than an individual name appears on the public deed. LLC ownership comes with real tradeoffs, though: financing is more complex and often requires a commercial or portfolio lender rather than a standard conventional mortgage, insurance needs to be structured correctly for the entity, and depending on how the LLC is used, you may lose certain personal tax benefits associated with owner-occupied residences, such as capital gains exclusions on a primary residence sale. LLC ownership is far more common for investment and rental properties than for a primary or even a true second home used personally by the family.

    Questions worth asking before you decide

    • Will this be a primary residence, a true second home, or an income-producing property? The answer changes which structure makes sense and what tax treatment applies.
    • Does your estate plan already include a trust that other assets are titled in? If so, keeping real estate consistent with that plan often makes administration simpler for your family later.
    • How will you finance the purchase, and does your intended structure work with that financing? Confirm this with your lender before you’re under contract with a tight settlement timeline.
    • Do you have out-of-state co-owners, business partners, or family members involved in the purchase? Shared ownership situations often benefit from a written operating or co-ownership agreement regardless of the titling structure chosen.

    Get the right advisors involved early

    Titling decisions are ultimately legal and tax decisions, not real estate decisions, and they’re much easier to get right before closing than to unwind afterward. An estate planning attorney and a CPA who understands real estate should be part of this conversation well before your settlement date, particularly for a trust or LLC purchase where document preparation takes time. Your real estate agent’s role is to make sure the offer, the title company, and the lender all know your intended structure early enough that it doesn’t create a last-minute scramble.

    Frequently asked questions

    Does titling a home in an LLC actually protect my other assets?

    An LLC can help contain liability related to that specific property, but the protection depends on maintaining proper corporate formalities, adequate insurance, and correct structuring — it is not automatic. This is a question for your attorney, since the details matter and vary based on your full financial picture.

    Can I title a home in a trust and still get a conventional mortgage?

    Generally yes. Most major lenders routinely finance purchases for properties titled in a revocable living trust, though the underwriting process requires additional documentation, such as a trust certification. Loop in your lender and title company as soon as you know you intend to title in a trust.

    Can I change how a property is titled after I’ve already purchased it?

    In many cases, yes, through a new deed transfer, but doing so can have tax, insurance, and financing implications (including potentially triggering a due-on-sale clause with your existing mortgage, or transfer tax in some jurisdictions). Talk to your attorney before retitling a property you already own rather than assuming it’s a simple paperwork change.

    Whatever structure you and your advisors land on, James Kennedy can help make sure your real estate transaction lines up with that plan from offer to closing. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Insuring a Luxury Home: What Buyers and Sellers Should Know in Philadelphia & South Jersey

    Insuring a Luxury Home: What Buyers and Sellers Should Know in Philadelphia & South Jersey

    Insurance is easy to overlook during a luxury home purchase, especially when buyers are focused on price, financing, and inspection results. But for higher-value properties in Philadelphia and South Jersey, insurance is not simply a bigger version of a standard homeowners policy. Replacement cost, unique architectural features, flood zone exposure, and coverage gaps all work differently at the luxury level, and getting this wrong can create real financial exposure or even delay a closing. Here is what buyers and sellers should understand before insurance becomes an afterthought.

    Why Standard Policies Often Fall Short

    Many standard homeowners insurance policies cap dwelling coverage or use formulas that do not accurately reflect the true cost to rebuild a custom, historic, or architecturally distinctive home. A policy written for an average-sized home may significantly undervalue a property with high-end finishes, custom millwork, imported materials, or complex rooflines. High-net-worth and specialty insurers instead typically offer guaranteed or extended replacement cost coverage, which is designed to fully rebuild the home even if construction costs rise above the original policy limit — an important distinction after a major loss.

    Key Coverage Areas for Luxury Properties

    Dwelling and Rebuild Cost

    Rebuilding a historic Society Hill townhome, a custom Main Line estate, or a contemporary riverfront property in Philadelphia often costs meaningfully more per square foot than new standard construction, particularly when it involves matching period detail, custom stonework, or specialty materials. An accurate replacement cost estimate — sometimes requiring an independent appraisal — is essential to avoid being underinsured.

    Personal Property and Valuables

    Luxury homes frequently contain fine art, jewelry, wine collections, and other valuables that exceed the sub-limits built into standard policies. Scheduling these items individually, often with a specialty rider or a dedicated valuables policy, ensures they are covered at appraised value rather than a capped default amount.

    Liability Coverage

    Higher-value homes often come with higher liability exposure, whether from a pool, a dock, extensive property staff, or simply a higher profile that can attract litigation. Many luxury buyers pair their homeowners policy with an umbrella policy to extend liability protection well beyond standard limits.

    Additional Structures and Unique Features

    Guest houses, pool houses, boat docks, wine cellars, home theaters, and detached garages all need to be specifically accounted for in a policy rather than assumed to be automatically covered. Buyers should review exactly what is and is not included before closing.

    Flood Zones and Coastal Exposure

    For South Jersey shore properties and Philadelphia riverfront homes, flood insurance is a separate and often significant consideration. Properties in FEMA-designated flood zones typically require flood insurance to obtain a mortgage, and premiums vary widely based on elevation, construction type, and flood zone designation. Even homes outside a mapped high-risk zone can benefit from flood coverage, since standard homeowners policies generally exclude flood damage entirely. Buyers evaluating shore or waterfront property should request a flood zone determination and sample insurance quote early in the process, not after the offer is accepted.

    Historic Homes and Renovation Considerations

    Insuring a historic property in neighborhoods like Old City, Society Hill, or Chestnut Hill introduces additional nuance. Insurers may ask about the age and condition of electrical, plumbing, and roofing systems, and older systems can affect both insurability and premium cost. Buyers planning renovations should also notify their insurer during construction, since coverage needs typically shift while work is underway, and a vacant or under-renovation property may need a separate policy or endorsement.

    Timing: When to Start the Insurance Conversation

    Insurance should not wait until the week before closing. Because specialty and high-net-worth insurers often need time to properly evaluate a unique property, luxury buyers are well served by reaching out to an insurance broker as soon as an offer is accepted, and ideally even earlier if they know they are looking at flood-zone or historic properties. This gives enough time to secure an accurate quote, address any red flags the insurer identifies, and avoid last-minute financing delays, since most lenders require proof of insurance before closing.

    Frequently asked questions

    Do I need a specialty high-net-worth insurance policy for every luxury home?

    Not necessarily, but any home with a rebuild cost, valuables, or liability exposure that exceeds standard policy limits typically benefits from a specialty carrier or at minimum a careful review of coverage limits with a broker experienced in higher-value properties. The right answer depends on the specific home and the buyer’s overall asset picture.

    How early should I get an insurance quote when buying a luxury home?

    As soon as your offer is accepted, and earlier if possible for properties in flood zones or with unique architectural features. Insurance underwriting for high-value or complex properties can take longer than a standard policy, and most lenders require proof of insurance before they will clear you to close.

    Is flood insurance required for every home near the Delaware River or the Jersey Shore?

    It depends on the property’s specific FEMA flood zone designation, not just its general proximity to water. A formal flood zone determination will clarify whether flood insurance is required for financing and give you an accurate sense of the likely premium before you finalize an offer.

    Insurance is one more detail worth getting right before you close on a luxury property in Philadelphia or South Jersey. James Kennedy can connect you with experienced local insurance brokers as part of the buying or selling process — reach him at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Escrow, Title Insurance, and Transfer Tax: What Luxury Buyers and Sellers Should Know in Pennsylvania and New Jersey

    Escrow, Title Insurance, and Transfer Tax: What Luxury Buyers and Sellers Should Know in Pennsylvania and New Jersey

    Buyers and sellers spend a great deal of time thinking about price, and understandably so. But three quieter parts of every closing — escrow, title insurance, and transfer tax — can meaningfully affect the true cost of a transaction, and they scale directly with a home’s price. On a luxury purchase in Philadelphia or South Jersey, these line items are often larger, in absolute dollars, than most buyers expect. Understanding what each one actually does helps take some of the mystery out of a closing statement.

    What escrow actually means in a real estate transaction

    The word escrow gets used in two different ways during a home purchase, and conflating them is a common source of confusion. The first is the escrow deposit, sometimes called earnest money, that a buyer puts down shortly after going under contract to demonstrate good faith. That money sits with a neutral third party — typically a title company or attorney’s escrow account — until closing, at which point it’s applied toward the purchase price.

    The second use of the term refers to an ongoing escrow account that a mortgage lender sets up after closing to collect a portion of property taxes and homeowners insurance with each monthly payment, so the lender can pay those bills on the homeowner’s behalf when they come due. On a high-value home, monthly escrow contributions for taxes and insurance can be substantial, and buyers financing a purchase should ask their lender for a detailed escrow projection well before closing so there are no surprises in the first year of ownership.

    Title insurance: protecting against what you can’t see

    Title insurance protects against defects in the chain of ownership that a buyer or lender might not discover during a standard title search — things like an undisclosed heir with a claim to the property, an old unreleased lien, a forged signature somewhere in the property’s history, or a boundary dispute that predates current ownership. Unlike most insurance, title insurance is paid once, at closing, and covers the policyholder for as long as they or their heirs own the property.

    There are generally two policies involved in a financed purchase: a lender’s policy, which protects the mortgage holder’s interest and is required as a condition of the loan, and an owner’s policy, which protects the buyer’s equity and is optional but strongly recommended, particularly on a high-value home where the potential loss from a title defect is correspondingly larger. Because title insurance premiums are calculated as a percentage of the purchase price, the cost of a robust owner’s policy on a luxury home is a real number worth budgeting for early, not an afterthought at the closing table.

    Transfer tax: often the largest closing cost buyers don’t anticipate

    Both Pennsylvania and New Jersey impose a real estate transfer tax on the sale of property, calculated as a percentage of the sale price and typically split between buyer and seller by local custom, though the exact allocation is negotiable and should be addressed explicitly in the agreement of sale. Philadelphia adds its own local transfer tax on top of the state’s, making the combined rate in the city meaningfully higher than in most Pennsylvania suburbs, which is an important factor for buyers comparing a city purchase against a suburban one.

    New Jersey layers an additional Mansion Tax on residential purchases above certain price thresholds, a detail that matters directly to many luxury buyers in South Jersey given the price points this audience typically transacts at. Because these thresholds and rates are set by statute and can change, buyers and sellers should confirm the current rates and thresholds with their attorney or title company well before closing rather than relying on a prior transaction’s numbers.

    How these costs interact on a luxury deal

    On a lower-priced home, escrow, title insurance, and transfer tax might amount to a manageable, almost forgettable line on the closing statement. On a multi-million dollar purchase, the combined total of these three items can run into the tens of thousands of dollars or more, which is exactly why an experienced luxury agent and a knowledgeable real estate attorney should walk buyers and sellers through a detailed estimate of closing costs as soon as a property goes under contract, not just in the days immediately before closing.

    Frequently asked questions

    Who typically pays transfer tax in Pennsylvania and New Jersey, the buyer or the seller?

    Local custom varies, and in many Philadelphia-area transactions the tax is split evenly between buyer and seller, though this is fully negotiable and should be spelled out explicitly in the agreement of sale rather than assumed.

    Is an owner’s title insurance policy required?

    A lender’s title policy is required as a condition of financing, but an owner’s policy is optional. It is nonetheless strongly recommended, especially on a high-value home, since it protects the buyer’s own equity against title defects that a lender’s policy does not cover.

    Does New Jersey’s Mansion Tax apply to every South Jersey luxury purchase?

    It applies to residential purchases above a set price threshold established by state law, which is exactly the range many South Jersey luxury buyers transact in. Because the applicable threshold and rate can change, buyers should confirm the current figures with their attorney or title company at the time of purchase.

    If you’d like a clear, upfront estimate of escrow, title, and transfer tax costs before you make an offer or list your home, James Kennedy can walk you through the numbers for your specific transaction. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.
  • Avalon, New Jersey: A Luxury Buyer’s Guide to the Jersey Shore’s Most Refined Address

    Avalon, New Jersey: A Luxury Buyer’s Guide to the Jersey Shore’s Most Refined Address

    Avalon occupies a particular place in the hierarchy of Jersey Shore towns. It isn’t the liveliest boardwalk destination, and it isn’t trying to be. What Avalon offers instead is a consistently well-maintained beach community with wide, clean beaches, strict zoning, and a housing stock that skews heavily toward well-built, well-kept single-family homes rather than dense multi-family blocks. For luxury buyers looking at the shore, that combination of natural beauty and disciplined town management is a big part of the draw.

    The character of the town

    Avalon runs along a narrow barrier island shared with neighboring Stone Harbor, and the town’s own regulations have shaped its development pattern deliberately. Height limits, setback requirements, and a strong emphasis on dune preservation have kept Avalon from developing the high-rise condo towers found in some other shore markets. The result is a town of predominantly single-family homes, many of them substantial, custom-built properties designed for extended family gatherings and long summer stays.

    The town center along Dune Drive offers shops and restaurants without the density of a full boardwalk commercial strip, which suits buyers who want a quieter, more residential shore experience.

    Understanding Avalon’s micro-markets

    Oceanfront and ocean-block properties

    The most sought-after and expensive homes sit directly on the dunes or within the first block or two of the beach. These properties command the steepest premiums and the least inventory, so buyers who want to be within easy walking distance of the sand should expect a competitive search and be prepared to move quickly when the right property appears.

    Bayfront properties

    Avalon’s back bay offers its own luxury market, appealing to boating families who want direct water access, docks, and sunset views across the bay rather than the ocean. Bayfront homes often offer more buildable lot size for the price than comparable oceanfront parcels.

    Interior streets

    Homes set back from both the ocean and the bay still command strong prices in Avalon given the town’s overall desirability and limited inventory, but they typically offer meaningfully more value per square foot than waterfront property, making them attractive to buyers prioritizing space and a quieter block over immediate water access.

    Seasonal rhythm and rental potential

    Like most barrier-island shore towns, Avalon’s population swells dramatically in summer and quiets considerably in the off-season. Many luxury buyers use their Avalon property as a seasonal residence supplemented by weekly rental income during peak summer months, which can help offset carrying costs. Buyers considering this approach should research the town’s specific rental regulations, since barrier-island municipalities frequently adjust rules around minimum stay lengths, permits, and parking as demand evolves.

    Flood zones and construction considerations

    As with any barrier-island community, flood zone designation, elevation requirements, and windstorm insurance costs are essential parts of due diligence in Avalon. Newer construction is typically built to current FEMA elevation standards, while older homes may require a closer look at flood insurance costs and potential future elevation work. A knowledgeable local inspector and insurance agent should be part of any Avalon purchase team from the outset.

    How Avalon compares to Stone Harbor

    Avalon and Stone Harbor share the same barrier island and much of the same reputation for quality and exclusivity, but the two towns have distinct personalities. Avalon tends to have a slightly more built-up commercial strip along Dune Drive, while Stone Harbor’s downtown and its well-known bird sanctuary give it a somewhat different, more naturalistic feel. Buyers torn between the two are well served by touring both before narrowing their search.

    Frequently asked questions

    What makes Avalon different from other Jersey Shore towns?

    Avalon’s strict zoning and height limits have kept the town almost entirely low-rise and single-family in character, avoiding the dense condo development found in some other shore markets. Combined with wide beaches and a well-funded municipal government, that has helped the town maintain strong long-term desirability.

    Is Avalon primarily a summer market or does it have year-round residents?

    Avalon is predominantly a seasonal community, with population and home prices both heavily influenced by summer demand. A smaller year-round population remains, but most luxury buyers purchase Avalon property as a second home or seasonal rental property rather than a primary residence.

    How should a buyer think about flood risk in Avalon?

    Flood zone designation and elevation requirements should be reviewed carefully for any barrier-island purchase, and buyers should budget for windstorm and flood insurance costs as part of their overall carrying cost analysis, working with an inspector and insurance agent familiar with the specific island.

    If you’re exploring a purchase in Avalon or comparing it to other South Jersey shore towns, James Kennedy can help you evaluate the trade-offs between oceanfront, bayfront, and interior properties. Reach James at 215-267-8479 or jameskennedy@unlockedteam.com.